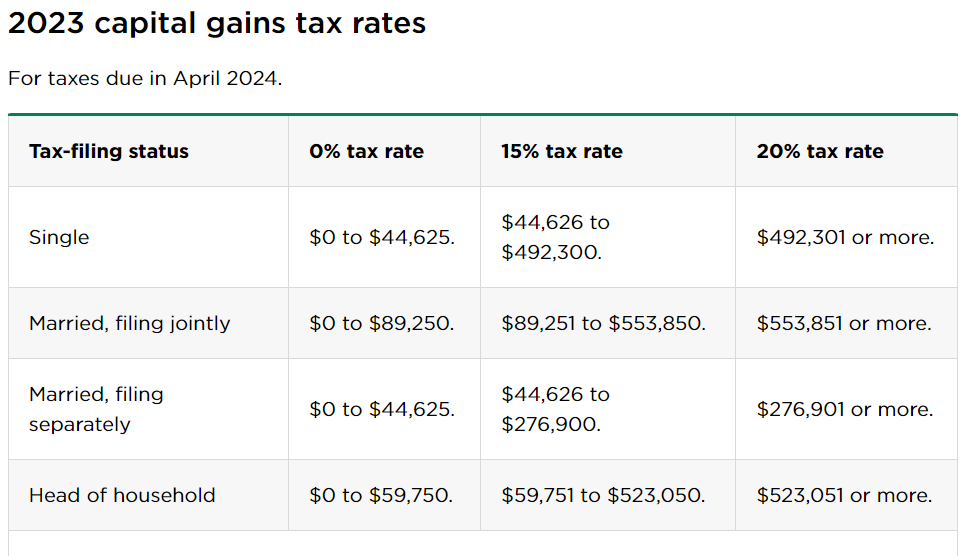I am proud to announce that I have successfully completed the CFP (Certified Financial Planner) coursework. I would like to thank all my finance and financial planning professors at @enmu Next stop: graduation in August 2024... @CFPBoard
I am proud to announce that I have successfully completed the CFP (Certified Financial Planner) coursework. I would like to thank all my finance and financial planning professors at @enmu Next stop: graduation in August 2024... @CFPBoard
In addition,
- See if a standard or itemized deduction makes sense for you.
- Hold assets for more than a year inside a taxable brokerage account. (Long-term capital gains rates)
- See if there’s any tax credits that apply to you.
*Speak with your CPA not tax advice*
Easiest way for W-2 employees to optimize their tax situation is:
- Take advantage of tax-advantaged accounts. (401k, IRA, HSA, Taxable account)
- Utilize tax-loss harvesting. (Selling a stock to claim such losses to minimize your taxable bill on other stocks sold for a gain)
Common mistake I see with IRA’s. (trad & roth) Many investors consider these accounts as an “investment.” Remember, Traditional & Roth IRA’s are “investments accounts.” You still need to pick investments and invest accordingly.
*Accounts hold funds. Investments grow your funds.*
Understanding your “why” is important. Personal finance is “personal” everyone’s goals and desires are different. Money is just a tool and it can help fund your goals & fulfill the qualities of your life such as giving to your church, paying for kids college & buying experiences.
When starting your personal finances you shouldn’t be trying to pick:
- Individual stocks
- Crypto
- NFT’s
However you should be:
- Creating a budget
- Eliminating high-interest debt
- Taking advantage of your employer match
- Trying to understand your “why” behind your money
Your employer match is essentially free money. Matching is a benefit an employer gives you to save for your retirement. Ex: Your employer offers a 4% match (dollar for dollar). You make $100,000 a year. $100,000 x 4% = $4,000. Your employer will match your $4,000 contribution.
Key notes:
401Ks must be offered by an employer. IRAs must be set up by an individual. HSAs contributions are only allowed if an individual has a “high deductible health plan.”
2023: limits (Single Filers)
401k - $22,500
IRA - $6,500
HSA - $3,850
Follow me for more👍
Key things to consider before the end of 2023:
1. Save for an emergency fund (3-6mo expenses)
2. Pay down high interest debt. (Int>5%)
3. Max out retirement accounts (401k/IRAs
4. Max out an HSA (Health Savings account)
5. Increase your savings (Vacation, Vehicle, or Downpayment)
Roth IRA and 401ks are tax-advantaged accounts but a taxable brokerage account has a tax advantage too:
Capital gains tax.
But you must hold your investments long-term (more than 1 year) to get the better tax rate.
2023 Long-Term Capital Gains rates: