$HYPE is still at least a 10x opportunity from here.
Daily active traders still only in hundreds of thousands vs platforms such as Robinhood, IBKR in the millions.
Think Hyperliquid is on the verge of going mainstream so the juiciest part of the trade is just beginning.
Took profits on HYPE after such a strong rally and rotated the proceeds back into ETH. Over the duration of the trade, HYPE was up 81% while ETH was down 29%, making the trade accretive to the portfolio’s ETH position
$PFE Bourla wanted to save money rather than getting best dual mechanism but now spending billions on losing trials.
It was all about his “ not over pay “ vision before board and activist investor.
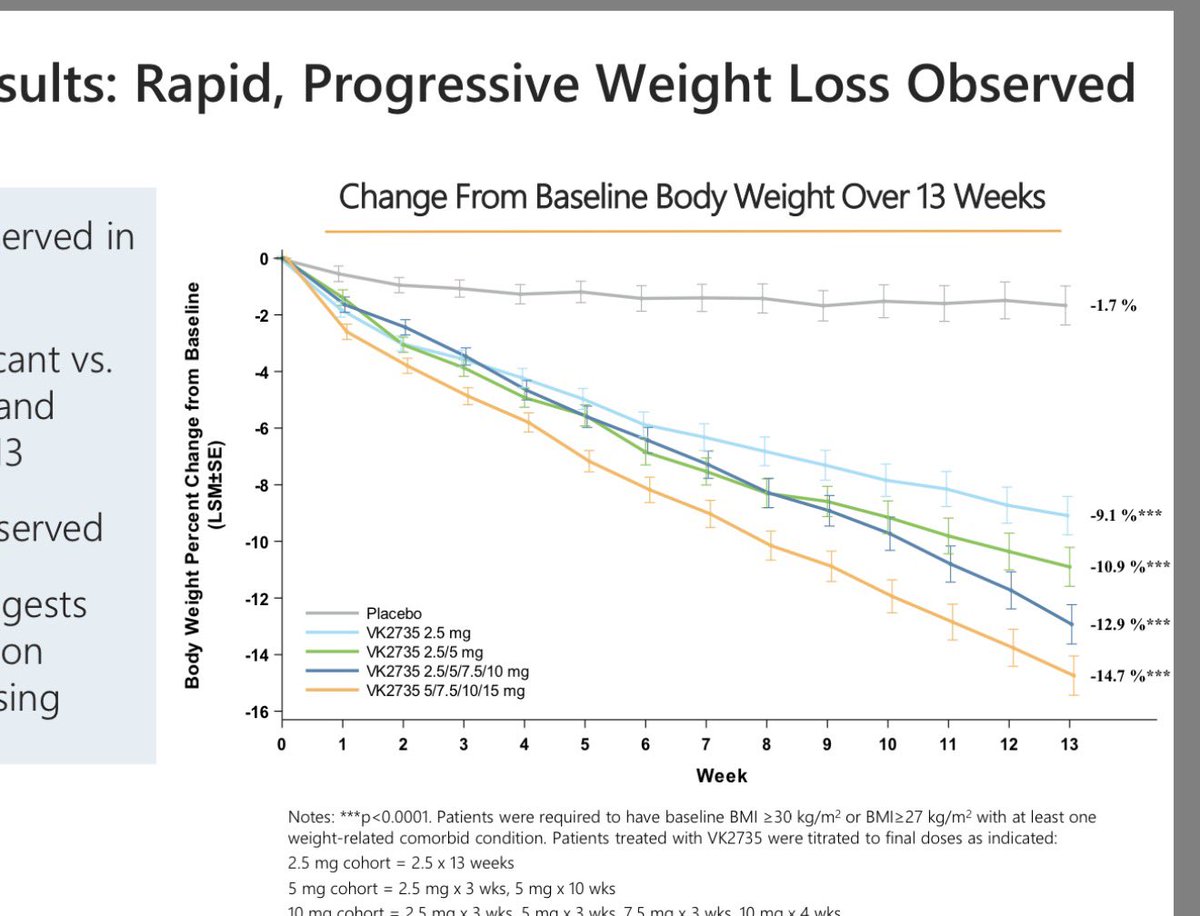
$VKTX phase 3 vanquish is leaking < 5% vomit at 6 months with almost non existent DC , vs Pfizer vesper 3 “ vomit rate c/w GLP1 class “ Which is 20-30%
Met 075 12% wt loss at 28 wks. Vs vk2735 smallest dose of 2.5 mg getting 9% wt loss at 13 wks. And 5 mg 11% at 13 wks
For Circle it’s basically less revenue growth potential as customer acquisition takes a hit, but it’s also higher margins (in the case they do not bypass the law with some loyalty programs or vaults)
The law will have no impact on Circle’s bottom line and operating profit, since revenues were already being spent ~98% on incentives. It could even prove marginally positive, as linked redemptions will occur over a longer period than the yield payments, which stop instantly.
S&P Dow Jones Indices and trade[XYZ] have joined forces to launch the first official S&P 500 perpetual contract, available exclusively on Hyperliquid.
For 69 years, the S&P 500 has been a defining reference point for global finance. Until now, access to that benchmark has been shaped by market hours, intermediaries, and geography. Today, that changes.
The S&P 500 perp is now available 24/7/365, anchored by the official index data required for deep liquidity and institutional confidence at scale.
SPDJI helped define modern indexing. They are stewards of an iconic benchmark, the standard against which portfolios across the globe are measured. We are honored to bring that legacy on-chain.
Trade[XYZ] is bringing the world's most iconic assets towards a future of global, continuous markets — a future powered by Hyperliquid.
As we approach the official release of Morpho’s fixed rate markets protocol it’s becoming clear that it should not be seen as an iteration of the existing Morpho variable rate markets (today known as Markets V1). It is a completely new paradigm that’s unlike anything DeFi has seen before.
Fixed rate markets are an extension of Morpho's offering, not a replacement. Variable rate markets remain a foundational part of DeFi for the few years to come. The two will complement one another.
For that reason, we’re drop the versioning naming we've been using up until now, and the protocols will no longer be named Markets V1 and Markets V2. We’re changing:
Markets V1 → Morpho “Blue” (as it was originally) Markets V2 → Morpho “[TBA]”
Blue introduced permissionless open-term variable rate markets, with externalized risk management. [TBA] will introduce fixed term, fixed rate, intent lending, with externalized risk and rate management. A completely different structure for pricing and matching that will take Morpho from $10B to $100B+.
As a side note: Morpho Vaults retain versioning because Vaults V2 is a direct improvement designed to supersede Vaults V1, exactly what versioning is meant to signal.
It has been an incredibly hard 2 years of building [TBA], but we are very excited to share more information about Morpho fixed-rate markets soon.
Since the beginning of the year the gap has widened too much based on disruption fear and supply shortages.
Valuation shrunk too much and maybe we are seeing some intrasectorial rotation right now. I am long software stocks and I think there is upside to catch in the near-term