Your day switches between #work and #life. Your banking should too.
Modern financial life is not neatly divided into “business hours” and “personal time”.
You land in #Lisbon for a conference.
The flight is a business expense.
Dinner with a client goes on the company account.
The hotel extension for the weekend is personal.
Your SaaS subscription renews in USD.
A client pays your business in EUR or a supported stablecoin.
Later that evening, you split dinner with a friend.
The context changes constantly.
But most financial products still make you manage those two lives in completely separate worlds — different apps, cards, balances and workflows.
At @fasqon, we are building a different model:
Personal and Business. Separate money. One financial experience.
Switch to Business when you need to receive client payments, pay suppliers, manage subscriptions, move money across SEPA, SWIFT or supported stablecoin rails, or handle company expenses.
Switch to Personal for travel, dining, shopping, transfers and everyday spending.
This matters especially for founders, freelancers and independent professionals, because the benefit is not just convenience.
When the right expense is paid from the right financial context from the start, there is less to untangle later — fewer personal purchases mixed into business records, fewer company subscriptions sitting on personal cards, and less manual sorting when it is time to understand where the money went.
One login.
Two clearly separated financial modes.
The right account for the right moment.
#Fasqon #neobank #banking #payments
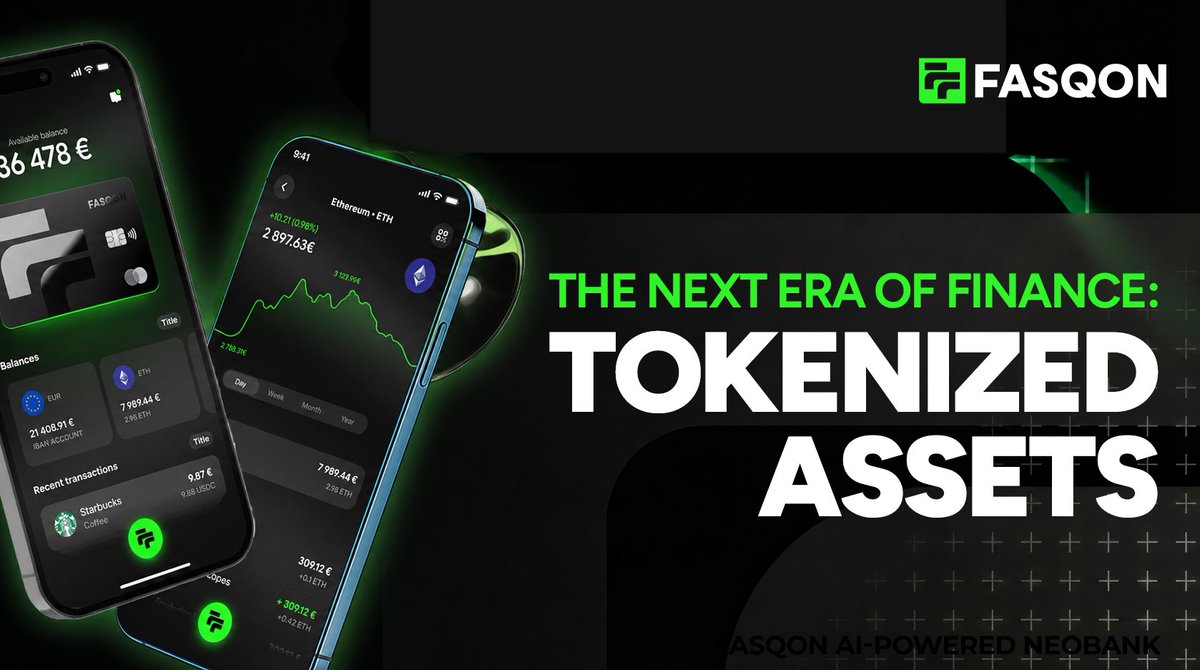
Tomorrow, your business may receive EUR, USDC or tokenised bank money.
You shouldn’t need a different financial platform for each.
That’s the idea behind @fasqon: traditional currencies, digital assets and international payment rails connected in one banking experience.
Read the full story on LinkedIn 👇
https://t.co/pH2u5xwp9Z
#Fasqon #Fintech #BusinessBanking #Stablecoins #DigitalPayments
The world’s biggest banks are putting money on blockchain.
@jpmorgan and @Citi are developing blockchain-based banking infrastructure. Citi estimates bank tokens could support $100–140T in annual transactions by 2030.
Potentially more than stablecoins.
What are bank tokens?
Imagine $100,000 in your business bank account, represented digitally on blockchain.
It remains a claim on the bank, but can move between approved participants 24/7.
It’s traditional bank money using new payment infrastructure.
That’s why we’re building @fasqon: USDT, USDC, EUR, USD and international payment rails connected in one banking experience.
Businesses shouldn’t have to choose between traditional banking and digital dollars.
Full story on LinkedIn 👇
https://t.co/gFBCCEeXdU
@Citi predicts nearly $100 TRILLION could move through stablecoins annually by 2030.
But who’s actually using them?
From international suppliers to global contractors, businesses are finding new ways to move digital dollars across borders, 24/7.
USDT holds ~59% of the stablecoin market. USDC holds ~24%.
But not every financial provider supports both.
Imagine getting paid in USDT, USDC and EUR, then needing to convert everything and pay your suppliers.
That’s the real business challenge.
Built to grow. Structured to last.
Fasqon @fasqon is investing in the legal and regulatory infrastructure behind its next stage of growth.
We are pleased to welcome Meridian Corporate Group as a partner in strengthening that foundation.
Building a financial platform across markets requires sustained investment in corporate structures, licensing and registration processes, compliance capabilities and banking relationships. These decisions shape which customers a business can serve, how money moves and how responsibly it can expand.
We are building a regulated European neobank for people and businesses operating globally, connecting traditional currencies and digital assets across SEPA, SWIFT, cards and on-chain payment rails. Bringing these capabilities into one banking experience requires complex financial and technical architecture, robust AML controls and coordinated compliance across jurisdictions.
Reliable specialist partners are essential to that work. As we approach launch, our partnership with Meridian strengthens the foundations for Fasqon’s international growth and the businesses we are building to serve.
#Fasqon #payments #banking #neobank
Fasqon is getting ready to launch in Europe. 🇪🇺
The first version of Fasqon app is almost here — bringing business and personal finance into one app, with traditional currencies and digital assets working side by side.
For businesses, that means you will be able to receive digital assets and stablecoins, swap them directly in Fasqon, and use the resulting balance for everyday financial operations — from SEPA and SWIFT payments to suppliers and partners, to recurring business subscriptions.
No need to move between a wallet, an exchange and a separate banking platform just to complete one financial workflow.
Businesses will also be able to generate payment links for invoices, giving customers a simple way to pay them, while keeping payments, transaction history and account statements accessible in the same app.
@fasqon Fasqon brings Personal and Business banking into one financial environment, while keeping each account and its financial activity distinct.
Next comes Fasqon AI — turning conversation into a new interface for banking: find transactions, analyse activity and prepare payments for review and approval.
We’re getting ready to launch Fasqon in Europe. More soon.
#Fasqon #neobank #payments
Financial markets are preparing for 24/7. Fasqon is building the rails for that reality.
🇺🇸 Michael Selig, Chairman of the U.S. Commodity Futures Trading Commission (CFTC), has called on financial markets to prepare for mass tokenization, near-instant settlement and real-time collateral movement.
He sees blockchain and tokenized assets as potential foundations of a new financial system, with stablecoins playing an important role in its infrastructure. The CFTC is also adapting its regulatory approach to on-chain finance and markets operating around the clock.
For businesses, this shift goes far beyond tokenized assets.
International settlements, supplier payments, payroll and liquidity management should not be constrained by banking hours, weekends or the limitations of individual payment systems.
This is precisely the financial environment we are building @fasqon Fasqon for.
Our multi-rail architecture brings traditional banking rails — SEPA and SWIFT — together with on-chain stablecoin payments. Businesses can operate across traditional currencies and digital assets within one connected financial environment, choosing the appropriate route for each transaction.
The goal is not to replace traditional banking. It is to connect it with the speed and flexibility of the next generation of financial infrastructure.
As global markets prepare for this transition, we are building the rails to bring these capabilities into everyday business finance.
The future of finance is multi-rail. And it is already being built.
#Fasqon #Fintech #Tokenization #Stablecoins #OnChainFinance
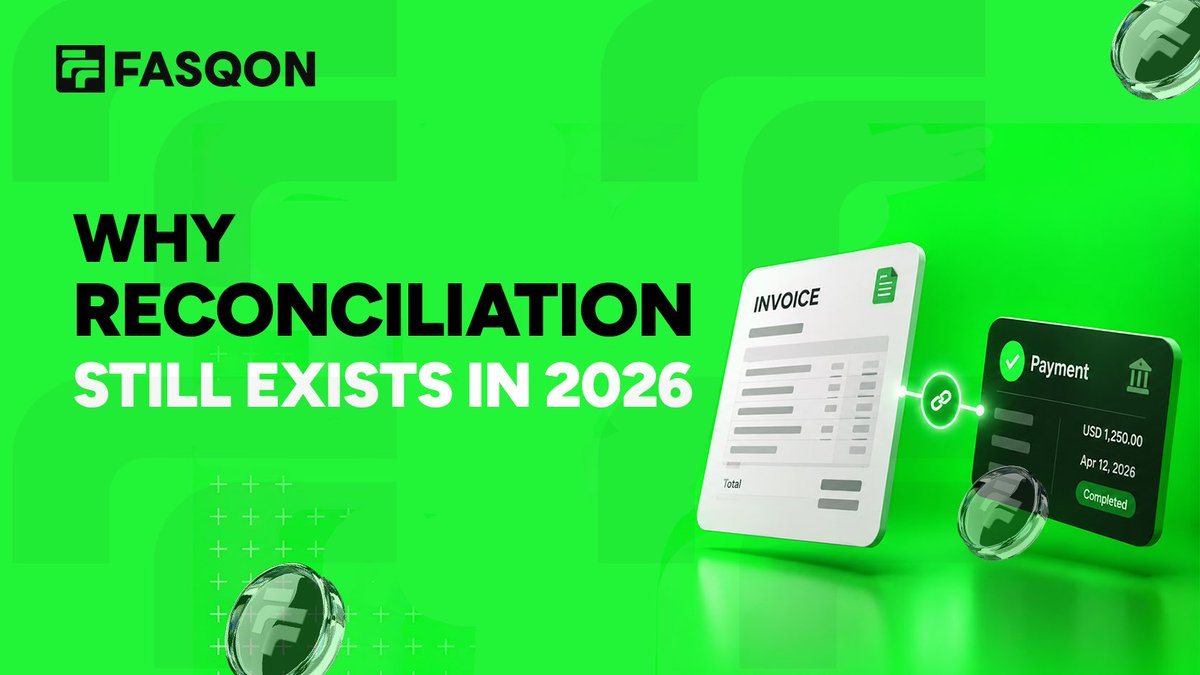
Why is payment reconciliation still so manual in 2026?
A customer receives an invoice and pays it. The money arrives. But finance still has to work out which invoice the payment belongs to.
That happens because the information is usually split across different systems. The invoice sits in accounting software, the transaction appears in the bank account, the payment reference may come separately, and the final status is often still tracked in a spreadsheet.
Add partial payments, fees, FX differences or one transfer covering several invoices, and what should be a simple match becomes manual work.
The issue is not really accounting. It is missing context.
If invoicing and payments are connected, the system already knows who should pay, how much, in which currency, for which invoice and when.
So the normal flow should be:
Invoice issued → payment received → matched → reconciled → accounting updated
And only the unusual cases should need a person to step in.
That is the real shift: not faster manual reconciliation, but exception-based reconciliation.
Finance should spend time on the cases that genuinely need judgement — short payments, missing references, duplicate transfers or several invoices paid together — not on matching every transaction by hand.
This matters because reconciliation is not just admin.
It affects how clearly a company sees what has been paid, what is still outstanding, how much cash is actually available and which receivables need attention.
That is one of the areas we are thinking about deeply at @fasqon
A bank transaction tells you that money moved.
An invoice tells you why.
Those two things should not live as separate stories.
The future of reconciliation is making manual work the exception.
#Fasqon #neobank #payments #banking
Not every payment should move the same way
A business can make seven payments in one day and need five different payment rails to execute them properly.
A salary payment to an employee in Europe may go through SEPA. Cloud infrastructure and advertising spend may be charged to a card. An international supplier may require a USD bank transfer through SWIFT. A contractor or creator may prefer USDC. An urgent euro invoice may make more sense through SEPA Instant.
These are not competing payment methods. They solve different problems.
The right rail depends on who is being paid, where they are, which currency they need, how quickly the money has to arrive, what the transaction costs, and how the recipient can receive it.
That is the product logic behind @fasqon
Instead of forcing every payment through the same route, Fasqon is being designed as one environment where businesses can work across multiple rails.
Imagine a single payout run containing salaries, suppliers, subscriptions, travel expenses and contractor payments.
One recipient gets EUR via SEPA.
Another receives USD through SWIFT.
A SaaS subscription is paid by card.
A contractor receives USDC on-chain.
Different currencies. Different destinations. Different rails. One workflow.
The same logic applies to invoices. A €3,000 invoice from a Portuguese supplier does not necessarily need the same settlement route as a $70,000 invoice from an Asian manufacturer or an urgent payment due on Saturday.
The goal is not to make businesses think more about payment infrastructure.
It is the opposite.
Fasqon brings the rails inside the banking experience, so businesses can choose and eventually intelligently route each payment according to what that transaction actually needs.
Because multi-rail banking should not mean managing more financial tools.
It should mean having more ways to move money without leaving one financial environment
Most financial companies start with a product idea.
Fasqon started with a problem we were already living with: running an international business across banks, currencies, payment rails and digital assets that were never designed to work together.
And we quickly realised we were not alone.
Companies across very different industries are dealing with the same fragmentation — combining banks, payment providers, exchanges and financial tools just to manage everyday operations across markets.
That raised a bigger question for us: was this simply a problem worth solving for ourselves, or was there a serious financial business to build around it?
In the first edition of Building FASQON, our Co-Founder & Executive Director Serhiy Khrun shares where Fasqon started and why we decided to build it.
Read the first part of the @fasqon story ↓
The banking platform we needed didn’t exist - so we built it https://t.co/0THZ5oR0aY
E-Invoicing is not an accounting feature. It is the start of machine-readable finance
For many businesses, an invoice is still basically a PDF with a payment instruction attached.
It gets created in one system, sent by email, recorded somewhere else, paid through a bank, and reconciled later. The information exists — but the workflow is fragmented.
E-invoicing changes something more fundamental than the document format.
It turns the invoice into structured financial data that other systems can understand and act on.
Once an invoice is structured, the financial platform can know what is owed, when it is due, who should pay, which payment belongs to it, and whether the receivable is still outstanding.
The result is a much more connected finance operation:
invoice → payment → reconciliation → liquidity
An invoice is issued. The customer pays. The payment is matched automatically. Accounting receives the same structured data. Cash-flow visibility updates. Overdue receivables become immediately visible.
And this is where e-invoicing becomes much more interesting than compliance.
A confirmed invoice is also a financial asset.
If invoice, payment history and receivable data already sit inside the financial workflow, eligible invoices can potentially move directly into factoring or invoice-financing processes — instead of being exported into another system and underwritten from scratch.
The same structured data matters for AI-native finance operations.
An AI agent cannot do much with a pile of PDFs and disconnected bank transactions. Give it structured invoices, payment status, balances and receivables, and it can start answering useful questions:
Which invoices are overdue?
What cash is expected next week?
Which receivables may be eligible for financing?
What needs attention before payroll?
Regulation may accelerate e-invoicing adoption, but the bigger opportunity is operational:
documents become data → data becomes workflow → workflow becomes finance.
At @fasqon Fasqon, this is how we see the direction of business banking.
Invoicing should not live in one platform, payments in another, reconciliation in a third and working-capital finance somewhere else.
The more these layers understand each other, the less manual financial administration businesses have to do.
The bank no longer just sees money after it moves.
It increasingly understands the financial context before it moves.
#Fasqon #fintech #banking #neobank
Good banking UX should turn five steps into one or two
The problem with modern money is not access. It is the number of steps between having money and actually using it.
A business receives USDC.
Now it needs to pay a supplier in EUR.
Today that can mean moving funds to an exchange, converting them, withdrawing to a bank account, waiting for settlement, checking fees and FX, then finally sending the payment.
Or you receive USD, need EUR for tomorrow’s invoices, and end up moving between two providers just to complete something that should feel simple.
Every extra platform means another login, another balance, another fee, another place to make a mistake.
That is the UX problem we care about at Fasqon.
If the money is already in your account, the next action should be one or two clicks away.
✅Receive a stablecoin → convert what you need → pay in EUR.
✅Hold USD → swap part of it → settle an invoice.
✅Receive EUR → send it through the appropriate bank rail.
✅Need to pay immediately → use the rail that makes sense for that transaction.
The customer should not have to manually build the route between a bank, wallet and exchange every time money changes form.
The infrastructure can be complex. The experience should not be.
That is where banking UX is heading — fewer handoffs, fewer unnecessary conversions, fewer screens between intent and payment.
At @fasqon Fasqon, we are building toward exactly that: different currencies and payment rails working behind one interface, so moving money feels less like operating infrastructure and more like simply getting something done.
#Fasqon #neobank #banking #payments #fintech
A card should not be a dead end for your money
Most crypto cards are built around the same flow:
top up → convert → spend.
It solves the checkout moment, but not everything that happens before or after it.
At @fasqon Fasqon, we are building the card as part of a much broader financial experience.
Behind the Fasqon Card sits an account with your own EU IBAN, supported currencies, stablecoins and payment rails. That means money can do more than simply arrive in a wallet and leave through a card terminal.
✔️Receive EUR through your IBAN.
✔️ Receive USDC or USDT and convert when needed.
✔️ Send money to a friend or pay your landlord.
✔️ Make a transfer to a supplier.
✔️ Pay an international subscription in the currency it requires.
✔️ Then use the same account for everyday spending through Apple Pay, Google Pay or your Fasqon Card.
No moving money through a chain of separate banking apps, exchanges and wallets just to make it usable. And the card itself should fit the way people actually live.
Use a virtual card when you want to start spending digitally. Order a physical card for everyday use, travel and ATM withdrawals while abroad.
Our team is now bringing the final pieces together as we prepare the release of the Fasqon app and Fasqon cards.
Pre-order your Fasqon Card now!
Banking is about to get its own workforce
The next generation of banking will not just give businesses an account, cards and a dashboard.
It will give them specialized AI agents that assist across banking, finance, digital assets and financial intelligence, directly inside the banking environment.
AI agents are moving from experimental interfaces toward a new operating layer for financial services.
At @fasqon Fasqon, we want to take this evolution directly to the business client.
We are building an AI-agentic banking layer where companies can activate specialised agents depending on what their business needs.
✅Banking Agents for balance and transaction queries, IBAN transfers, FX conversion and account configuration.
✅Digital Asset Agents for deposit detection, portfolio valuation, MPC withdrawal workflows and multi-chain routing.
✅Finance Agents for invoice drafting and issuance, invoice financing, payroll execution and trade-finance orchestration.
✅Insight Agents for spending analytics, cash-flow forecasting, anomaly and fraud alerts, compliance summaries and regulatory reporting.
But the bigger innovation is not simply putting several AI assistants inside a banking app. It is orchestration.
A supervising Fasqon agent coordinates specialised agents through shared context and memory, while permissions, approval rules and guardrails determine what each agent can access, prepare or execute.
An invoice can move from document to analysis, approval and payment workflow.
A founder can ask about cash flow instead of searching through dashboards.
A finance team can receive exceptions and anomalies instead of manually looking for them.
This is a fundamentally different relationship with banking software.
At Fasqon, we believe the next step is equally important: bringing specialised financial agents to the businesses using the bank.
From banking software you operate to financial infrastructure that can increasingly understand, assist, coordinate and execute within your rules.
#Fasqon #AiAgents #Ai #AgenticAI #Fintech #BusinessBanking #AIBanking #FutureOfBanking
Banking & Market Insight: Stablecoins Are Becoming Financial Infrastructure
In 2022, Standard Chartered warned about the risks digital assets could pose to the financial system. Today, the bank has become the first Global Systemically Important Bank (G-SIB) to offer institutional clients direct access to USDC minting and redemption through its partnership with Circle.
Four years is a remarkably short time for an institution of this scale to move from caution around crypto to providing regulated stablecoin infrastructure.
And Standard Chartered is not moving in isolation.
The numbers tell the story:
✔️ USDC has grown into a $73.8 billion stablecoin ecosystem.
✔️ Visa processed more than $225 billion in stablecoin settlement volume last year.
✔️ Stripe invested $1.1 billion to acquire stablecoin infrastructure, reinforcing its long-term strategy around programmable payments.
✔️ PayPal’s PYUSD surpassed $1 billion in quarterly payment volume as digital dollars become increasingly integrated into payment flows.
Taken together, these developments point to a structural change in financial infrastructure.
Stablecoins are no longer being positioned simply as an alternative to banking. They are increasingly becoming another settlement rail within banking — supporting cross-border payments, treasury management, liquidity movement, and institutional settlement.
For businesses, that changes the question.
It is no longer whether to operate through traditional banking or digital assets.
It is how to use both efficiently — and how financial infrastructure can select the right rail for the transaction.
At @fasqon Fasqon, that is exactly the environment we are building for.
A business can operate across IBAN accounts, SEPA, SWIFT and supported stablecoin rails within one financial environment, alongside treasury, global payroll, invoice settlement, and cross-border payments.
And where stablecoin settlement offers a faster or more efficient route, the infrastructure can sit underneath the transaction — without forcing the business to manually buy crypto, move funds through an exchange, or convert them again at the receiving end.
The client manages the payment.
The platform manages the rails.
That is where the next phase of business banking becomes interesting: not replacing fiat with crypto, but intelligently orchestrating both.
#Fasqon #neobank #payments #fintech #stablecoins #banking
The fastest cross-border payment rail is not always SWIFT.
In some corridors, the more efficient route may be:
local currency → regulated stablecoin rail → settlement → local currency.
The difference is that the business should not have to manage that process itself.
✅No exchange account.
✅No manual purchase of USDC or USDT.
✅No wallet transfer followed by another conversion at the receiving end.
The client sends and receives traditional currency. The stablecoin can operate underneath as an optional settlement rail when it offers a meaningful advantage in speed, cost or availability.
That is the infrastructure model @fasqon Fasqon is building - a multi-rail environment. A payment may move through SEPA, SWIFT or a supported blockchain settlement rail, depending on the currencies, corridor, counterparty, compliance requirements and execution conditions.
Where stablecoins offer the better route, Fasqon can manage the conversion and settlement logic beneath the customer experience. Where traditional rails are more appropriate, they remain available.
For the business, the workflow stays familiar: send fiat, receive fiat, track the payment, reconcile the transaction.
The complexity sits in the infrastructure not with the client.
The real advantage is therefore not “crypto payments.”
It is intelligent rail orchestration: combining the reach and familiarity of traditional banking with the speed and availability that stablecoin infrastructure can provide in eligible transactions.
Speed matters. But resilience, transparency and compliant fallback options are what make that speed suitable for business finance.
#Fasqon #neobank #payments #banking #fintech
From “Crypto Is Risky” to Building Stablecoin Infrastructure
In 2022, Standard Chartered warned about the risks digital assets could pose to the financial system.
Today, the bank has become the first Global Systemically Important Bank (G-SIB) to offer institutional clients direct access to USDC minting and redemption through its partnership with Circle.
That is more than another product launch.
It reflects how quickly financial infrastructure is evolving.
The numbers tell the story:
🔹 USDC has grown into a $73.8 billion stablecoin ecosystem.
🔹 Visa processed more than $225 billion in stablecoin settlement volume last year.
🔹 Stripe invested $1.1 billion to acquire stablecoin infrastructure, reinforcing its long-term strategy around programmable payments.
🔹 PayPal’s PYUSD surpassed $1 billion in quarterly payment volume as digital dollars become part of everyday commerce.
These are not isolated announcements.
They signal that stablecoins are becoming part of mainstream financial infrastructure—not as a replacement for banks, but as another settlement rail for global payments, treasury management, liquidity, and business operations.
For businesses, this changes the conversation.
The question is no longer whether to use traditional banking or digital assets.
The question is how to operate efficiently across both.
At @fasqon Fasqon, that’s exactly the future we’re building for.
A regulated business banking platform where companies can manage IBAN accounts, SEPA, SWIFT, stablecoins, treasury, global payroll, invoice settlement, and cross-border payments from one operating environment.
Because the future of business banking won’t be defined by choosing between fiat and crypto.
It will be defined by infrastructure that makes both work seamlessly together.
That future is already taking shape.
#Fasqon #Stablecoins #USDC #BusinessBanking #Fintech #DigitalAssets #Payments #Treasury #Web3