On Chandrasekaran, Venu Srinivasan, Noel Tata, and 4 questions every owner on this planet must ask themselves.
Epictetus was born a slave. He spent the rest of his life teaching free men how to live. Think of life, he told them, as a banquet. A dish comes round to you. Take a moderate portion, and pass it on. A dish goes past you. Do not reach after it. Do not chase the server. Above all, do not seize the plate.
On 17 September 2026, at a table laid in 1868 by a family whose name is still on the building, a man who had already announced his departure decided to retain the plate.
This is an old and unfashionable idea, so let me state it plainly. A company is not a stage for personal destiny. It is a plate where someone else set the table. Someone else paid for the grain. You were invited only to eat, then asked to cook, then trusted with the kitchen.
That trust is not ownership. It never was.
That afternoon, the board of Tata Sons voted 4-1 to hand N Chandrasekaran another five years as chairman, weeks after he had told the same board he would not seek another term. Tata Trusts, which hold about two-thirds of Tata Sons, called the resolution a legal nullity. Noel Tata, chairman of the Trusts and a nominee on that board, voted against it and recorded his dissent. The other Trust nominee, Venu Srinivasan, voted the other way. The holding company spoke of continuity and of complying with the Reserve Bank’s listing directive. The majority owner spoke of articles of association, of a decision that had already attained finality, and of a resolution it says was never validly passed.
Call it governance or succession or whatever you like. The country and the entire corporate world will call it what it looks like, and that is :
A professional who rose inside another man’s house, and a nominee seated in it by invitation, are now standing across the table from the owners - and declining to leave the chair.
Aristotle’s warning, running through Book V of the Politics, is that constitutions are undone less often by the enemy at the gate than by faction within the walls. Empires rarely fall because the stranger was too strong. They fall because the trusted man was given more rope than he deserved to be entrusted with.
That is the impression this fortnight has left. Impressions, once they harden, become culture. Culture, once it hardens, becomes the reason the next generation of owners never again trusts a professional - or a fellow trustee - with the keys.
Chandra was always an employee
Chandrasekaran joined Tata Consultancy Services in 1987. He was a junior engineer, a young man given a desk inside a house that was not his. He was good. He was better than the rest. He became CEO of TCS in 2009 and, after the wreckage of the Cyrus Mistry years, Ratan Tata put him in the chair of Tata Sons in 2017 - the first non-Parsi to run the 158-year-old group, and a lifer from outside the family.
That sentence used to be a compliment, but it was also a boundary.
The owners remained the owners. The Trusts remained the Trusts. The name on the building remained TATA. Chandra remained, in law and in morals, an employee - an extraordinarily well-paid one, among the most highly paid professionals in the country - but still an employee.
Tata Sons’ own filings show what that employment paid. In FY26 the chairman’s remuneration was ₹158.66 crore. Over five years, the disclosed Tata Sons pay alone is in the region of ₹670-685 crore. A man who has drawn that kind of money from one house, and invested even a fraction of it with ordinary competence, does not need another term to buy his daily bread, or pay his monthly bills.
So the question is not hunger. The fight cannot be about money. What is left is a question only he can answer.
Whatever larger figures do the rounds in Mumbai’s drawing rooms, the moral arithmetic does not change. He needn’t be a billionaire on paper to have already been paid enough that the next rupee cannot be the reason the house is now fractured. Continuing this fight is not ambition. It is a profound lesson, delivered in public, on how a senior employee should not behave when the owners say the innings is over.
The exit that was offered, and the hole that was cut.
On 12 August 2026 Chandra wrote that he would not offer himself for a further term when the present one ends on 20 February 2027. The Trusts say that decision was freely taken, made public, and then relied upon by employees, lenders, counterparties and the majority shareholder. They say it attained finality. Five weeks later the board reopened the question, and a majority of directors - not the majority owner - voted to keep him in the chair until 2032.
There is a name for the moment when a man is offered a dignified door and chooses instead to enlarge the crack in the wall. It is not courage. It is a failure of gargantuan proportion.
Chandra had, if the August letter is to be believed, the rarest gift Indian corporate life offers a professional: an exit after creating appreciable enterprise value (debatable, given the capital committed to loss-making bets on his watch), with the option of leaving the argument to history rather than to the courts. The combined market capitalisation of Tata companies multiplied several times over during his tenure. That is a life’s work. Absolution, if he wanted it, was available in the ordinary way - finish the term, help find a successor, walk out with the erstwhile crown of TCS’s success still attached to his name.
Instead, the group is split between two statements issued on the same day. Tata Sons says the matter is settled. Tata Trusts says the vote is void. Lawyers are already planning their investment strategies from the enormous fees that will make. The Reserve Bank has filed a caveat so that it is heard before any court rules on the listing. Markets did what markets do when a house fights itself: Tata stocks fell. A war that may now run through the courts has been opened inside a conglomerate that employs more than a million people.
What, precisely, is being saved by this?
Air India, and the moat that will take years to rebuild
Every chairman inherits some of the owner’s bets and places some of his own. Ratan Tata’s late return to Air India was a romance with an infectious wound. Chandra was in the room when that bet was priced, and the turnaround, it now seems, was projected as a walk in the park (albeit on excel sheets). It has been anything but that. Air India’s losses have run into tens of thousands of crores, alongside a difficult stretch at Jaguar Land Rover and heavy capital committed to new bets, including semiconductors. Those are not sins by themselves. Industrial groups are allowed to bleed on purpose if the purpose is a moat.
The problem is the other half of that logic. A moat keeps the enemy out. What has been created, in aviation and in the holding-company fight, looks more like a drawbridge left down while the family fights in courts. Vulnerabilities of this kind do not close in a quarter. They take years. Listing the holding company, if it comes, will not only raise capital. It will change who can sniggle his way in to take over the Tatas in times to come.
The Trusts fear a listing would change the character of a group whose majority owner is a charity. The board has now aligned itself with a path the RBI has forced and the Trusts have resisted. Shapoorji Pallonji, with roughly 18 per cent, wants liquidity and has welcomed a listing. That is a legitimate shareholder interest. It is not the same thing as the chairman appointing himself the interpreter of the group’s soul, core values and aspirations.
A professional is paid to execute. He is not paid to decide, against the majority owner, what the house is for.
Some of the decisions now in jeopardy were taken with Ratan Tata. That is history, and history is allowed to be mixed. What is not allowed is the sequel in which the professional, having broken bread with the owner through the good years and the bad, 'assumes' the role of a referee, ignoring what the owners want. And assuming that it is he and he alone who understands the company best. There is only one legitimate referee here, and right now he (Noel) isn't sitting in the chair.
That is not stewardship. That is a theology of indispensability. Every failed empire has employed the same priest.
The second man in the room
No fight of this kind is won by one chair. It needs a second signature. On 17 September, that signature belonged to Venu Srinivasan.
He is not a Tata. He sits on the Tata Sons board as a nominee of the Trusts and is vice-chairman of the Trusts themselves - Chairman Emeritus of TVS Motor, a Padma Bhushan, a man invited into Bombay House to represent the owners. Late on 16 September, the Sir Dorabji Tata Trust passed a resolution barring him from voting on the listing, on the ground that his public position conflicted with the Trust’s own. He called the restraint illegal and without authority, said he had been nominated by two Trusts and not one, and that his duty as a director ran to Tata Sons. The next day he voted with the majority - on the listing, and on the extension. Noel Tata was left as the lone dissenter.
The article that requires a majority of Trust nominees to affirm a chairman’s appointment was split one-one. On the Trusts’ reading, that makes the resolution void. On the board’s, the split was simply outvoted.
His lawyers will say, and there is serious law behind them, that a director’s duty runs to the company. That is a respectable position. It is not the bargain the owners thought they were making when they sent him into that room. He has taken no commission from Tata Sons since he joined the board, so this was never about money. It is about whose chair he sits in. And if the owners of two-thirds cannot rely on their own nominee, the articles of association are merely stationery.
The irony is on the exchanges. In late March 2026, at his own Sundaram-Clayton, a compliance appointment made on a Friday was undone by Monday, the independent chairman stepped down, and Venu Srinivasan - who had left the chairmanship four years earlier - took the chair back himself with immediate effect. In his own house, the promoter’s will settled the question in seventy-two hours.
In the Tatas’ house, five months later, he cast the vote that allowed a board to set the promoter’s will aside.
One house he corrected in a weekend. The other he helped leave in the hands of a chairman the owners had already released.
Plato’s guardians in the Republic are watchdogs, and Plato's whole argument rests on one condition: The watchdog faces outward. A nominee is given the night watch because someone trusted him. The only question that has ever mattered is which way he is facing while the owners are sleeping.
If Chandrasekaran is the employee who would not leave the chair, Srinivasan is the nominee who would not vote with the owners who seated him. One without the other does not produce a 4-1. Together they produce a question every promoter in the country will now recite.
Are you above the owners?
The question has to be asked in the plain language owners use when the lawyers have become infructuous.
Are you above the owners of the company?
You have concluded, on this one question, that you are right and the owners are wrong. Not because they are foolish - the Trusts include people who have run serious institutions - but because you assumed that you understand the company better than the people who own it. You may even be right. The difficulty is that being right was never the test. Ownership was.
If the answer is yes, say it. At least the honesty would be welcome. If the answer is no, then the 17 September vote is not a rescue. It is a refusal to accept that the plate was never yours.
Ratan Tata chose you. That choice was an act of the owner’s will, not a coronation. The man who picks a steward does not thereby make the steward the owner. When the patriarch is gone, the title does not migrate into the steward’s pocket because the steward has the better slide deck. It stays where the shares stay. Sixty-six per cent is not a joke.
There is a particular vanity that grows in very large rooms. It whispers that the institution would die without you, that the owners are sentimental, that the market “needs continuity,” that listing requires your face on the prospectus. Continuity is a real good. So is legitimacy. A chairman extended by a majority of directors against the recorded opposition of the majority owner does not give the market continuity. He gives it a court case number.
Plato, in 'the Laws', holds that the first and best of all victories is the conquest of self, and that to be conquered by oneself is of all things the most shameful. A third term that has to be voted through over the owner's recorded extent is not a victory over circumstance. It is a man conquered by his own indispensability.
The impression you are leaving
Think for a moment, not as Chairman of Tata Sons, but as a man who will be discussed in other boardrooms for the next twenty years. Every owner in this country is watching. Every professional who eats from a promoter’s plate is watching. Every son and daughter being groomed to inherit a company is watching.
The impression is this: rise high enough, stay long enough, become rich enough, and then the distinction between steward and sovereign starts to look like a matter of who happens to be in th eroom on that day.
That is the worst lesson a senior employee can teach, and it will be used against the next professional who deserves trust. Owners have long memories and short forgiveness. If this battle is lost - and battles against the holder of two-thirds, fought in the open, are usually lost even when they are won in a single meeting - there will not be a quiet consulting practice or a board seat waiting, or a warm table at the clubs where promoters still greet each other by first name.
Many of the men who praised your elevation were owners themselves. They will read this fight the way owners read every fight - by asking whose side the professional took. That answer follows a man into every room he enters afterwards.
The language for this is older than Bombay House. 'Ghar ka bhedi Lanka dhaye'. The insider who knows the doors is the one who can bring the city down. You do not have to destroy the proverbial Lanka. You only have to forget which side of the wall you were hired to stand on.
Shame is not a fashionable word in strategy decks. It is still the right word for the day a house has to explain, in public, why the people who own it and the people who run it no longer agree on who decides.
Spend an evening with that thought, Chandra Sahib - Not with counsel. With a mirror.
And lastly - A note to every other promoter
This is no longer only a Tata story.
If you own a company, stop assuming that loyalty is permanent weather. It is a season. It lasts as long as incentives, health, succession, and vanity remain aligned. The moment the professional becomes the only person who “understands the complexity,” you already have a problem, even if the quarterly numbers are beautiful. The moment your own nominee on a board begins to speak of “fiduciary duty to the company” as a way of setting aside the shareholder who sent him there, you have a second problem, and it is worse.
Do the unfashionable work now.
Name, on a private page and with deep reflection, who your Chandra could be - and who your Venu could be. Not the villains. The indispensable one, and the respected outsider who sits in the owner’s chair as if it were his. The person whose exit would scare the banks. The trustee whose narrative the independent directors have begun to repeat.
Ask four questions while there is still time.
One: If this person announced tomorrow that the company cannot survive a listing, a merger, a succession or a strategy change without him, would the board believe it because it is true, or because he has become the only translator of the truth?
Two: Who actually holds the shares, and have you allowed a culture in which that fact can be treated as a technicality?
Three: When was the last time you ran a real succession process that did not require the incumbent’s blessing - and when did you last test whether your nominee still votes like a nominee?
Four: If the fight went public, whose story would the employees believe - the owner’s, or the man who signs their increments?
Tata is extreme because Tata is vast, charitable at the top, and legendary. Your company is smaller and will burn faster. A promoter who learns this lesson from someone else’s newspaper pays cheap tuition. A promoter who learns it at his own AGM pays dearly.
Identify the person. Narrow the mandate. Separate the brand from the biography. Put the articles of association where a sleepy loyalist can find them at midnight. Do not wait for the week the central bank rejects an exemption and the board discovers it has two versions of reality.
The professional class will call this paranoia. Owners who have lived through one insider war will call it hygiene.
For Noel Tata
You are the most aggrieved party in this room, and the only one who still has to think like an owner after the statements have been issued.
The RBI has closed one door. Listing may now be the price of staying on the right side of the law. If compliance requires the holding company to come to market, then come to market. Do not die on the unlisted hill if the hill has already been occupied by regulation. Get the obligation out of the way.
Then do the harder thing.
Settle this so completely - in the articles, on the board, in the Trusts, in the memory of every director who raised a hand on 17 September - that no hired hand, however decorated, however well paid, however indispensable last year, ever again confuses the chair with the title deed. Not theatrics. Not a press war. A structural answer so plain that the next professional who feels tempted will look at the wreckage and walk back to his desk.
You do not need to match anyone’s temperature. You need to restore a principle older than this group: the owner may be wrong on a factory, wrong on an airline, wrong on a listing timetable. He is still the owner. A Board that can set the owner aside on a question like this is not a reform. It is a precedent. And precedents, unlike profits, compound in the wrong direction.
List Tata Sons if the law now demands it. Then close the door behind the men who opened it without you.
That is not bitterness. That is how houses last a second century.
What the plate required
The Tata group did not owe Chandrasekaran a third term. It did not owe Venu Srinivasan the right to split the owners’ vote and call it conscience. It owed the first man a fair account of his years. New bets were placed, some of them wise, some of them bleeding, Air India among the latter. That account could have been closed with gratitude and a clean handover.
The August letter was the beginning of that ending. The September vote was its contradiction.
The owners will remain the owners. That is the only sentence in this affair that will still be true when the petitions are done and dusted.
The steward was paid - overpaid by any village standard - and trusted with a century and a half of other people’s name. The point of an exit after such a life is not to win one more cycle. It is to leave the plate that fed you unbroken.
If you lose, there will be no alcove deep enough to hide in. If you win on paper, you may still lose the only verdict that lasts in this country - the verdict owners pass on professionals when they are alone.
Put the chair down. Let the house that made you remain a house.
Because if you do not, your name will outlive your record - not as a chairman, not as the man who ran TCS through its finest decade, but as a verb. And in boardrooms from Mumbai to Chennai to London, promoters will lean across the table, lower their voices, and ask one another the only question this affair will leave behind:
Who could do a Chandra on you?
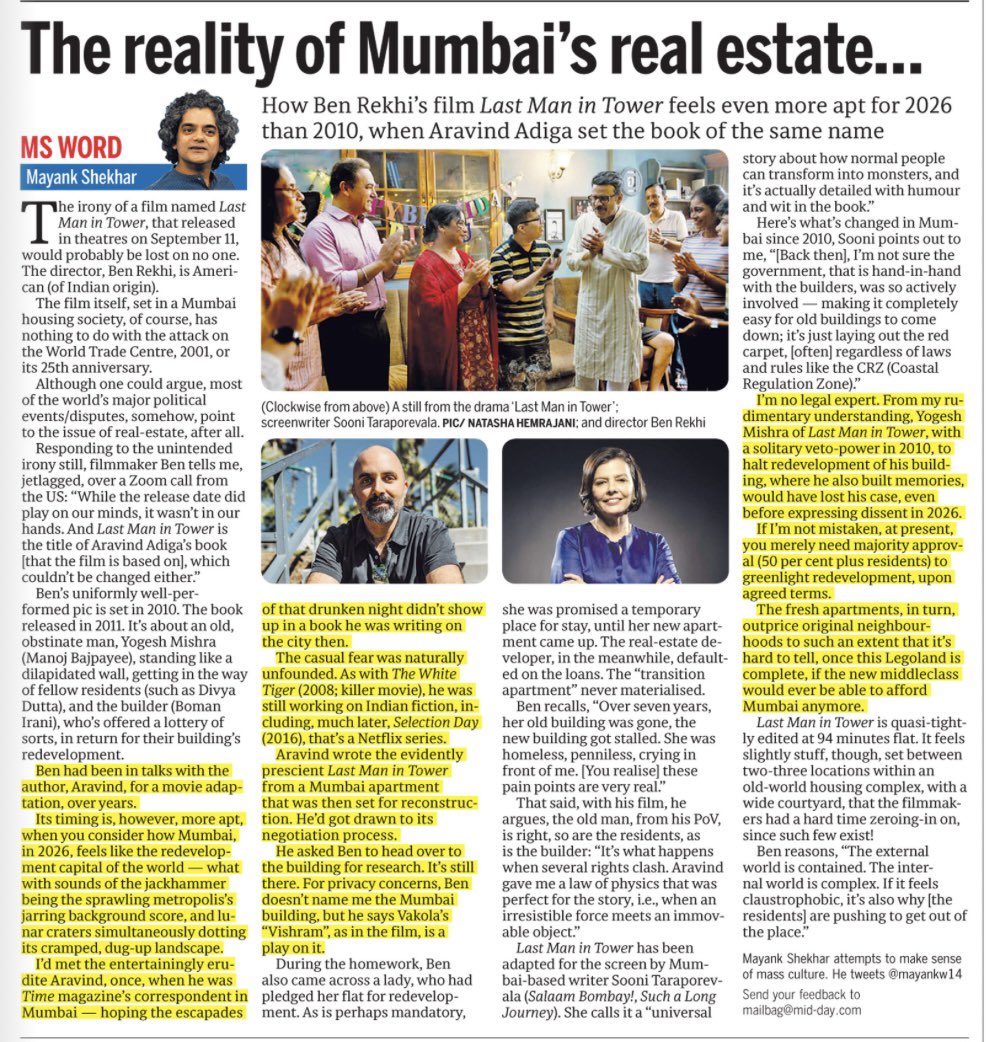
The irony of a film named Last Man in Tower, that released in theatres on Sept. 11, would probably be lost on no one. The director, Ben Rekhi, is American (of Indian origin).
The film itself, set in a Mumbai housing society, ofc, has nothing to do w/ the attack on twin towers of WTC, 2001, or its 25th anniversary.
Although one could argue, most of the world’s major political events/disputes, somehow, point to the issue of real-estate, after all.
Responding to the unintended irony still, filmmaker Ben tells me, “While the release date did play on our minds, it wasn’t in our hands, & Last Man in Tower is the title of Aravind Adiga’s book [the film is based on], which couldn’t be changed either.”
Ben’s uniformly well-performed pic is set in 2010. The book released in 2011.
It’s about an old, obstinate man, Yogesh Mishra (Manoj Bajpayee), standing like a dilapidated wall, getting in the way of fellow residents (such as Divya Dutta), & the builder (Boman Irani), who’s offered a lottery of sorts, in return for their apartment building’s redevelopment.
Ben and been in talks w/ the author, Aravind, over years.
Its timing is, however, more apt, when you consider how Mumbai, 2026, feels like the redevelopment capital of the world — what w/ sounds of jackhammer being the sprawling metropolis’s jarring background score, & lunar craters dotting its cramped, dug-up landscape.
I’d met the entertainingly erudite Aravind, once, when he was Time magazine’s correspondent in Mumbai — hoping the escapades of that drunken night didn’t show up in a book he was writing on the city then.
The casual fear was naturally unfounded. As w/ The White Tiger (2008; also, a killer movie), he was still working on Indian fiction, including, much later, Selection Day (2016), that’s a Netflix series.
Aravind wrote the evidently prescient Last Man in Tower from a Mumbai apartment that was then set for reconstruction. He’d got drawn into its negotiation process.
He asked Ben to head over to the building for research. It’s still there.
For privacy concerns, Ben doesn’t name me the Mumbai building, but he says Vakola’s “Vishram”, as in the film, is a play on it.
What about it?
Full column link in bio.
The poignant drama stars #ManojBajpayee as a stubborn Mumbai resident resisting the redevelopment of his modest housing colony
Read @ReelReptile’s review of #LastManinTower here:
https://t.co/ImGQzoMWUD
Relatable premise. Sincere performances 👀❤️
#LastManInTower, which stars #ManojBajpayee, earns praise for keeping its story grounded while being elevated by its performances.
Rating: 🌟🌟1/2
https://t.co/WkcFYsfQdB
If you can watch one film this week, make it #Lastmanintower It explores our inherent tussle between preserving simpler times, community culture, & embracing the promise of a better tomorrow.Poignant & powerful. Manoj Bajpayee and Divya Dutta are terrific. https://t.co/qvGoyPnuEA
Adapting Aravind Adiga’s acclaimed novel, Ben Rekhi builds a gripping moral battleground where a community chooses redevelopment to compromise its own foundation.
✍️Anuj Kumar
https://t.co/wvr8hgWKTC
IMDb Rating:
Last Man in Tower - 8.9/10
Very limited shows.
Haiwaan - 6/10
Opened with 7000+ shows across India
And as always a small budget movie with limited shows will become cult classic after few years.
Adapting Aravind Adiga’s acclaimed novel, Ben Rekhi builds a gripping moral battleground where a community chooses redevelopment to compromise its own foundation. ✍️Anuj Kumar
https://t.co/wvr8hgWKTC
The film to watch this week is #LastManInTower. Through @BajpayeeManoj’s character, the film makes a scathing comment on the state of Mumbai. Dull, gloomy and with no silver lining. More than a drama, it’s a scary film and a prophecy about Mumbai.
https://t.co/rXGKulZ1XR