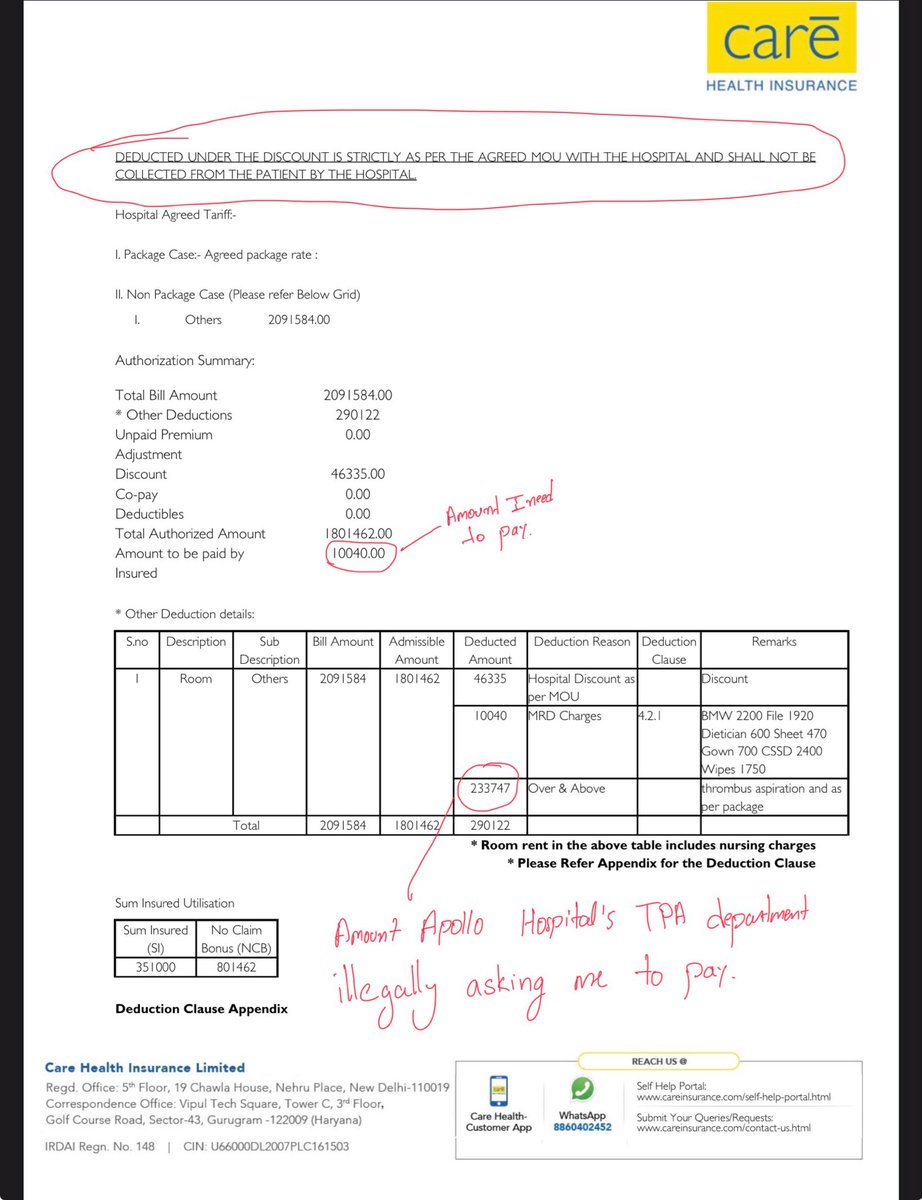
@HospitalsApollo Please help. Your Navi Mumbai TPA team is asking me to pay a deduction that, under the MOU between @CareHealthIndia and @HospitalsApollo, should not be charged to the patient.
You already hold my ₹2 lakh deposit. Please refund the balance. @CareHealthIndia help
@Adani_Elec_Mum 36 hours since clearing dues, still no power. Refrigerator spoiled, daily life disrupted. How long to press a few buttons and reactivate a digital meter?
@Adani_Elec_Mum Power disconnected for non-payment. After clearing dues (Order No. 1040836009) I was told reactivation would take upto 8 hrs. It’s been 18. How long does it take to reactivate a digital meter? Your reps keep saying ‘Escalated’ over 10 times now. Still no action.
First order from @firstcryindia - total nightmare. Delayed delivery, no support, and the delivery guy has been "on his way" for a day. Useless BOTs, can’t even cancel because no refund! I could have easily bought from an offline store.
Industower Q1FY25
Growth is modest. Despite exceeding estimates, main highlight tomorrow will be buyback and write-back, likely from Vodafone Idea. Excluding this, numbers fall short of expectations.
#nifty50#Nifty#Q1FY2025#Q1#StockMarket#INDUSTOWER#Industowers
/🧵/
Tower additions look good. Additionally, Indus has approved a buyback of ₹2,640 cr. It will buy back 5.67 crore shares, 2.1% stake at ₹465/share, with Bharti not participating in the share buyback.
The results look somewhat mixed. I think the poor financial performance is somewhat priced in because we got the gist of this at the time of BPCL’s results.
View on HPCL - Q1FY25 Financially, the results look quite poor. The significant drop in net profit is primarily due to suppressed marketing margins on some petroleum products and reduced refining margins.
#nifty50#Nifty#Q1FY2025#Q1#StockMarket#HPCL#HINDPETRO
/Thread 🧵
In summary, the poor financial performance is mainly due to lower refining and marketing margins. Despite these challenges, the company saw some operational growth and achieved several record highs in throughput and sales volumes.
NIM at 6.6% down from 7.1%. The management plans to achieve a 7% margin level in the medium term by augmenting income as compared to the cost of funds. Concerns include lower than expected NIMs, an elevated cost-to-income ratio (up 1%), and stagnation in branch expansion.
View on M&MFin - Q1 FY25
The results look good to me. Both total income and NPAT growth are impressive, driven by top line growth, controlled OPEX, reduced write-offs, and less provisioning.
#nifty50#Nifty#Q1FY2025#Q1#StockMarket#mahindra_and_mahindra_finance
/Thread 🧵
The CAR is low but above the required level, and the management does not expect a need to raise further capital in FY25. This is not great but acceptable.
The aspirational target of achieving a pre-tax ROA of 2.2% for FY25 is aspirational again, with the current figure at 1.8%.
@SakatasHomma I believe it is currently testing a support and if it can sustain above. It has the potential to consolidate above it. Opportunity for a put writer. What are your thoughts?