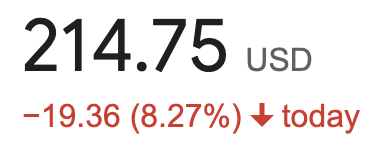
What a day for $AMD shareholders.
This is a massive deal on both sides:
- OpenAI commits to purchasing 6 gigawatts of AMD chips.
- OpenAI will have the right to purchase up to 160 million shares of AMD—roughly 10 percent of the company—at one cent per share, provided it meets certain deployment milestones and AMD’s stock value rises accordingly.
This deal is projected to generate tens of billions of dollars in revenue for AMD over the next five years, as each gigawatt of deployment is expected to cost several tens of billions.
This is great for AMD. They become a key supplier for one of the leading AI companies, which will help attract more high-end customers. The deal structure, which ties compute to performance-based equity, allows both parties to benefit. If AMD delivers the hardware and OpenAI deploys at a large scale, both sides see upside. If either underperforms, we see no equity dilution. A well-structured deal for AMD, combining safety with upside on execution.
I will continue to hold...$250 will be next!
I opened a small position in Salesforce $CRM
Salesforce is a beast of a company — highly profitable, still delivering double-digit growth, and trading in rare tech value territory (~20x forward P/E) where strong earnings, expanding margins, aggressive share buybacks, and accelerating AI adoption aren’t fully priced in.
My largest position is in $AMZN, and I recently added some more shares.
Amazon has not performed well this year, but it's an excellent buy with long-term potential.
Amazon will continue to grow through AWS, lead in robotics, strengthen Prime, and expand its robust logistics network.
The post-earnings selloff in Amazon $AMZN is overdone.
This is a company that should be a staple in every investor’s portfolio. A must-own. Its multiple diversified businesses will continue to thrive over the long term.
I see Amazon compounding at a 15–20% annual growth rate for years to come.
On Friday, I officially sold the vast majority of my Tesla $TSLA shares.
The business has been struggling for a while now, and I’ve been debating this decision for the past month. This week’s earnings report was the final nail in the coffin.
Tesla has been reporting bad quarter after bad quarter. This one was no different.
Here’s a quick summary of the key financials for context:
- Automotive revenue: -16%
- Energy generation & storage revenue: -7%
- Services & other revenue: +17%
- Total revenue: -12%
- Gross profit: -15%
- Income from operations: -42%
- Adjusted EBITDA: -7%
- Net income: -16%
- Operating cash flow: -30%
- Free cash flow: -89%
Some added context behind those numbers:
On the revenue side, the company saw a decline due to:
- Fewer vehicle deliveries
- Lower regulatory credit revenue
- Reduced average selling price (ASP) of vehicles.
- Lower Energy Generation and Storage revenue
- The only real bright spot was some growth in Services and Other.
Profitability was just as bad — operating income dropped 42% YoY. That was driven by:
- Lower regulatory credits
- Higher operating expenses (mostly from AI and R&D)
- Lower deliveries
- Increased stock-based compensation
- They did benefit a bit from reduced restructuring charges, slightly lower vehicle costs, and improved gross profit from energy.
Vehicle sales are declining, and so is the average selling price. The car business is a mess.
Additionally, as you could imagine based on the numbers, their market share is shrinking in key regions (see attached chart).
In terms of the earnings call… Elon sounded completely disinterested and unenthusiastic. Honestly one of the worst I’ve heard from him — just going through the motions.
In terms of FSD and Optimus — I’m happy to get behind it in theory. But right now, I’m not going to put my money on it. Even if they execute (key word if), it'll take years to show up in the numbers. Meanwhile, the current valuation already seems to price in success. You’re basically paying today for Tesla to dominate several highly competitive, unproven markets — just to maybe justify the stock price.
It’s a company I want to own, but as of right now, I can’t justify it as a strong investment.
The “Google’s search business is dying” narrative has been an overhang on the stock for some time now.
Google, $GOOG, reported their quarterly earnings yesterday, and once again, the data didn’t back this up.
Google Search revenue grew year over year by DOUBLE-DIGIT percent — and even better, it accelerated growth from the most recent quarter.
Google Search is growing at an accelerated pace.