$ANT
$VCX looks significantly undervalued to me.
Considering the current valuation of Anthropic, one of the fund’s key portfolio holdings, I believe VCX’s current share price does not fully reflect the underlying value of its assets.
As Anthropic’s valuation continues to rise, that value should eventually translate into a higher NAV for VCX.
The market may not be pricing in this potential yet.
For me, the current discount presents an interesting opportunity. 🚀
Just my investment thesis, not financial advice.
$ANT
Anthropic is set to hold about $210B in cash after today’s IPO.
They’ve guided to $63B of spend in 2027 (likely to be revised higher) and $447B cumulatively by 2030. There’s no fixed window for future share issuance.
If it trades like SpaceX—brief spike then fade—raising another $70-80B on the strength to add more data centers looks sensible. Compute remains the real bottleneck.
Don’t chase the pop. Near-term dilution is the more probable outcome.
@zerohedge ZeroHedge is back with “AI bubble popped.” Nvidia drops 25%, PE down to 22. Comparing this to 1881 and 2000 is easy. Generating record earnings isn’t. Data center spending still accelerating into 2027. Correction, not collapse. Wrong again.
@WallStreetMav These numbers are absurd. A Senate candidate beating every presidential nominee and governor in Texas history is a massive anomaly. County data needs to explain it.
$MU and $AMD. Same market cap. Pure insanity.
$MU is about to print ~$203B while $AMD does ~$25B. That’s 700% more earnings for the same price.
Cut $MU’s profits in half for 5 years and it still crushes $AMD by $265B.
The market is completely asleep. Agentic AI + LTAs make this gap structural. This won’t last.
#MU #AMD #Stocks #Investing #AI
@PeterSchiff Starting the clock right after the dot-com crash is a nice trick. Most other windows and stocks still beat gold. Keep moving the dates Peter.
@StockSavvyShay The guy turned almost half of them into millionaires and that 1% is still whining for him to go. They’re either complete idiots or never bought any shares. Same shit either way.
@TTHUEONE@damnang2 Nice analogy, but incomplete. Classic DRAM is commodity-like, yet HBM and high-end server memory now resemble TSMC: customer-specific, long-term contracts, capacity allocation. Buyers still cut purchases in downcycles. “Must-buy” is short-term, not absolute.
Anthropic’s valuation depends on the number you use. The filed $70–78 range implies roughly $0.9–1.0 trillion; banks are reportedly pushing toward $1.5 trillion.
On sales it looks reasonable. TTM revenue is $35.3B, so the filed range is only 26–29x and even $1.5T is 42.5x. Q3 revenue was $17B, more than 12x year-ago. Palantir is ~56x, Nvidia ~13.5x. By that measure it doesn’t look stretched.
Profitability is the catch. Most of the $104B nine-month GAAP loss is non-cash convertible mark-to-market. Adjusted net income is ~$4B (370x at $1.5T, ~118x annualizing last quarter). There’s also $900B+ in committed compute capacity that only works if growth stays extreme.
SpaceX is the cautionary tale: it ran up, then fell hard, and is now only slightly above its IPO price despite strong growth. The bet here is simply that Anthropic’s growth continues for several more years. If you believe that, the multiple can work. If not, waiting out the early volatility is a reasonable choice. #AnthropicIPO #AI #Valuation #TechStocks
Inflation came in hotter than expected yesterday and the market felt it — S&P off 0.4%, Nasdaq 0.6%, with the 10-year yield pushing up to 5%. Nvidia took another 5.5% hit in our core book on the Jensen Huang investigation headlines and is now down roughly 10% over two sessions.
Pre-market this morning the AI complex is finding a bid again. S&P futures are up about 0.9%, Nasdaq 100 futures nearly 2%, and the VIX is down around 6%. Treasury market is shut for Veterans Day. Brent is firmer, up 1.4% near $93.
#NVDA #QQQ #NDX
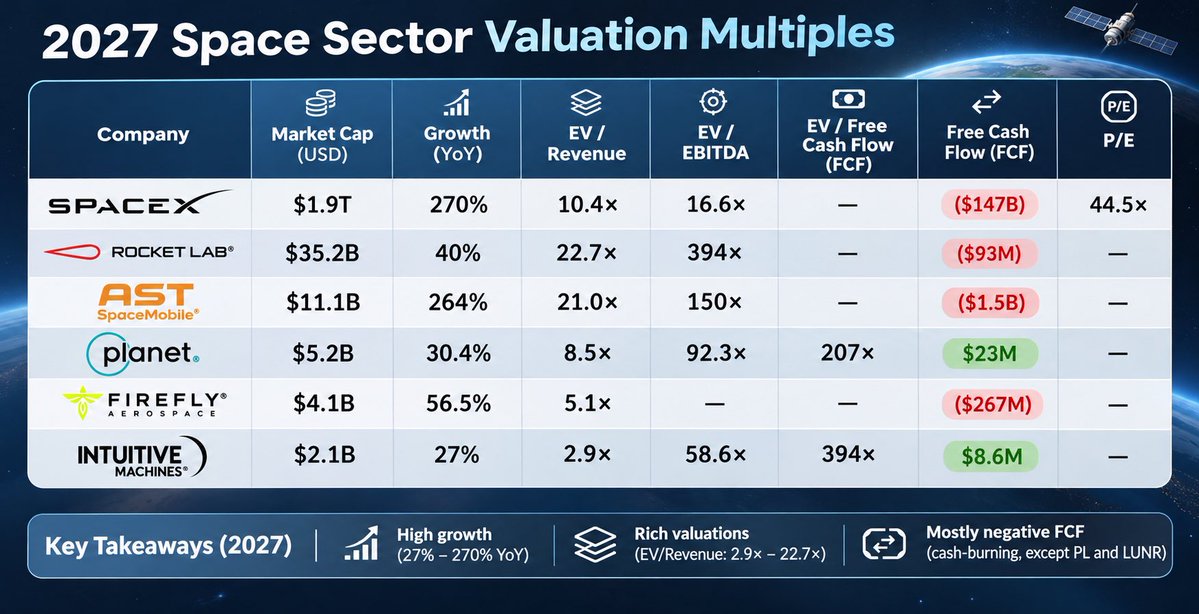
When analyzing unprofitable growth companies, we focus on EV/Revenue, cash reserves, quarterly cash burn, and cash runway. These metrics tell us how long a company can survive before needing additional financing or taking on debt.
Most space companies have negative FCF. So we’re betting on industry growth, execution, and management’s ability to deliver on its promises. In other words, we’re trusting management to turn the vision into reality.
With no positive FCF, these companies are highly sensitive to interest rates and market uncertainty, resulting in extremely high betas.
Look at this year’s charts for $RKLB, $ASTS, and $PL.
The space investment thesis for most of these companies depends on reaching positive FCF by 2029–2030 and executing successfully along the way.
Huge upside, but equally high risk and volatility.
$SPCX $RKLB $ASTS $PL $FLY $LUNR
Not exactly the inflation report markets were hoping for.
Core CPI rose 0.3% MoM, above the 0.2% estimate. Headline CPI came in at 0.4%, also above the 0.3% forecast.
Energy prices jumped 0.7%, gasoline rose 1.0%, and food prices increased 0.5%.
The Fed may not have as much room to cut rates as investors hope. The inflation fight clearly isn’t over yet.
#CPI #Inflation #Fed #Markets
Quantum stocks are back in the spotlight. $IONQ reported $174M in Q3 revenue, up from $40M a year ago, and raised its full-year outlook. The stock jumped 23%, with $RGTI and $QBTS following.
Yet all three are still 57–77% below their October highs.
The excitement is clearly still there, but so is the uncertainty.
Quantum computing could transform drug discovery, materials science and complex financial calculations. The technology is real, and companies like Google are making progress.
But there’s a long way between a promising breakthrough and a commercially useful machine. Qubit stability, error correction and scaling remain major challenges.
I think investors sometimes underestimate how long that journey could take.
Here’s the uncomfortable part: valuations are already pricing in a lot of future success.
$RGTI and $QBTS trade at over 300x trailing revenue. Even $IONQ, despite its stronger growth, is still losing money. Add dilution to the picture, and the risks become hard to ignore.
My view? Quantum is worth watching, but this is still a high-risk, long-term bet. Great technology doesn’t automatically make a great investment at any price.
@StockSavvyShay Everyone’s getting carried away with the AI hype. But at some point, these companies actually have to live up to those crazy valuations.
@StockSavvyShay This is Jevons Paradox in AI: cheaper intelligence creates more demand and unlocks new opportunities. The biggest winners will be those turning it into scalable products and services.