$CCDS.V Techinals on behalf of @CarrierCDS
Volume continues to perk up on a long & getting tighter pennant as timeline to potential PO's for their $95M ARR LOI validation ticks
As ive said before its been 12 weeks since Carrier signed the 25MW LOI with a single AI computing customer which could generate ~CAD $95M in Annual Recurring Revenue at full scale for Carrier.
While non-binding LOI's are rarely priced in by the market timeline to binding PO's could be imminent & would be a material validator to the deal.
"As Purchase Orders are executed for specific deployments in connection with the LOI, the Company will issue a more comprehensive news release disclosing further details of the proposed transaction."
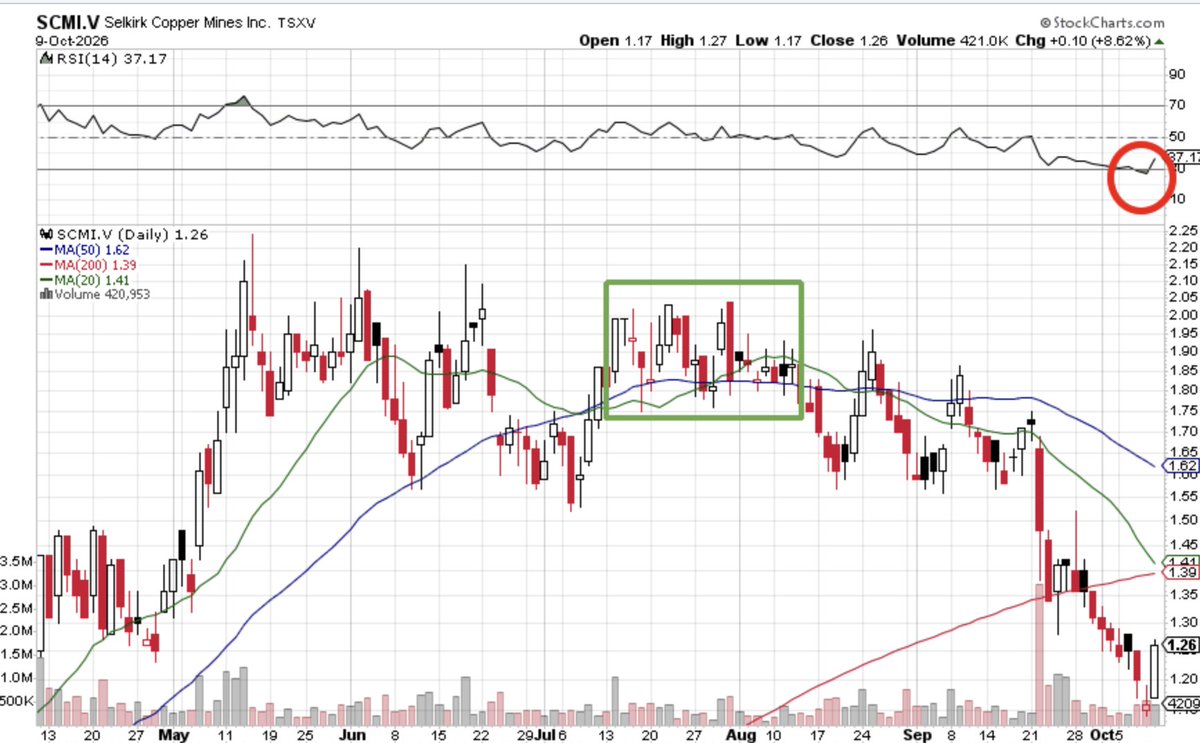
$SCMI $SCMi.V
I am noticing that an RSI trough under 30 (red circle) is often a technical sign of capitulation.
Watching this closely. When it's properly valued it will be rocket back to a double.
I looked at Cambria last Saturday on my live podcast. I realized it was too cheap to ignore. All you need to do is execute, and you will be printing money. I like your approach with adding Red Mountain.
Guys, Cambria is coming on the Feneck Commodity Report in December. You know what that means. You might as well buy now to front-run it. 😂
Strong close!
Make sure when youre a few drinks in at Thanksgiving youre telling all your relatives about the commodities macro & which of our stocks to buy
No action Tuesday = you failed your mission
Happy Thanksgiving. LOTS to be thankful for.
Enjoy the long weekend all 🍻
Connecting the dots on $PRCG 👀 DrJim & geologist/fund manager Tom Woolrych discussing Arikepay’s 3D model. Historical 81m @ 3.17 g/t Au within 420m @ 0.91 g/t gives that deeper-potential discussion context. How far does it extend? That’s the drill question. Long.
For those that don't know who Tom is .. he runs a fund .. a crazy good one at that ..look him up !
Bought a little $SKP.V this week
204m mcap
No warrants
90m cash, means EV = 114m
Predominant RC drilling in Nevada.
4.5million Oz deposit already
They could do a 100000 meter program for next 12 -18 months and still have like 60million in bank
When Fronteer sold to Nemont in peak of 2011 last 4 holes drilled in the property has results like 17m of 6g/t Au
Terrible shareholder communication with little focus on larger TAM or a wider moat from previous management.
Underlying business is a decent foundation to build off of but new CEO is now in a show me what you got state rather than blind faith for a new direction.
M&A from cash would be a direction that would be interesting if well execute. I remain with only a starter
$CCDS.V Techinals on behalf of @CarrierCDS
Volume continues to perk up on a long & getting tighter pennant as timeline to potential PO's for their $95M ARR LOI validation ticks
As ive said before its been 12 weeks since Carrier signed the 25MW LOI with a single AI computing customer which could generate ~CAD $95M in Annual Recurring Revenue at full scale for Carrier.
While non-binding LOI's are rarely priced in by the market timeline to binding PO's could be imminent & would be a material validator to the deal.
"As Purchase Orders are executed for specific deployments in connection with the LOI, the Company will issue a more comprehensive news release disclosing further details of the proposed transaction."
$CCDS.V Keith Schaefer Substack on behalf of @CarrierCDS
"The Little Data Center that MIGHT" by @OilandGasInvest (He owns shares)
Summary take: Keith Schaefer's latest on Carrier Connect Data Solutions is worth a read as CEO Mark Binns answered seven direct questions, and the numbers stand out.
• CCDS has about 4.2 MW of open, AI-ready capacity at Rochester and Perth that needs no upgrades.
• Management estimates filling it could add C$13M to C$15M a year in revenue, 3x to 4x the current run-rate. New AI customers pay US$250K per MW per month, about 2.5x legacy rates.
• An established global operator has signed an LOI for up to 25 MW, worth about C$100M a year at AI pricing, and the total sales funnel is over 150 MW.
• CCDS buys operating data centers at about C$3M per MW, while new builds cost US$11M to US$18M per MW.
• With net cash and a tight share structure, the next two quarterly reports could be key catalysts.
Full article:
https://t.co/49RGhtAWWM
@JosefGether@RonStoeferle Good, now once you get it, burn it! No book can teach you this game, only real world pain (Joking not joking)
Its a great book, the real task is implementing the value learned from it
28 acquisition deals in the works, about 98 MW combined, with two or three targeted to close by year end. That's CEO Mark Binns putting real numbers on the $CCDS.v roll-up in the Oct 1 replay, against a 7.7 MW portfolio today. $CCDSF
https://t.co/6HqDo2cdPf