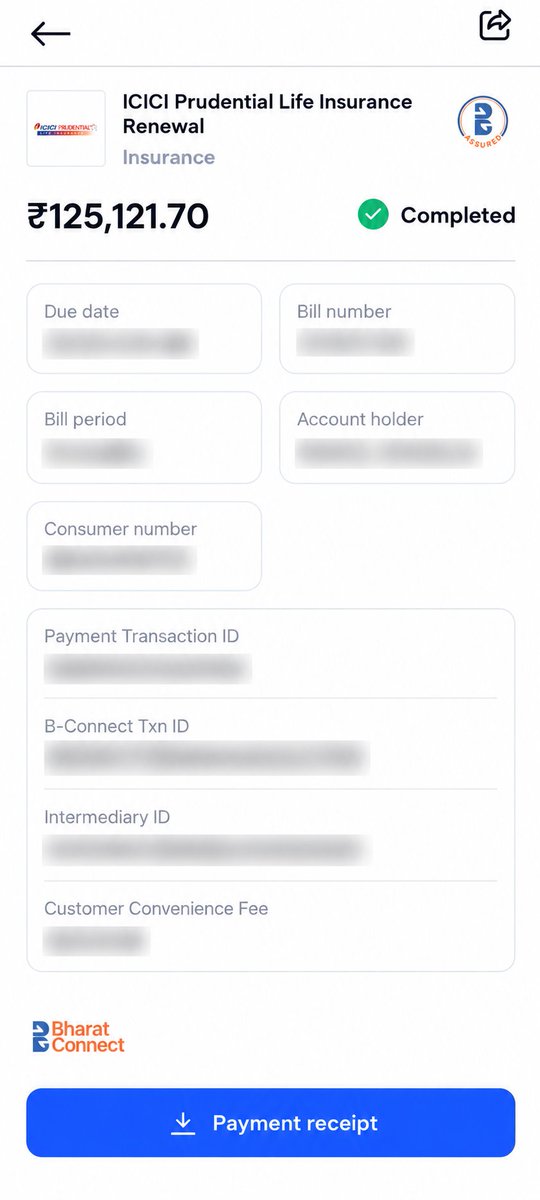
Yesterday I paid more than 1 lac rs for insurance and realized there is not much info around on internet for how to pay insurance via credit card to maximize.
In normal I feel there are only two ways-
1. Pay directly via credit card.
2. Buy gift vouchers for wallets amazon pay/phonepe etc.
If you want to know the way to pay bills of more than 1 lacs rs via wallet DM me and follow me.
Although 2nd option is better as it fetches better rewards.
But one can not buy these gift cards for a big value as there are restrictions everywhere on limit.
I am soon planning to make a post on how to collect these wallets gift voucher from platforms with maximum rewards.
Anyway if you want to pay directly then following credit cards are better because they offer more reward rate than 2%. Almost all websites charge atleast 1.5% convenience fees+ gst for using credit cards.
So here's my take.
🧵 Credit Cards Giving >2% Effective Rewards on Insurance Payments in India — 2026
The important part isn't just the headline reward rate — insurance-specific monthly/statement-cycle caps can drastically change the actual return.
1 — HDFC INFINIA / INFINIA METAL 💎
🔹 5 Reward Points / ₹150 retail spend
🔹 1 RP = ₹1 for flights/hotels
🔹 Effective value: ~3.33%
🔹 Insurance RP cap: 10,000 RP/month
➡️ Maximum insurance spend earning points before the cap:
₹3,00,000/month
So:
₹50K insurance → ~₹1,667 value
₹1L → ~₹3,333
₹2L → ~₹6,667
₹3L → ~₹10,000
---
2 — HDFC DINERS BLACK METAL 💎
🔹 5 RP / ₹150
🔹 1 RP = ₹1 for flights/hotels
🔹 Effective value: ~3.33%
🔹 Insurance RP cap: 5,000 RP/month
➡️ Maximum insurance spend earning points:
₹1,50,000/month
₹50K → ~₹1,667
₹1L → ~₹3,333
₹1.5L → ~₹5,000
---
3 — ICICI EMERALDE PRIVATE METAL 💎
🔹 6 RP / ₹200 retail spend
🔹 Maximum value of RP: ₹1 each for eligible redemptions
🔹 Effective value: ~3%
🔹 Insurance cap: 5,000 RP/statement cycle
➡️ Maximum insurance spend earning points:
~₹1,66,667/statement cycle
₹50K → ~₹1,500
₹1L → ~₹3,000
₹1.67L → ~₹5,000
After the 5,000-RP insurance cap, additional insurance spending doesn't earn those RPs.
---
4— ICICI TIMES BLACK ⚫
This one is interesting but does NOT qualify for my >2% shortlist.
🔹 Reward rate: 2% on eligible domestic transactions
🔹 Insurance is included
🔹 5,000-RP statement-cycle cap
So it's exactly 2%, not more than 2%.
I'm therefore keeping it outside the main >2% list rather than calling it a >2% card.
---
5— SBI PHONEPE SELECT BLACK 📱
This card is often misunderstood because of its headline reward rate.
From 1 July 2026:
🔹 Insurance through PhonePe: accelerated rewards
🔹 10 RP/₹100
🔹 But insurance rewards are capped at only 500 RP/month
➡️ Accelerated insurance rewards effectively apply only up to:
₹5,000/month
Insurance outside PhonePe earns only base rewards and has separate restrictions.
So I wouldn't consider this a genuine high-reward solution for large insurance premiums despite the headline 10 RP/₹100.
---
WHAT ABOUT OTHER HDFC CARDS?
HDFC's current rule is particularly interesting:
🔹 Infinia / Infinia Metal → 10,000 RP/month insurance cap
🔹 Diners Black / Diners Black Metal / Biz Black Metal → 5,000 RP/month
🔹 Most other HDFC cards → 2,000 RP/month
🔹 Marriott Bonvoy HDFC → NO restrictions
IMPORTANT ⚠️
Don't compare insurance cards purely on the advertised reward percentage.
Before paying a large premium, check:
✅ Is insurance eligible?
✅ What is the insurance-specific RP cap?
✅ Is the cap monthly or per statement cycle?
✅ How much insurance spending reaches the cap?
✅ What's the actual ₹ value of 1 RP?
✅ Are there redemption restrictions?
✅ Is the insurer/payment gateway charging a convenience fee?
A 10% headline reward with a ₹5K monthly insurance cap can be far less useful for a ₹1L premium than a 3.33% card with a ₹3L insurance-reward ceiling.
#CreditCards #CreditCardIndia #Insurance #PersonalFinance #HDFC #ICICI #SBI
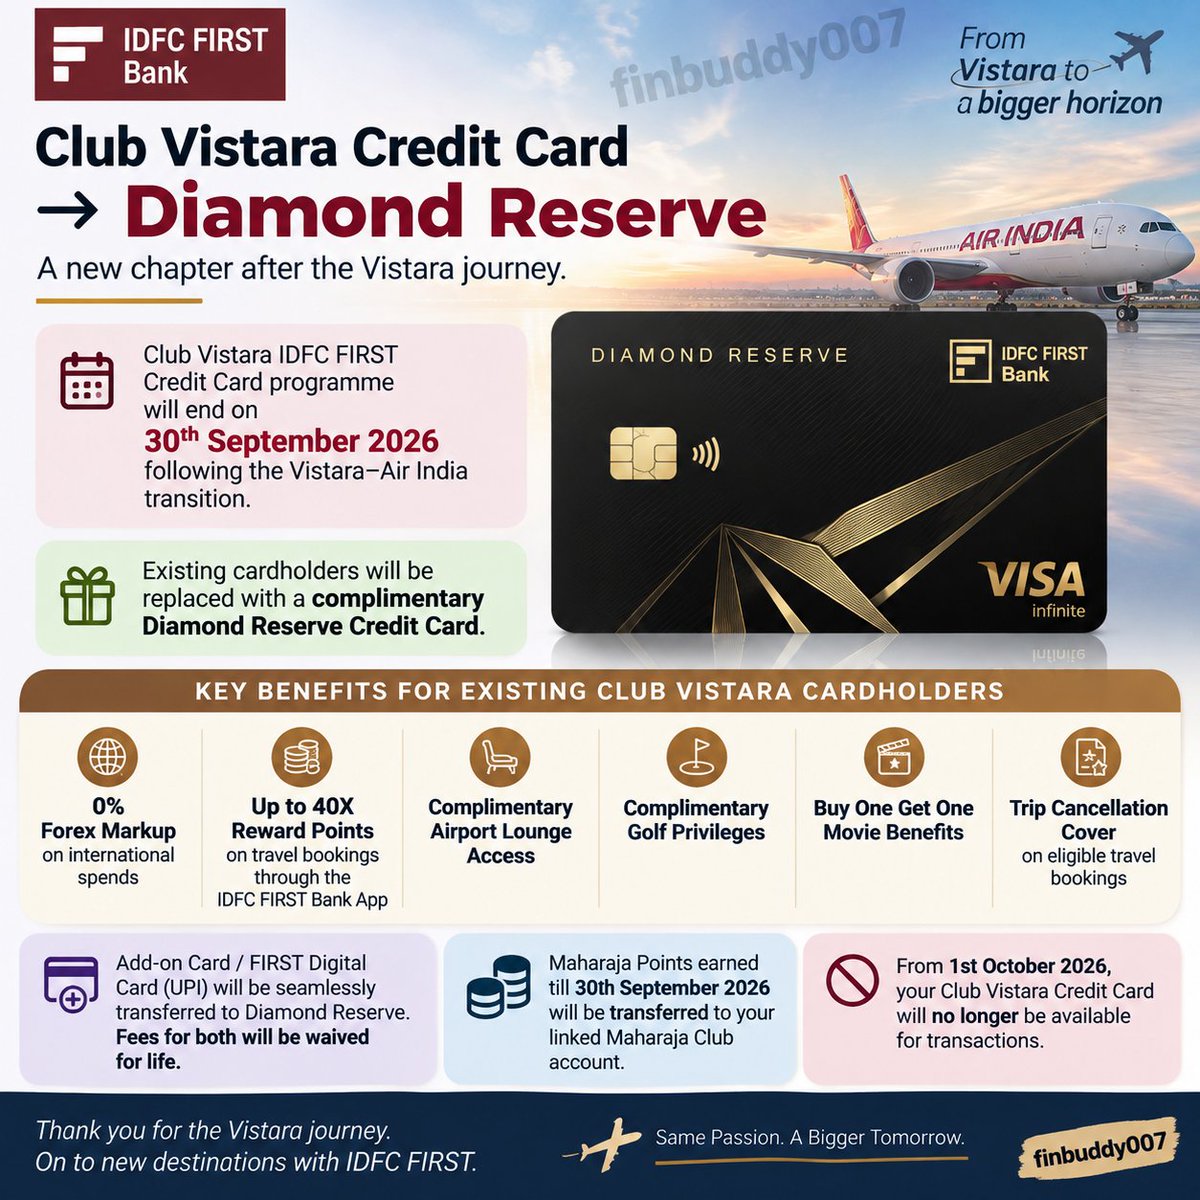
🚨 IDFC FIRST Club Vistara Credit Card → Diamond Reserve
Received this communication from IDFC FIRST Bank today.
The Club Vistara IDFC FIRST Credit Card programme ends on 30 Sept 2026 following the Vistara–Air India transition.
Existing cardholders are being offered a complimentary Diamond Reserve Credit Card.
Key points 👇
• 💳 Lifetime fee waiver
• 💱 0% Forex Markup
• ✈️ Airport lounge access
• ⛳ Golf privileges
• 🎬 Movie benefits
• ⭐ Up to 40X reward points on eligible travel bookings through the IDFC FIRST Bank App
• Add-on Card / FIRST Digital Card (UPI) will transfer to Diamond Reserve, with fees waived for life
• Maharaja Points earned till 30 Sept 2026 will be transferred to the linked Maharaja Club account
⚠️ Existing Club Vistara card will stop being available for transactions from 1 Oct 2026.
The interesting part: Diamond Reserve normally carries a ₹3,000 annual fee, but existing Club Vistara cardholders are getting it lifetime free.
#IDFCFIRSTBank #ClubVistara #DiamondReserve #CreditCards #AirIndia #MaharajaClub
I was just going through several posts related to recent UPI MDR changes and realized following things-
A. Many so called fin-fluencers with thousands of followers don't even have basic ideas of finance.
B. Most of the people just share things without understanding anything from any post.
Fin-fluencers are like from 15 oct people will pay 2000+x or investment via zerodha will be 10000+y rs.
I am like seriously what is wrong with you all people and how did you all get so many followers with this kind of knowledge.
It is surely a problem for MERCHANTS because so far UPI MDR was free but it was never going to be like it always.
As of now compared to any other online method or instrument UPI MDR is very less and it's max value is also fixed.
Big merchants don't have any problems at all and very small merchants will not have any MDR. Only small to medium merchants will face problems due to small fees but that is going to be very minimal.
I do understand that Government has put MDR but it was always going to be like that.
In India we only want freebies it seems.
#banking
#UPI
#creditcards
#ccgeek
@vasishtanagalla Balinese are mostly Hindus. Cholas spread hinduism in the area. Their way of practising it has influenced by their local methods and practices through hundreds of years.
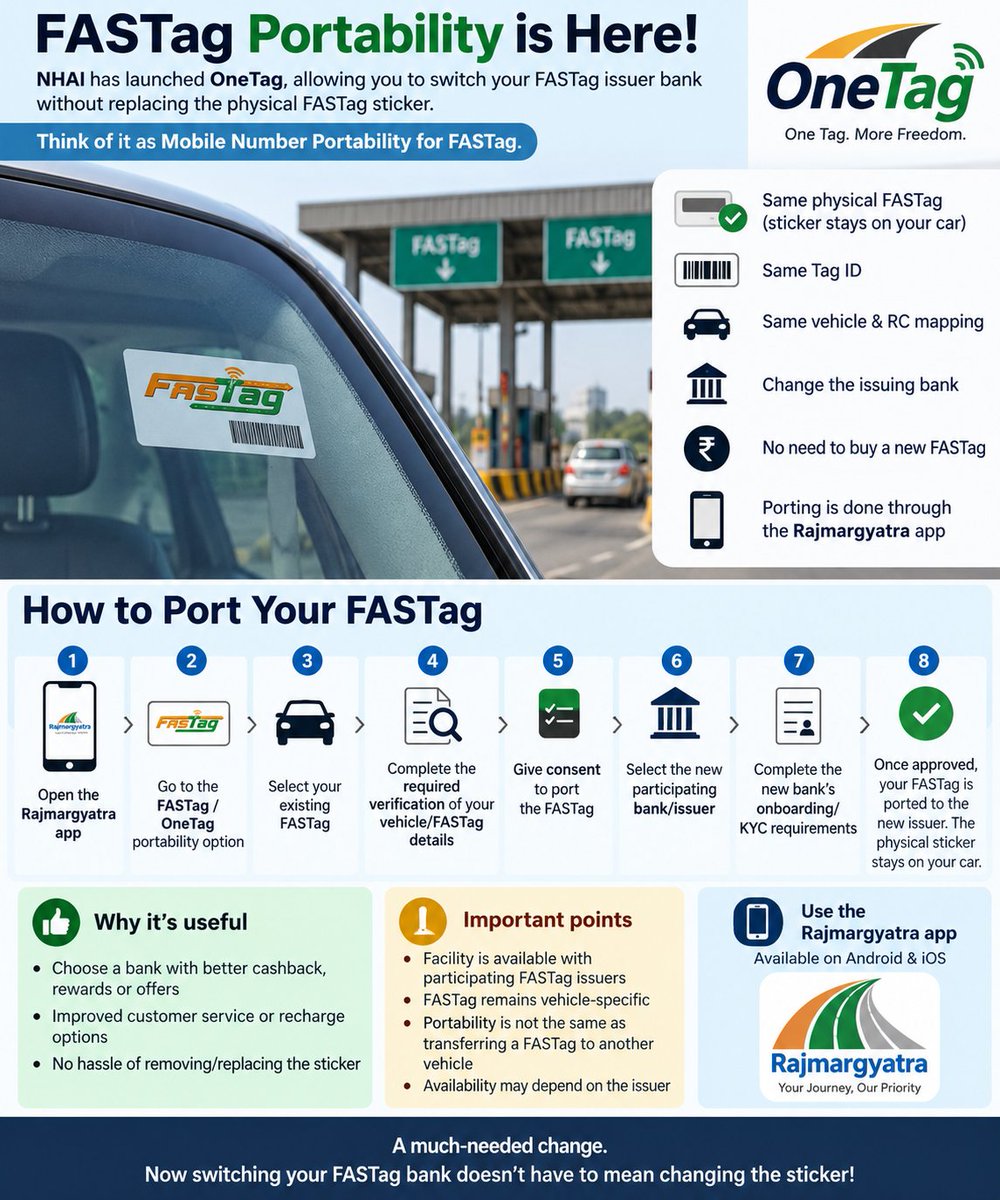
🚗 FASTag Portability is finally here!
NHAI has launched OneTag, which allows you to change your FASTag issuer bank without replacing the physical FASTag sticker.
Think of it as Mobile Number Portability for FASTag.
🔹 Same FASTag / Tag ID
🔹 Same vehicle & RC mapping
🔹 Change the issuing bank
🔹 No need to remove the sticker
🔹 Porting is done through the Rajmargyatra app
How to port your FASTag 👇
1️⃣ Open the Rajmargyatra app
2️⃣ Go to the FASTag / OneTag portability option
3️⃣ Select your existing FASTag
4️⃣ Complete the required verification of your vehicle/FASTag details
5️⃣ Give consent to port the FASTag
6️⃣ Select the new participating bank/issuer
7️⃣ Complete the new bank's onboarding/KYC requirements
8️⃣ Once approved, your FASTag is ported to the new issuer — the physical sticker stays on your car.
💡 This is particularly useful if another bank has better FASTag offers, cashback, service or recharge options.
⚠️ Portability is between participating FASTag issuers and is not the same as transferring a FASTag to another vehicle.
Shri Nitin Gadkari ji launched it at Global Fintech Fest 2026 on 11th September 2026.
A much-needed change. No more removing a perfectly good FASTag sticker just because you want to change the bank! 🚀
#banking
#hdfc
#ccgeek
It seems that IDFC FIRST Bank is taking banking and Credit Cards seriously. While bigger banks like HDFC bank and AXIS are just devaluing their services.
IDFC FIRST Bank has also kept reward points alive on their top credit cards. Reward Points on international transactions will continue to be earned on Ashva, Mayura, Gaj:, FIRST Private, FIRST WOW!, FIRST WOW! Black and IndiGo IDFC FIRST Bank Credit Cards.
I feel this is their iPhone moment as they have launched something new in the market.
Fintech cards like Scapia and ixigo will feel most heat out of this.
Hoping for a serious of revaluation on banking and Credit Cards Services in India.
Follow for more.
#hdfc #credit #ccgeek #new
BIG MOVE: IDFC FIRST Bank scraps forex markup across ALL credit cards.
In a major disruption to traditional retail banking, IDFC FIRST Bank MD & CEO V. Vaidyanathan announced that the bank is abolishing foreign exchange (FX) markups across its entire credit card portfolio.
Key Highlights:
* Zero FX Markup: Cardholders will pay 0% forex markup on international transactions, whether traveling overseas or shopping on international websites (industry standard sits between 3% and 3.5%).
* Includes Existing Customers: Unlike typical industry product refreshes that lock perks behind new card variants, this feature is automatically rolled out to all current cardholders—no upgrades, fee structures, or spend thresholds required.
* Customer-First Track Record: The move follows the bank’s earlier firsts, including monthly interest credits, zero-fee savings accounts, and lifetime-free credit cards.
* Speaking Appearance: Vaidyanathan will elaborate on human-centered innovation and AI in banking tomorrow at 10:30 AM at the Global Fintech Fest (GFF), Hall Jasmine 2.
A massive win for international travelers and global spenders alike.
#IDFCFIRSTBank #CreditCards #PersonalFinance #Fintech #Forex #GFF #BankingNews #TravelHacks #ccgeek
My Singapore trip turned out to be absolutely fantastic because I redeemed Accor Plus benefits and points.
The best part was staying at Swissotel, The Stamford, which was truly amazing.
#ccgeek#ccgeeks#Finance#stocks#Nifty50#Credit#upi#debit