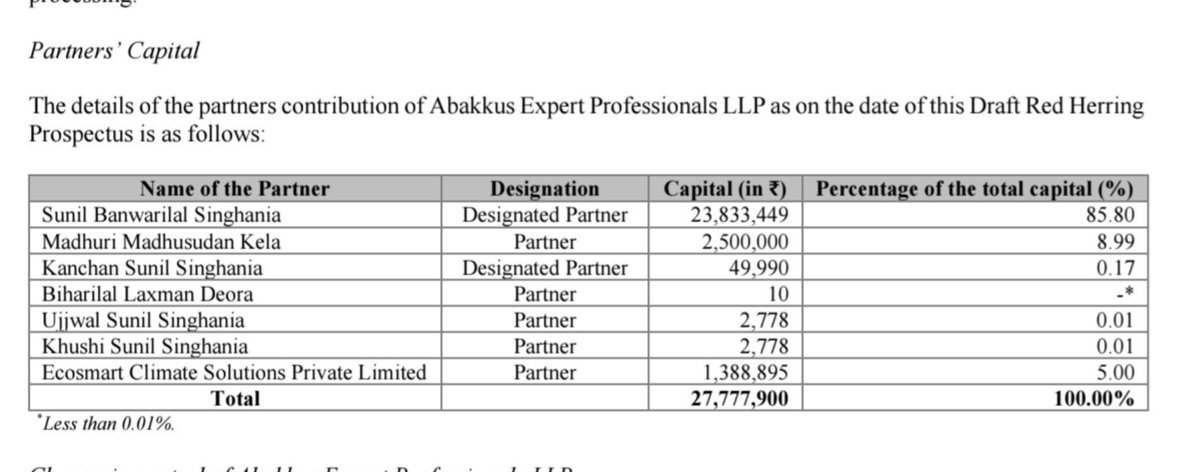
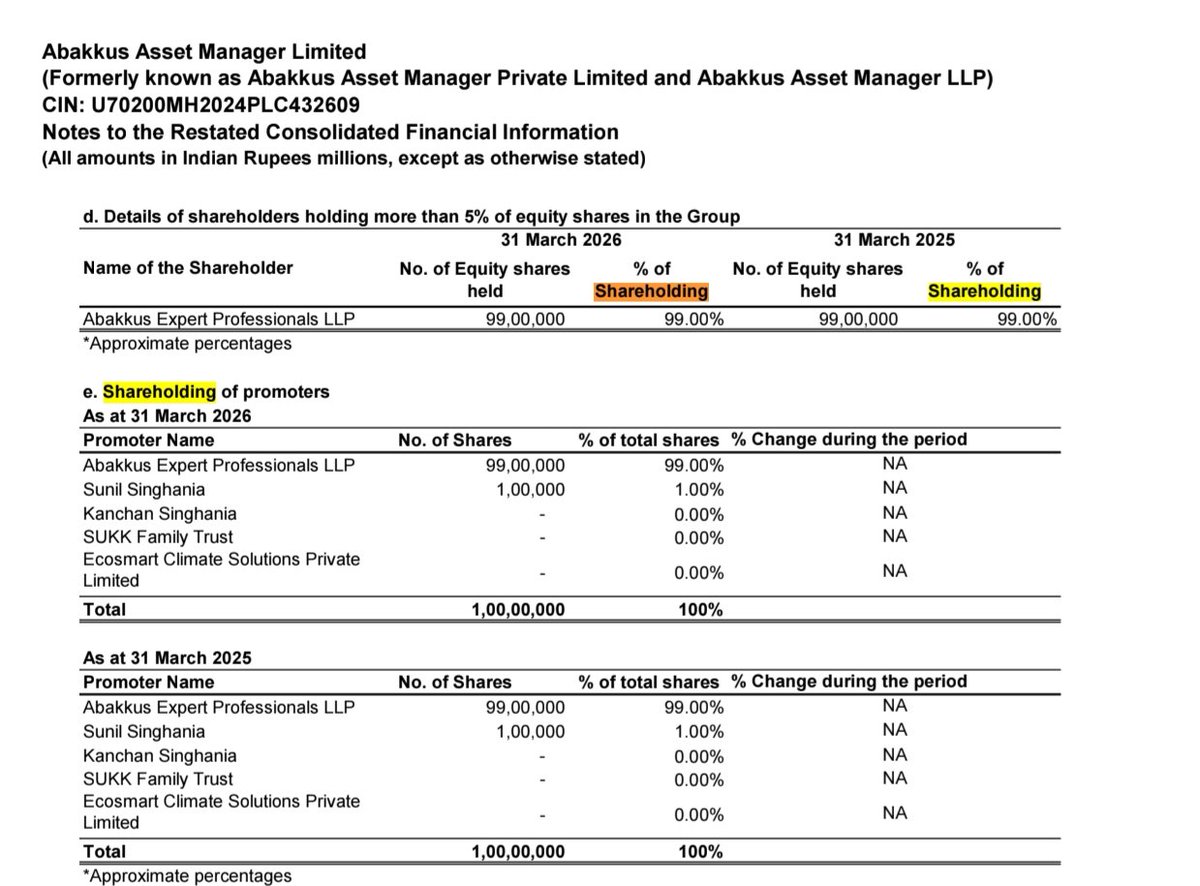
Most interesting thing found in Abakkus AMC DRHP
Madhu Kela is also partner in Sunil Singhania Abakkus AMC's Promoter entity
Indirectly holds 8.9% stake in the company
@PulkitA30298377 Receivables are up ~74% (₹23 cr → ₹40 cr), not 100%.
H1 FY27 revenue is already ₹100 cr+, against ₹136 cr for all of FY26, which is a ₹200 cr+ run-rate.
Receivables grow with sales. Debtor days have moved from ~62 to ~70: worth tracking, not a red flag.
The financial runway:
• H1 revenue: ₹100.79cr
• FY27 revenue guidance: ₹250cr
Management plans to revisit its outlook after mining begins.
Next Phase: A Move towards Pan-India Player
Mining Approval - Captive Sourcing
Inventory Optimisation
New Commercialised Plant Ramp-up
New South/West Capacity Expansion
Monolithisch: You Beauty 🤌
Again Blockbuster Q2 FY27:
• Revenue: ₹53.59cr, +88.2% YoY
• EBITDA: ₹15.80cr, +192.2%
• PAT: ₹11.17cr, +145.1%
But the bigger story is how backward integration could change its economics.
A 🧵on Monolithish- A Pan-India Player in Making
A Move towards making stronger Regional Play and becoming a Pan India Company
Due to cost reduction and logistical benefit- Mono give tough competition to everyone across east india belt
Next Pan India Plan
Proposed capex: ₹45cr
Additional capacity: 3 lakh tonnes annually
📍Near Hospet, Karnataka(South): 1.25 lakh tonnes annually, Target: Jul-27
📍Udaipur, Rajasthan(West): 1.75 lakh tonnes annually, Target: Nov-27
Why in West & South?
📍Proximity to steel and industrial customers can improve freight economics, delivery times and service.
📍Management also highlights access to potential export markets.
9/9 🎯 THE BIG TAKEAWAY
SEBI's order draws an important distinction between stock market education and regulated investment advice.
Teaching market concepts is one thing.
Providing actionable stock-specific recommendations, live trading guidance and targets for consideration is another.
Calling a service 'education' does not automatically exempt it from SEBI regulations.
Source: SEBI Final Order | Avadhut Sathe Trading Academy
@BeatTheStreet #SEBI #StockMarket #InvestorProtection
1/9 🚨 BIG SEBI ACTION AGAINST AVADHUT SATHE TRADING ACADEMY!
SEBI has passed a 171-page final order against Avadhut Sathe Trading Academy, Avadhut Sathe and Gouri Sathe.
💰 ₹546.17 Cr refund ordered
💰 ₹67.87 Cr interest
🚫 Securities market ban
⚖️ Additional monetary penalties
Here's what SEBI found 🧵👇
@BeatTheStreet10
8/9 📢 WHAT HAPPENS TO STUDENTS?
The academy and Avadhut Sathe must:
• Publish public notices within 30 days explaining the refund claim process
• Refund eligible participants through traceable banking channels
• Complete refunds within five months of receiving the order
• Submit a Chartered Accountant-certified compliance report to SEBI
Unclaimed balances will be handled under SEBI's prescribed process.
The bigger picture:
Jio’s IPO could mark an important step in its balance-sheet transformation. Lower debt, reduced currency exposure and stronger cash generation are meaningful improvements.
But a cleaner balance sheet does not automatically translate into substantially higher profits.
Jio Platforms plans to use ₹27,500 crore from its IPO to repay debt.
That is nearly 39% of its total borrowings.
But here’s the catch:
Even if Jio saves 10% annually on this debt, its profit could increase by less than 7%.
So, what does this IPO really change?
A thread 🧵
What could drive Jio’s earnings after listing?
Four factors stand out:
Higher average revenue per user (ARPU)
Lower capital expenditure(6G is already ready)
Stronger free cash flow after financial obligations
Returns from broadband, enterprise and digital investments
Jio’s monthly ARPU has already increased from ₹182 to ₹214 over the two years.