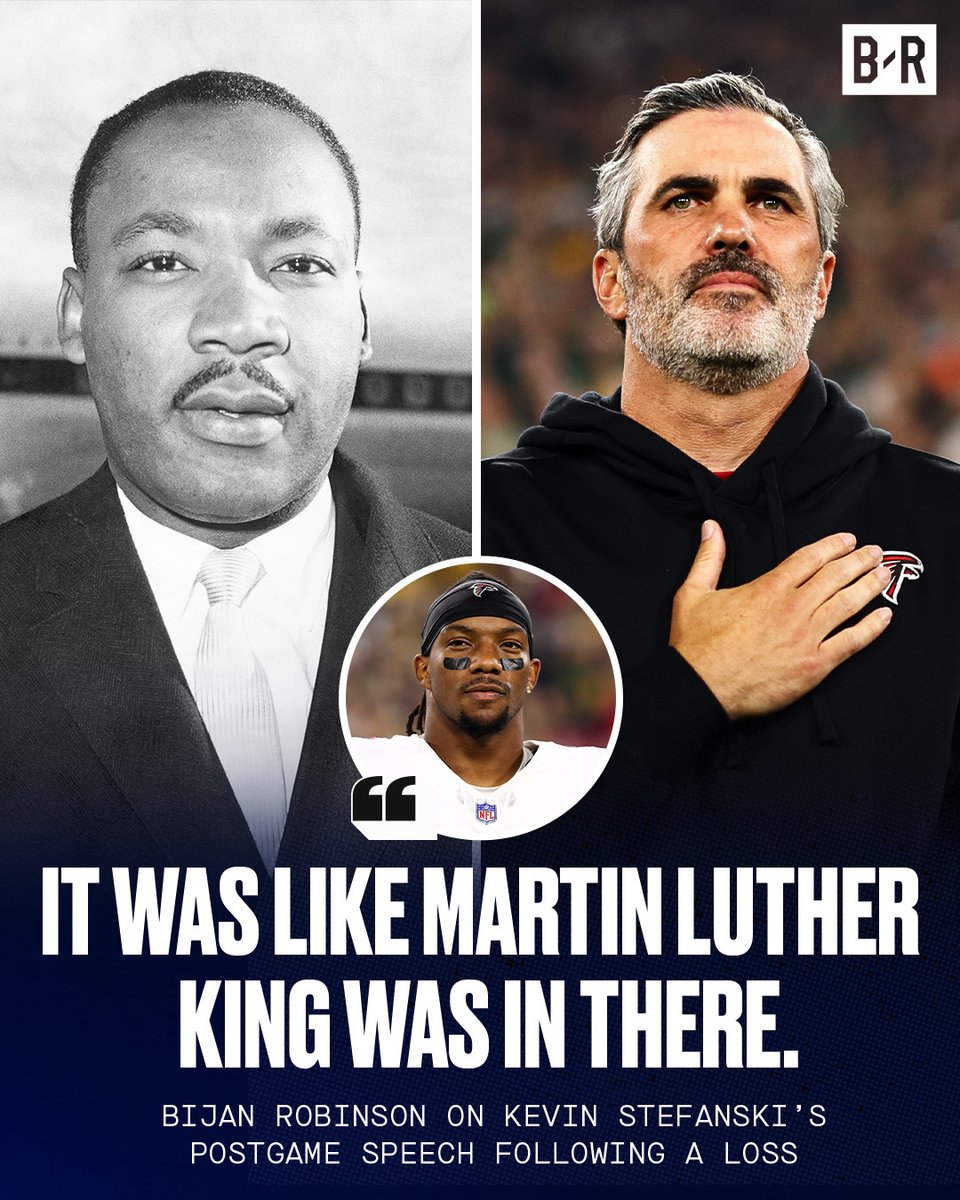
Bijan Robinson says Kevin Stefanski brought the Falcons together with a speech after the Panthers loss that reminded him of Martin Luther King
Atlanta responded with a 21-point win over the Packers at Lambeau 🔥
(Via @SportsonPrime)
Did a review of $TPB Today as a result of the sell off. full disclosure, Our fund has a long position in TPB.
I think the CEO leaving 8-k does read like there was a personal issue, I don't think the board has had an issue with the CEO and based on the PR it does seem like there are some immediate personal issues that happened; however, that announcement along with a guide down on ebitda is gonna have the market say "why do I want you now when I could buy something that's working?" regardless if the reason is that shipping costs are up a lot (look at oil prices and $BWET to get an idea on how much it's changed).
The market has a hard time understanding growth opex, I think if you find and understand businessses that are doing well and truly have a good time horizon, then investing in a company going through a growth opex cycle often allows you to get a company very cheap. A good example that people can understand today is $META a lot of their investments have been via opex (there is capex as well, but they more than others have done a lot of opex investment into their biz). The market doesn't understand the opex investment until it starts to see the fruits of it, and it hasn't yet with $TPB yet.
Another problem for TPB is the chart is terrible, if you're a chartist I think you unanimously say the direction for TPB is simply "lower".
I think if you look at and understand TPB and their growth opex strategy, it makes a lot of sense and is the correct move. They are growing their oral segment >100% this year and it doesn't seem the momentum is slowing down as I see them opening up all around the USA and now in europe as well.
To understand growth opex, you need to be able to understand the underlying earnings power of the business and in my opinion most people don't understand or often care to do that. If you look at the company's Ebitda as a % of gross profit in 2025, it was roughly 45% (120M of Ebitda on 264M of gross profit). That is probably close to the underlying true earnings power of the company, but since they are going through this opex cycle (investing in marketing and sales), Ebitda as a % of gross profit decreased to 16%.
This is an intentional move by the company, they are doing this because they see a great opportunity in front of them and think the ROI is better than simply returning to cash to shareholders and growing in a slower manner.
Back to the part about the PMTA, the market, in my view understandably, is concerned about the investment because: 1. they don't understand opex investment but more importantly, or at least more understandably, they are worried about all of this investment having negative ROI because of regulators.
IF the regulators give TPB the ok, then you're seeing a business that is trading at roughly 6x CY 27 underlying ebitda in my model and is still in an amazing position to grow for many years in this new market for years after that.