BlackGreep is moving toward its first Closed Beta.
We’re building a trading research platform designed to answer one question:
Does your strategy still have an edge when the backtest gets harder to fool?
The first Beta is planned for spring / early summer 2027.
Initial focus:
• causal backtesting
• strategy validation
• execution & ambiguity analysis
• risk analytics
• out-of-sample testing
• paper trading
• detailed research reports
No promises of guaranteed returns.
If a strategy is bad, BlackGreep should be able to show you why before real money is involved.
We’re testing the platform on our own strategies first — and publishing the failures too.
Closed Beta applications will open before launch.
Follow @BlackGreepHQ if you want early access.
Validate before real money.
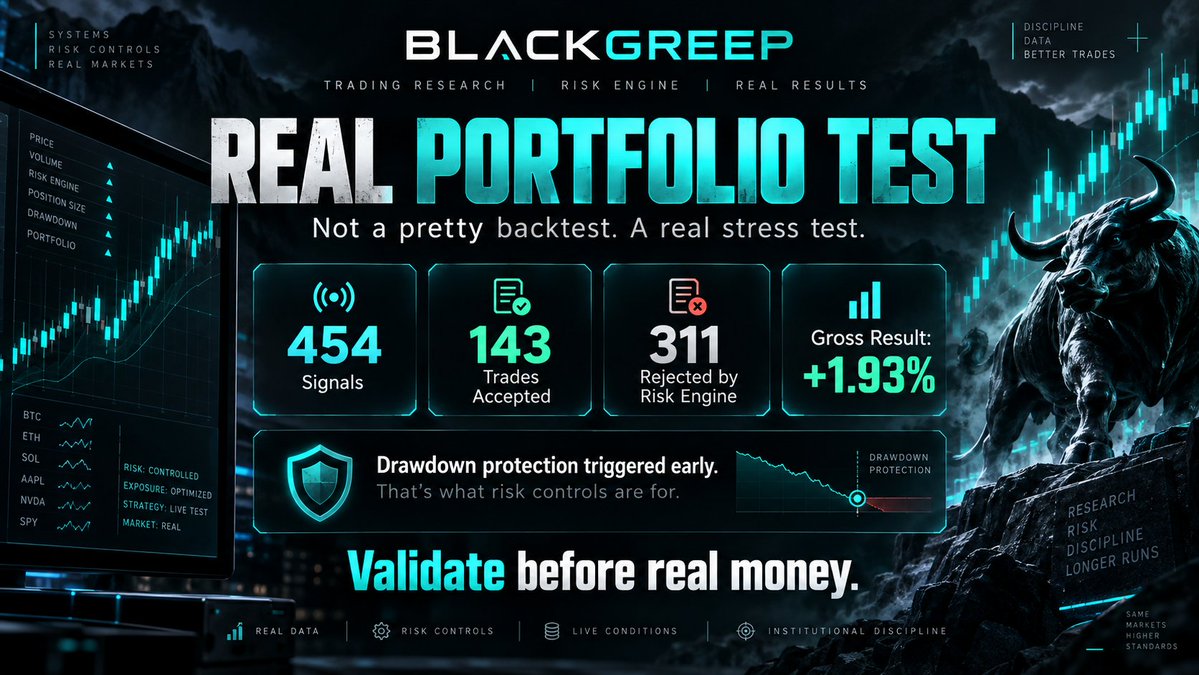
We just tested BlackGreep as a real multi-asset portfolio.
454 strategy signals.
143 trades accepted.
311 rejected by the risk engine.
Gross result: +1.93%.
Sounds disappointing?
Good.
The portfolio hit its drawdown protection early, and the system stopped accepting new trades.
That's exactly what risk controls are supposed to do.
We're not optimizing BlackGreep to produce beautiful backtests.
We're building it to expose where a strategy breaks.
Validate before real money.
@Hacikan39622P Exactly. That’s why fees, slippage and funding are next in our validation stack.
If the edge disappears under realistic execution, it wasn’t robust enough.
A profitable backtest doesn't mean you have a profitable strategy.
Change the stop-loss.
Add realistic fees.
Test another market.
Watch how quickly the “edge” disappears.
We're building BlackGreep to challenge trading strategies, not sell dreams.
Agree or disagree?
#AlgoTrading #Trading #Crypto #BTC
Most trading tools help you make a backtest look better.
We want BlackGreep to do the opposite.
Try to break the strategy.
Find the hidden assumptions.
Stress the execution.
Expose where the edge disappears.
Only then ask if it deserves real money.
Validate before real money.
-7.49% → +34.64%
We changed ONE thing.
We only allowed setups from zones with exactly one prior touch.
BTCUSDT · 5m · 1 year
145 trades
42.1% win rate
8.2% max drawdown
Everything else stayed the same.
This is still a backtest.
No fees. No slippage. No funding.
No victory lap.
Now we freeze the rules and try to break them on another market.
That’s what BlackGreep is about:
Validate before real money.
#BTC
The internet loves stories like:
“I turned $68 into $750,000 with an AI trading bot.”
I have one question:
Show the fills.
Show the fees.
Show the slippage.
Show the losing trades.
Show the deposits and withdrawals.
Show what happens when execution assumptions get worse.
A beautiful equity curve proves almost nothing.
We recently watched a +167% BlackGreep backtest disappear after fixing unrealistic execution assumptions.
Good.
I’d rather kill a fake edge in research than discover it was fake with real money.
Would you trust an AI trading bot without verifiable execution data?
We currently treat wick penetration/touch as a valid stop or target hit — we do not wait for a candle close.
The stop itself is fixed from causal information available before entry. If both SL and TP are touched inside the same 5m candle, we drill down to 1m data to resolve the order where possible. If the 1m candle is still ambiguous, we keep that trade explicitly ambiguous rather than pretending we know the execution order.
The new stop floor changes stop placement, not the hit-validation rule.
Today’s BlackGreep research update:
A +167% backtest result disappeared after fixing unrealistic stop-loss behavior and intrabar ambiguity.
That’s a good result.
We tested fixed and ATR-based stop floors, reduced leverage distortion, and moved the strategy much closer to realistic execution.
Current focus: finding whether the edge is actually in the setups — not in backtest assumptions.
Build the research engine first. Trust the P&L later.
Next: causal setup-quality validation and out-of-sample testing.
@CoinTech2u Yes — unresolved ambiguity will stay a separate bucket, with no guessed P&L in the canonical result.
We also want to expose SL-first vs TP-first as separate what-if scenarios, so the uncertainty itself becomes measurable.
First real BTCUSDT research run is done.
BlackGreep found a SHORT on live public Bybit data. 5m hit both SL and TP.
We drilled down to 1m — still ambiguous.
No fake win. No fake loss.
Next: multi-trade backtesting.
BlackGreep is getting closer to its first real-market research run.
✅ Bybit linear market data
✅ Research Dataset v1
✅ Causal backtesting pipeline
✅ Risk & trade planning integration
✅ 2,074 tests passing
Next: read-only BTCUSDT research on real historical data.
Most traders don’t lose because they lack strategies.
They lose because they never truly validate them.
A setup can look perfect on a chart and still fail with fees, slippage, bad fills and drawdowns.
BlackGreep is built to expose that before real money is at risk.
If one candle touches both the stop-loss and take-profit, OHLC data alone can’t tell you which happened first.
BlackGreep marks that trade as ambiguous instead of silently choosing the profitable outcome.
Small detail. Big difference in backtest honesty.
Most trading bots start with promises. BlackGreep starts with testing.
We're building a platform to validate strategies before real money: market structure, liquidity, risk, backtesting, paper trading — then AI.
If a strategy is bad, the system should prove it first.