In part, just felt like a "sell the news" event since they had been projecting to hit adjusted EBITDA breakeven this quarter for quite a while. Also wasn't a great time to report given the broader market dropping, but the capex increase and skepticism around future AI drug discovery projections also likely played a role.
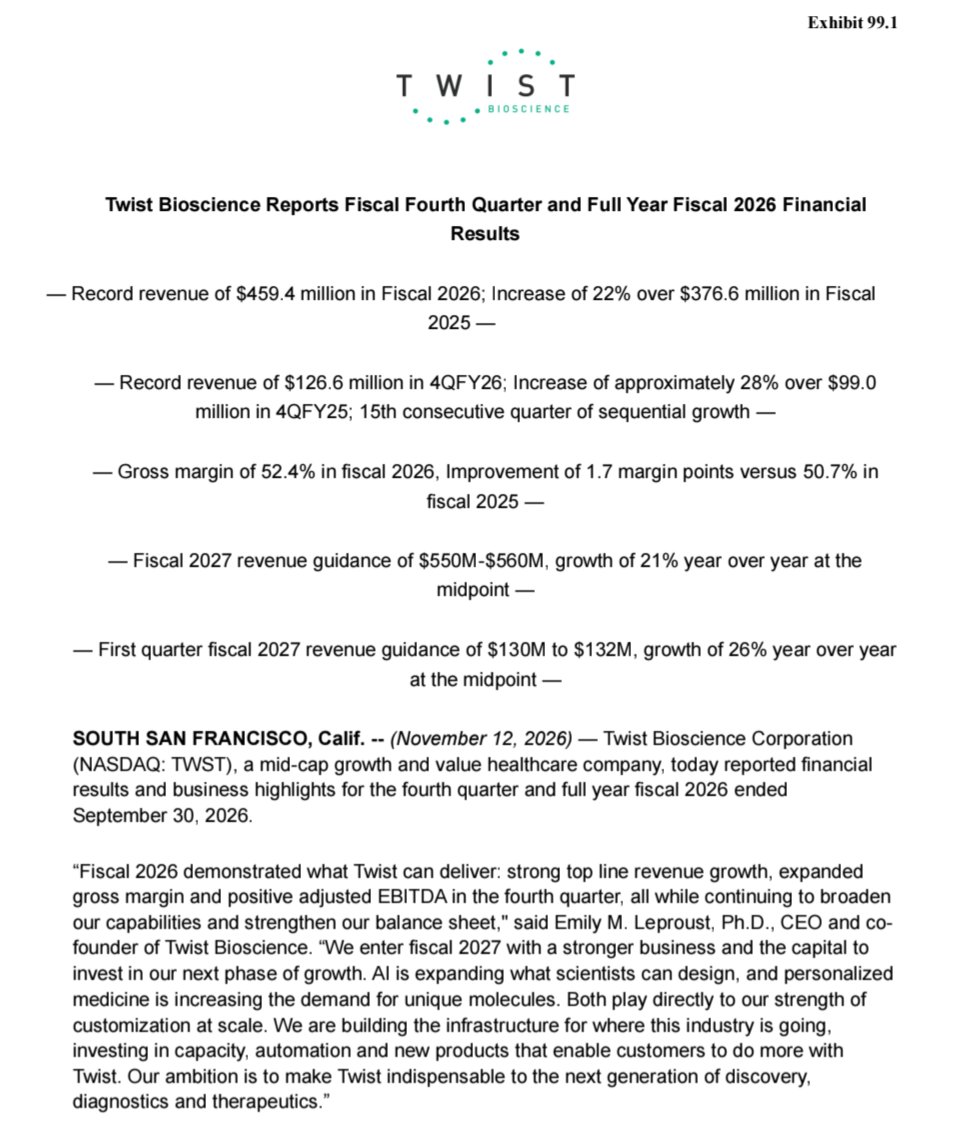
$TWST Twist reported 4Q and full-year FY26 earnings, hitting their Adjusted EBITDA breakeven target while accelerating revenue growth and expanding margins. They also shared more numbers around their AI drug discovery business and a massive capacity expansion plan.
Some key highlights:
1) Headline Numbers & Achieving Breakeven
• 4Q Revenue: $126.6M (+28% YoY), beating guidance of $123M-$124M and marking 15 straight quarters of sequential growth.
• FY26 Revenue: $459.4M (+22% YoY), finishing about $30M (+7%) above initial FY26 guidance.
• Gross Margin Expansion: 4Q gross margin hit 53.1% (+180 bps YoY), bringing FY26 gross margin to 52.4% (+170 bps YoY).
• Profitability Inflection: Hit their Q4 target with positive Adjusted EBITDA of $2.2M (vs. a $7.8M loss in 4Q25). 4Q GAAP net loss narrowed to $20.6M or $(0.32)/share.
• Strong Balance Sheet: Ended FY26 with $582M in cash and investments after raising about $425M in net proceeds.
2) Segment Breakdown & The AI Discovery Engine
• DNA Synthesis & Protein Solutions: 4Q revenue grew 33% YoY (+8% QoQ) to $61.0M (FY26 up 32% to $221.9M). Shipped about 401K genes in Q4 (+49% YoY) and 1.3M in FY26 (+43% YoY), while internal gene volume for protein and characterization workflows more than doubled YoY.
• AI Drug Discovery Surge: AI-enabled discovery revenue reached $59.1M in FY26, surging 175% YoY. As customers design millions of sequences in silico, Twist acts as the physical Design-Build-Test engine, supported by Express Screening Antibodies, 5-day antibody turnaround times, and joining Lilly's TuneLab.
• NGS Applications: 4Q revenue accelerated to 24% YoY growth (+6% QoQ) at $65.7M (FY26 up 14% to $237.5M), driven by commercial diagnostic volumes.
• MRD & mRNA: MRD added 1-2 pts of growth in FY26, and MRD Express launched in late October (custom panels up to 10K probes shipped in as little as 1 day). Also supplying research-grade mRNA to early access customers with plans for a high-throughput offering.
3) Scaling to $1B+ Capacity & FY27 Guidance
• $150M CapEx Plan: Investing $150M across FY27-FY28 (about $75M in FY27) to support $1B+ in annual revenue capacity. Integrated systems will grow from 20 to 26 in 2027, with protein characterization capacity expanding up to 5x off the FY26 base.
• Strong FY27 Guide: Guided FY27 revenue to $550M-$560M (+21% YoY at midpoint) and 1Q27 to $130M-$132M (+26% YoY). Assumes $100M in AI drug discovery revenue (with upside opportunity), 52.5%-53% gross margins, and positive full-year Adjusted EBITDA.
To summarize, Twist just crossed the Adjusted EBITDA breakeven threshold while growing the top line 28% YoY. With $582M in cash, AI revenue up 175% YoY and projected to hit $100M+ in FY27, MRD Express live, and a clear CapEx roadmap to unlock $1B+ in annual capacity, I believe the operational flywheel is hitting its stride heading into 2027.
Your heart, brain, and immune system share the same DNA sequence. So how can a single-letter change affect disease in some cells, while sparing the rest?
AlphaGenome 2 is our new AI model that zooms in on specific cells to help scientists understand what drives disease. 🧵
BREAKING: An open letter to reinstate Jensen Huang as CEO of Nvidia, $NVDA, now has over 65,000 signatures, alleging that Huang was removed "without meaningful due process."
The letter has been signed by more than 35,000 shareholders and 4,700 current and former Nvidia employees.
Elon Musk has publicly stated that he has signed the petition and fully supports Huang's return to the company.
We maintain our view that Huang was removed prematurely, without a conclusive investigation.
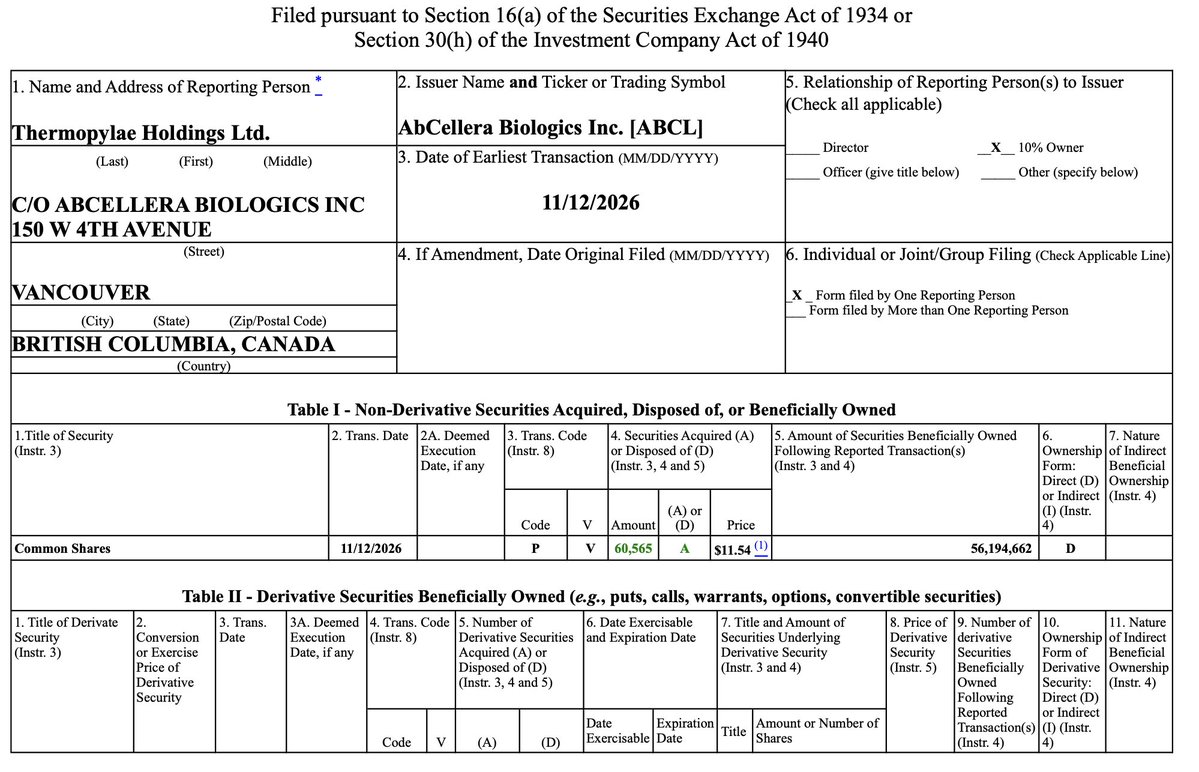
$ABCL More insider buying! Thermopylae Holdings (CEO Carl Hansen's holding company) acquired 60,565 shares (about $699K total) on the open market 💪
• Weighted-Average Price: $11.54 (ranging from $11.29 to $11.86)
• Total Holdings: 56,194,662 shares following the purchase
Good to see Carl continuing to add after Q3 earnings and the new pipeline updates.
Owned Nvidia since 2021, started trimming to rotate heavier into AI Biotech late last year and sold the last of my shares at the end of September. Crazy to think about the timing in hindsight...
$ABCL Good interview with AbCellera CEO Carl Hansen at Stifel, mostly reiterated or expanded on the news from earnings but here are some initial notes I found interesting:
1) Sleep Relief Without Somnolence
• The oral VMS pill Lynkuet hits both NK3R and NK1R, bringing daytime drowsiness risks. As a pure NK3R antibody, ABCL635 delivered sleep improvements at least equal to Lynkuet without somnolence (drowsiness).
2) "Multiples of a Blockbuster" & DTC Playbook
• With efficacy comparable to hormone therapy (HT) and no liver tox, Carl noted the commercial profile looks like multiples of a blockbuster and could expand beyond HT-ineligible patients to any woman who prefers a safe monthly autoinjector.
• Because women easily self-diagnose hot flashes, VMS drugs could potentially fit the GLP-1 telehealth/DTC playbook down the road, allowing commercialization without a massive sales force.
3) ABCL992 (VMS Follow-on)
• AbCellera recently unveiled ABCL992, a half-life extended follow-on to ABCL635. Carl emphasized they remain all-in on ABCL635, and ABCL992 could be both a defensive and offensive move to lock down the market.
• Theoretically moving dosing to something closer to every 3 months (quarterly) could cut cost of goods sold (COGS) by 3x and triple manufacturing supply, providing huge optionality across different geographies, indications, or pricing tiers.
4) Thinking Beyond VMS
• ABCL688 and ABCL386 are in IND-enabling studies, followed-up by newly announced development candidates ABCL992, ABCL385 (undisclosed oncology), and ABCL646 (first-in-class antagonist antibody against an ion channel target).
(Apologies if I've misheard anything, planning to re-listen later)
$ABCL The golden eggs keep coming 💪
Considering AbCellera only guided to nominating at least 1 new candidate in 2026, dropping 3 at once is an awesome beat on execution.
Quick recap of all 7 internal molecules in the pipeline:
– NEWLY ANNOUNCED (IND-ENABLING)
• ABCL992 (NK3R): A next-generation, half-life extended analog of ABCL635 for vasomotor symptoms (hot flashes), engineered to support even less frequent dosing.
• ABCL385 (Oncology): An antibody candidate targeting an undisclosed oncology indication.
• ABCL646 (Ion Channel): A potential first-in-class antibody antagonist against an undisclosed ion channel target and indication.
– EXISTING PRECLINICAL (IND-ENABLING)
• ABCL688 (Autoimmunity): Targets an undisclosed GPCR or ion channel. Continues to progress through IND-enabling studies toward a 2027 clinical start.
• ABCL386 (Oncology): Targets an undisclosed oncology target, also advancing through IND-enabling studies for a 2027 trial initiation.
– EXISTING CLINICAL-STAGE
• ABCL635 (NK3R): Following standout Phase 2 data in menopausal VMS (50% placebo-adjusted drop in frequency, zero liver signals), AbCellera will share 12-week and open-label extension data in early 2027 before starting Phase 3.
• They are also expanding ABCL635 into two new oncology trials in 2027 for hot flashes caused by hormone-suppressing breast cancer (AET) and prostate cancer (ADT) treatments.
• ABCL575 (OX40L): Top-line Phase 1 results in 40 healthy volunteers met all endpoints. It showed a clean safety profile across all doses (75mg to 900mg) and a roughly 65-day half-life that easily supports dosing once every 12+ weeks. As previously announced, AbCellera won't develop it in-house beyond Phase 1.
AbCellera is rapidly scaling their internal GPCR, ion channel, and oncology programs while turning ABCL635 into a multi-indication franchise.
$ABCL AbCellera reported Q3 2026 earnings, highlighting 3 new preclinical assets, label expansion plans plus a next-gen follow-on for 635, and nearly $900M in liquidity 🙌
Some key highlights:
1) Building a VMS Franchise Around ABCL635
• Late-Stage Menopause Trial: Following positive Phase 2 top-line data showing significant reductions in moderate-to-severe hot flashes (VMS) and improved sleep, AbCellera remains on track to start late-stage development in menopausal VMS in 2027.
• Expanding into Oncology Support: As previously revealed, AbCellera is expanding 635 into 2 new indications to treat hot flashes caused by hormone-suppressing therapies in breast and prostate cancer patients, with clinical trials in both groups slated to start in 2027.
• Next-Gen Analog (ABCL992): Officially unveiled ABCL992, a next-generation, half-life extended antibody analog of ABCL635 for VMS that has entered IND-enabling studies (mentioned previously by management).
2) Confirmed Shelving ABCL575 (OX40L) Despite Hitting Phase 1 Endpoints
• Clean Phase 1 Readout: Top-line Phase 1 data for ABCL575 in atopic dermatitis and autoimmune conditions met all endpoints, showing favorable tolerability and pharmacokinetics supporting an extended dosing schedule.
• Stopping Internal Development: Despite hitting its Phase 1 goals, AbCellera confirme they do not plan to advance ABCL575 past Phase 1.
3) Expanding the Internal Pipeline & Partnered Portfolio Updates
• New Preclinical Programs: Alongside 386 and 688, AbCellera advanced 2 additional programs into IND-enabling activities: ABCL385 (an antibody for an undisclosed oncology target) and ABCL646 (a potential first-in-class antibody antagonist targeting an undisclosed ion channel).
• Partnered Programs: Partners are currently leading 34 progressing programs where AbCellera holds a downstream stake, including 12 molecules actively progressing in the clinic as of Sept 30.
4) Financials, Cost Discipline & Liquidity Fortress
• Narrowing Losses via Cost Cuts: Q3 revenue rose to $10.6M (up from $9.0M in Q3 2025), driven primarily by $10.5M in research fees. Meanwhile, R&D expenses dropped to $43.5M (down from $55.0M YoY) and SG&A was nearly cut in half to $13.6M (down from $25.0M YoY), narrowing Q3 net loss to $40.8M or $(0.13)/share (vs. $57.1M or $(0.19)/share in Q3 2025).
• Positive YTD Operating Cash Flow: Over the first 9 months of 2026, AbCellera generated $19.3M in positive operating cash flow. This was supported by a $66.1M inflow from deferred revenue (total deferred revenue on the balance sheet rose to $83.1M, up from $17M at year-end 2025), alongside property and equipment CapEx dropping to $7.6M YTD.
• Nearly $900M in Liquidity: Following its $200M share and pre-funded warrant offering ($188.8M in net proceeds), AbCellera ended Q3 with over $790M in cash, equivalents, and marketable securities, plus more than $100M in available non-dilutive government funding for over $890M in total available liquidity.
To summarize, AbCellera is showing real capital discipline as it pivots into a clinical-stage biotech. Rather than burning cash across every program, they're still shelving 575 after Ph1, slashing SG&A and CapEx, and putting their $890M+ in liquidity behind a high-conviction VMS franchise (expanding 635 into breast and prostate cancer VMS while advancing long-acting ABCL992) and new first-in-class internal targets like ion channels.