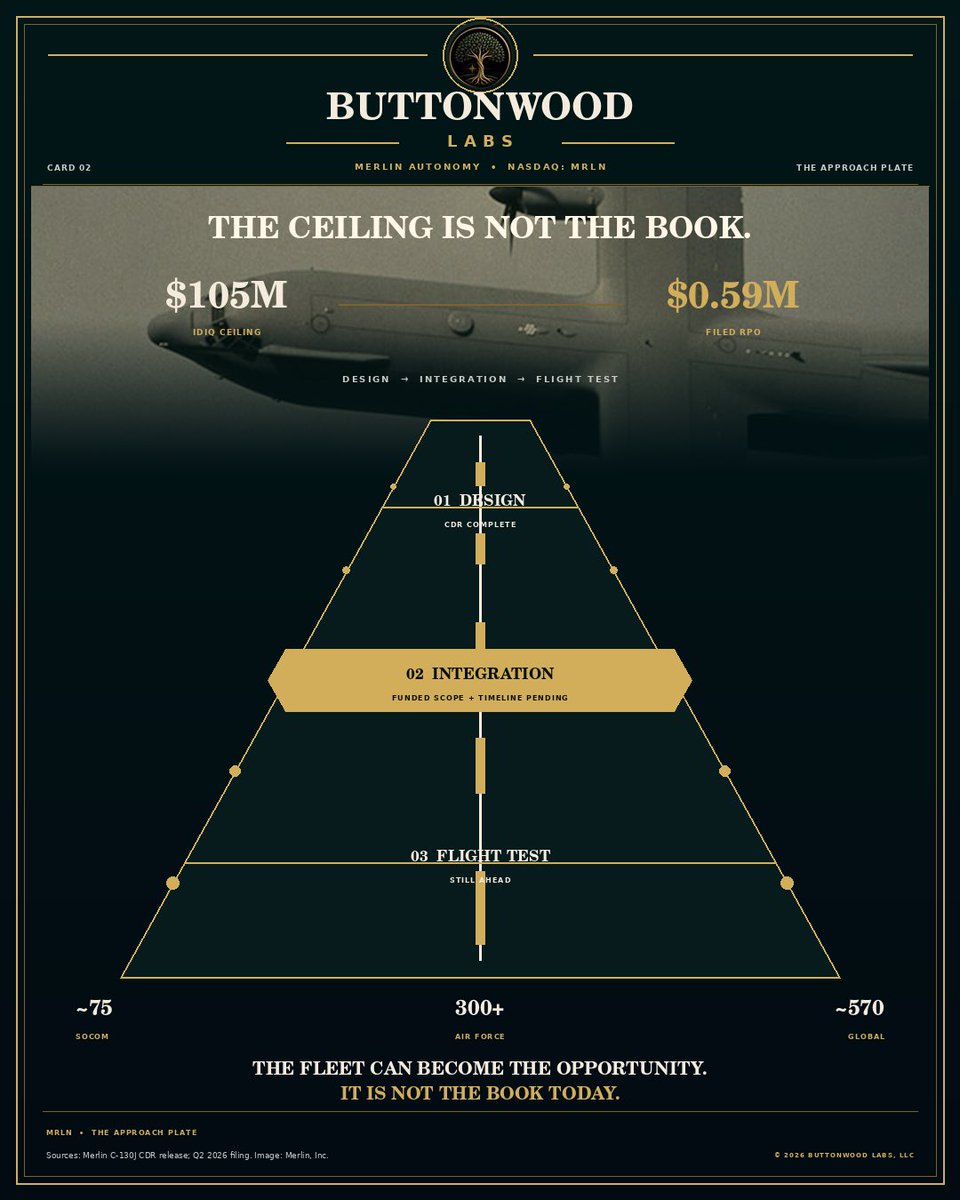
$MRLN can land the airplane. The stock is still in a holding pattern over BOS, waiting on clearance.
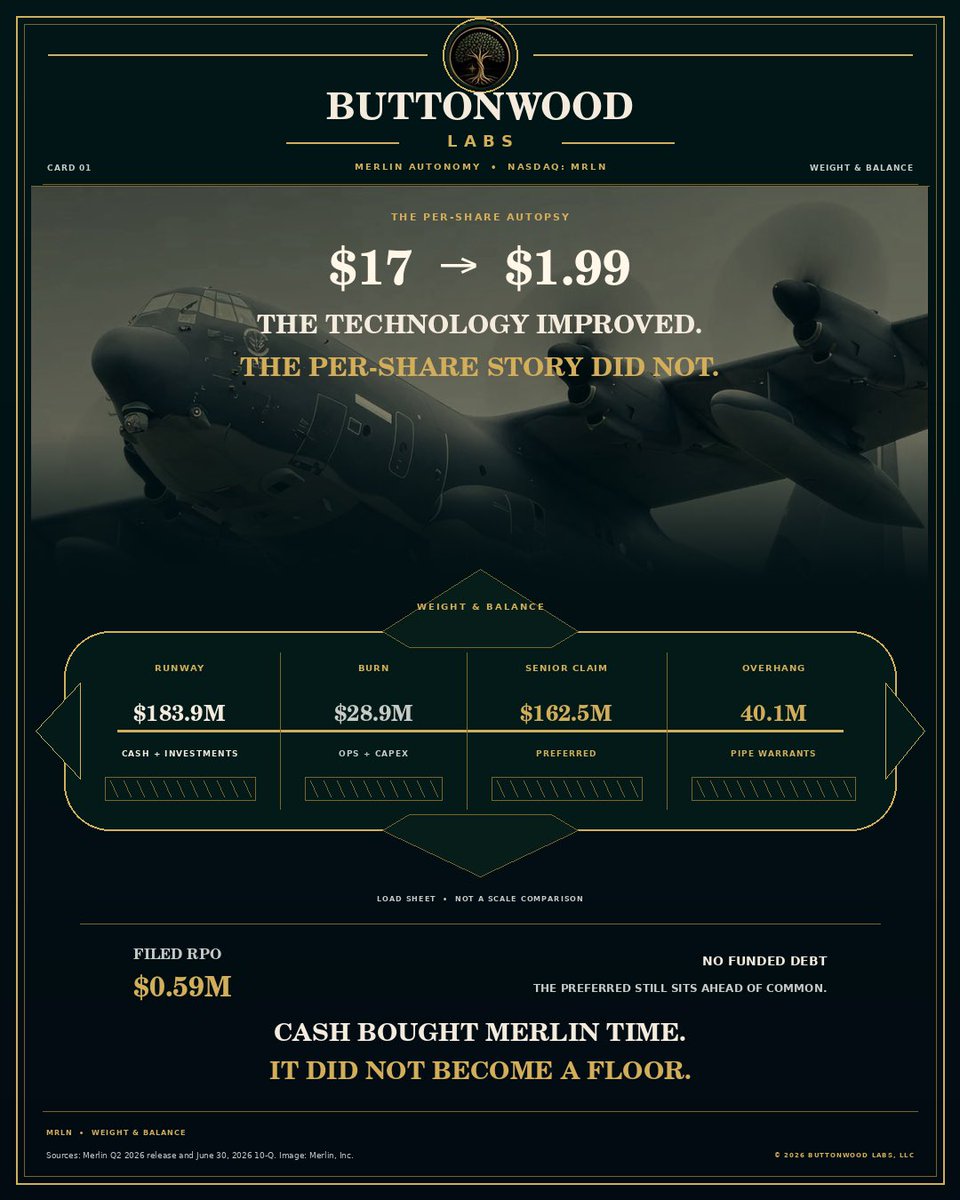
CDR is done. The $105M figure is a ceiling. Filed work left on the books was $0.59M. The $184M cash pile comes with $162.5M of preferred sitting in the front row.
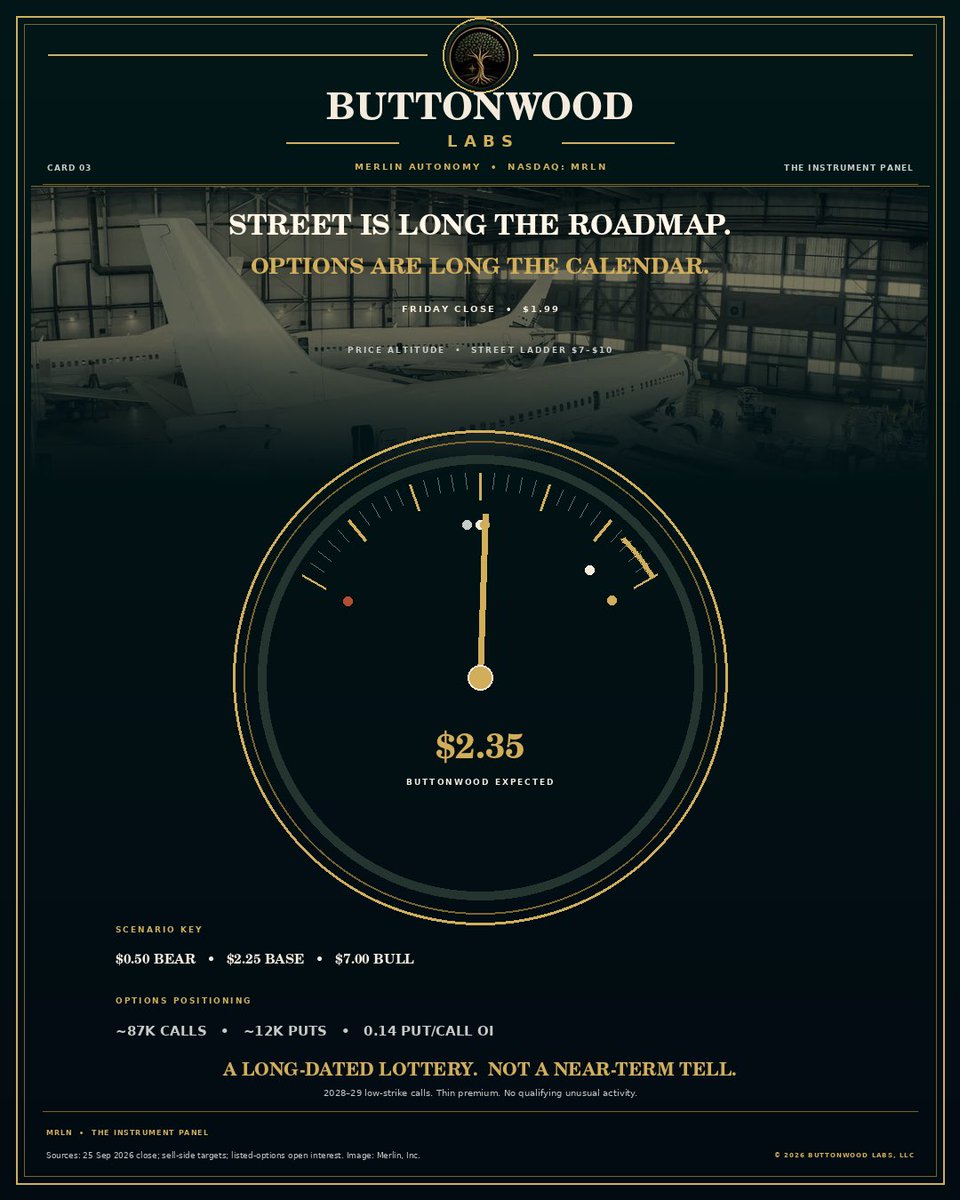
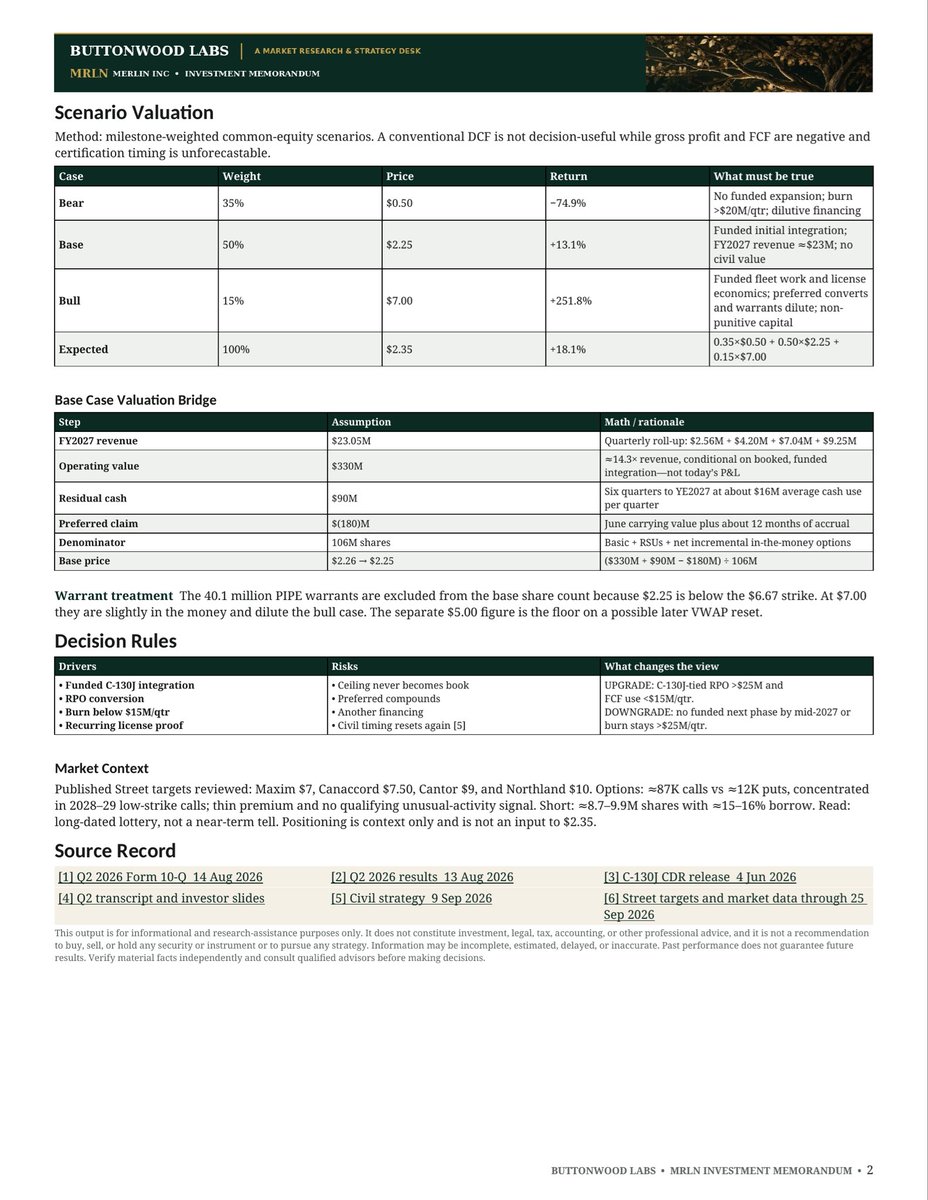
Street has it at $7–$10. I have it at $2.35 until integration shows up as booked revenue.
$MRLN #MRLN #Defense #Autonomy
That’s a fair split. I don’t ignore the TAM or Merlin’s position — those are why I think it’s vectored toward the bull case. But it will take more than an E-6B to get all the way there.
I’d argue this framework matters more for emerging companies, not less. Technical promise is not yet per-share value. Funded work, commercialization, cash burn, preferred claims and dilution determine how much of the eventual upside reaches today’s common shareholder.
That’s why the framework gives $MRLN a $7 bull case, but a $2.35 value on the evidence currently booked. I’ll move as the evidence moves.
Appreciate the exchange — and the follow.
@1MoreSmithHere@ke0in Here’s the work behind the $2.35.
Filed RPO $0.593M, not the $105M ceiling. Cash $184M with $162.5M preferred in front. Base is funded initial integration at ~$23M FY27 revenue; Street $7–$10 waits on fleet work I am not counting yet.
Not advice.
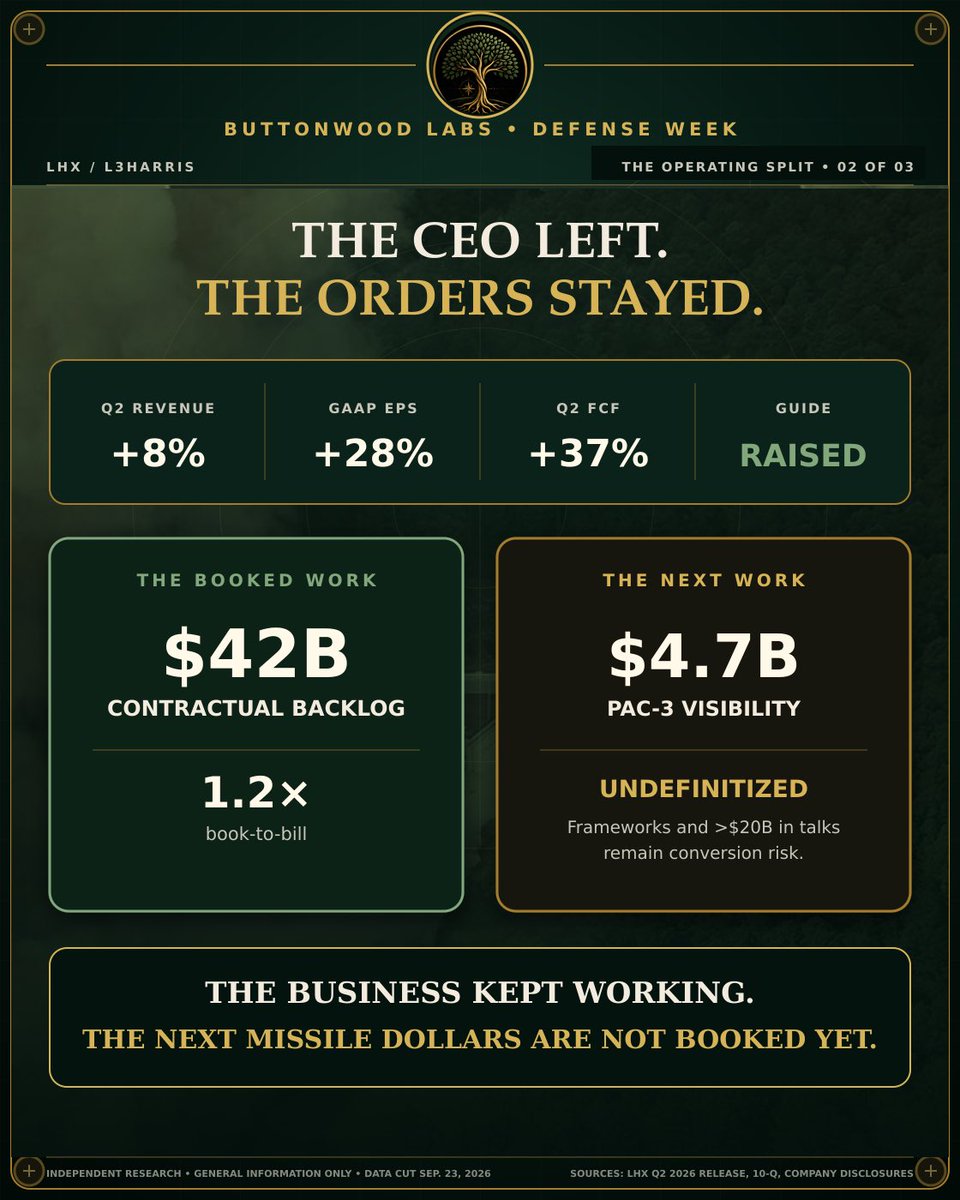
The CEO left. The orders stayed.
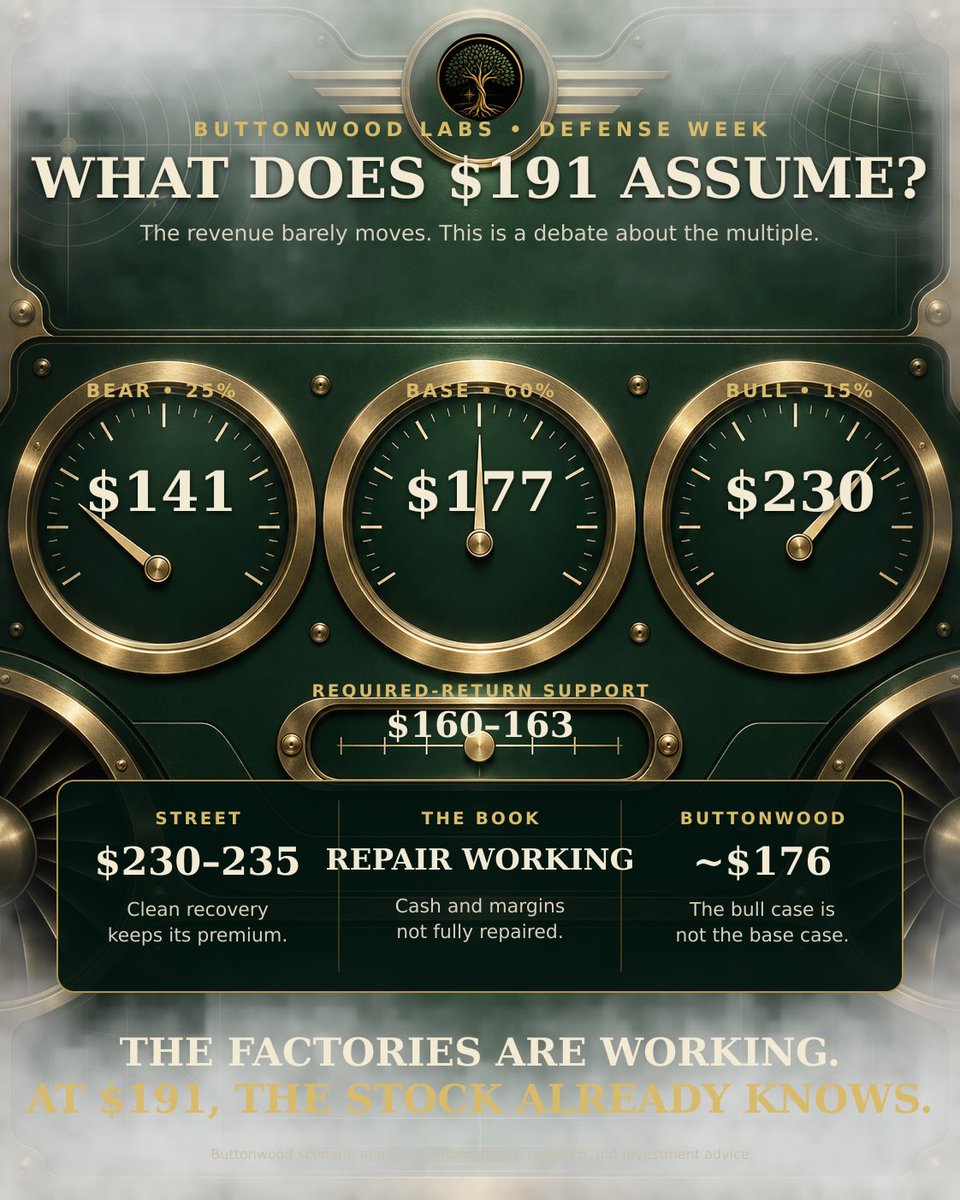
$379 priced a clean compounder. $239 prices a company that has to earn trust twice: quiet leadership, and missile frameworks that become booked work.
$LHX #DefenseStocks
@InsiderFinancex Closed above the line that usually helps the upside, then spent the session buying puts at $773. That’s not a breakout. That’s “we can go higher” with one hand and “please don’t” with the other. $780 only matters if $773 stops getting defended.
Hey nerds, here’s what I have for you today:
RTX did not fall because the missiles forgot how to fly. It fell because the post-earnings price briefly asked Pratt to graduate, Collins to become GE, and Raytheon to convert the entire backlog before lunch.
$RTX #Defense#Aerospace
20-30MW is “tiny” until you do the Starbucks math.
A normal store pulls ~15 kW.
That’s 1,300–2,000 stores running around the clock.
Or, in seasonal units: about a million pumpkin spice lattes a day.
They’re not hunting spare outlets. They’re hunting the power equivalent of every @Starbucks between Chicago and Indy, all of them on at once, all of them ringing up PSL.
The constraint isn’t who can announce the biggest campus. It’s who can turn already-interconnected power into usable tokens first.
@investing_girl $IREN $CIFR $WULF $CORZ
Day 3. Different jet.
Kratos used to be $134. That price treated Valkyrie like a production line and engines like the second act. Then they sold 16 million shares at $84 to build the factory. Smart financing. Still more shares.
The jet is the poster. The other room pays the bills. Eighty-three percent of the quarter is rockets, engines, microwave and space. Unmanned is 17%.
They printed $38 million of cleaned-up EBITDA and still lost money on an operating basis. Headline growth was 31%. Organic was 19%. The shopping helped the headline.
The new engine lit off yesterday morning. That is progress. That is not a production lot.
Street still clusters around $100. The targets written after the crash sit near $74. We land around $47.
The stock fell 64%. The expectations fell farther. At $49 you are still paying for the ramp.
Redwire got a seat. AeroVironment got the order. Kratos has a jet on a poster and a factory on a slide.
$KTOS $AVAV $RDW
A week off the AI circus, day 2.
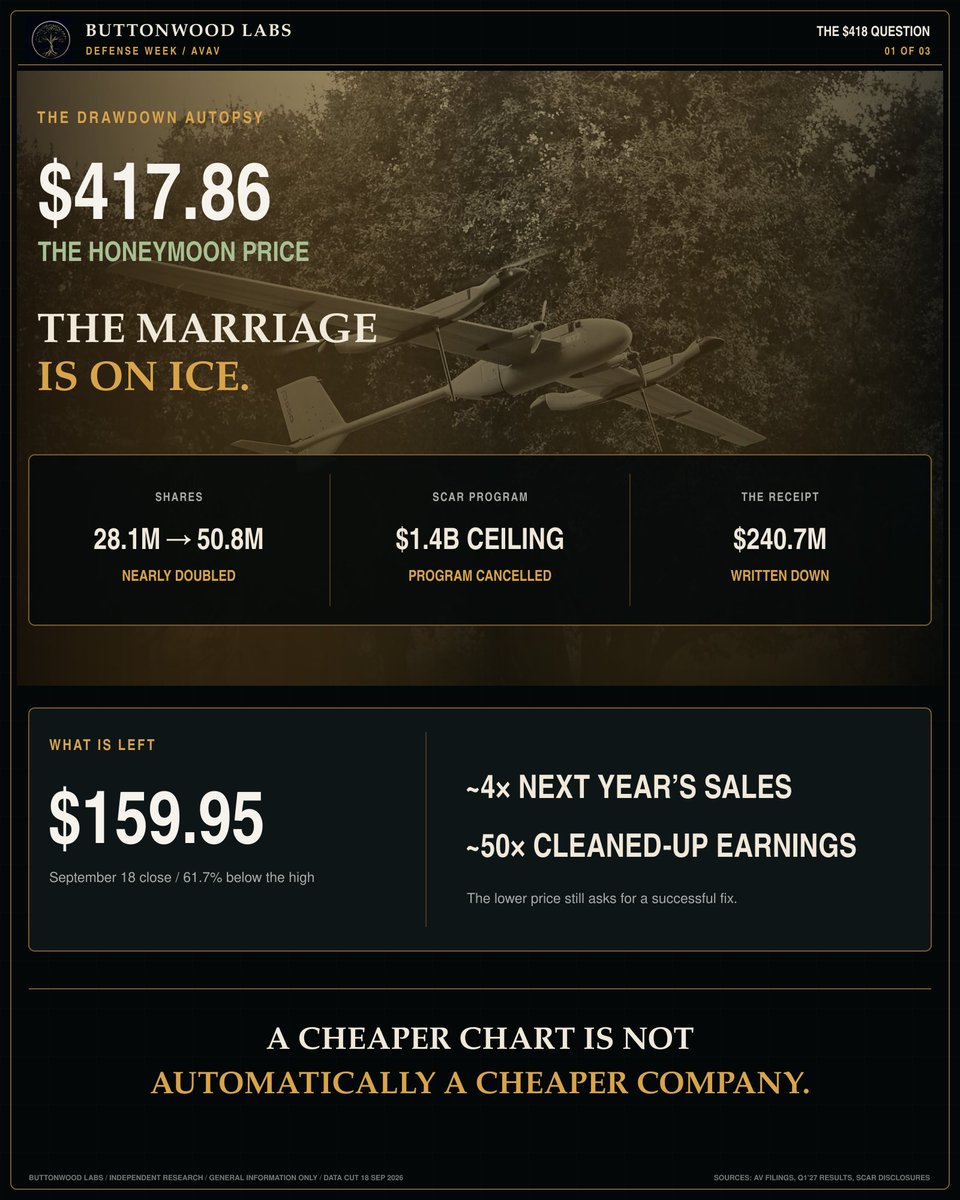
Yesterday was the quiet one. Today is the one that used to be $418.
AeroVironment paid for a second company and the stock priced the wedding. Share count nearly doubled. A $1.4 billion Space Force program (SCAR) got killed. They wrote down $241 million.
The original drone shop is still fine. Army even ordered 82 of the new ones for $117 million. The room they bought is not. It lost $9 million last quarter and ate the difference.
Street still has it around $220. That feels optimistic. I’m closer to $150–$160 until the new room stops losing money.
The chart looks like a sale. Four times next year’s sales and fifty times the cleaned-up earnings is not a sale.
Redwire got a seat. These guys got the order. Neither one is cheap just because it fell.
$AVAV $RDW
Taking a week off from the AI circus. The GPUs will still be there on Friday.
Some companies still make things that fly, and they’ve been standing in the corner while everyone fights about data centers.
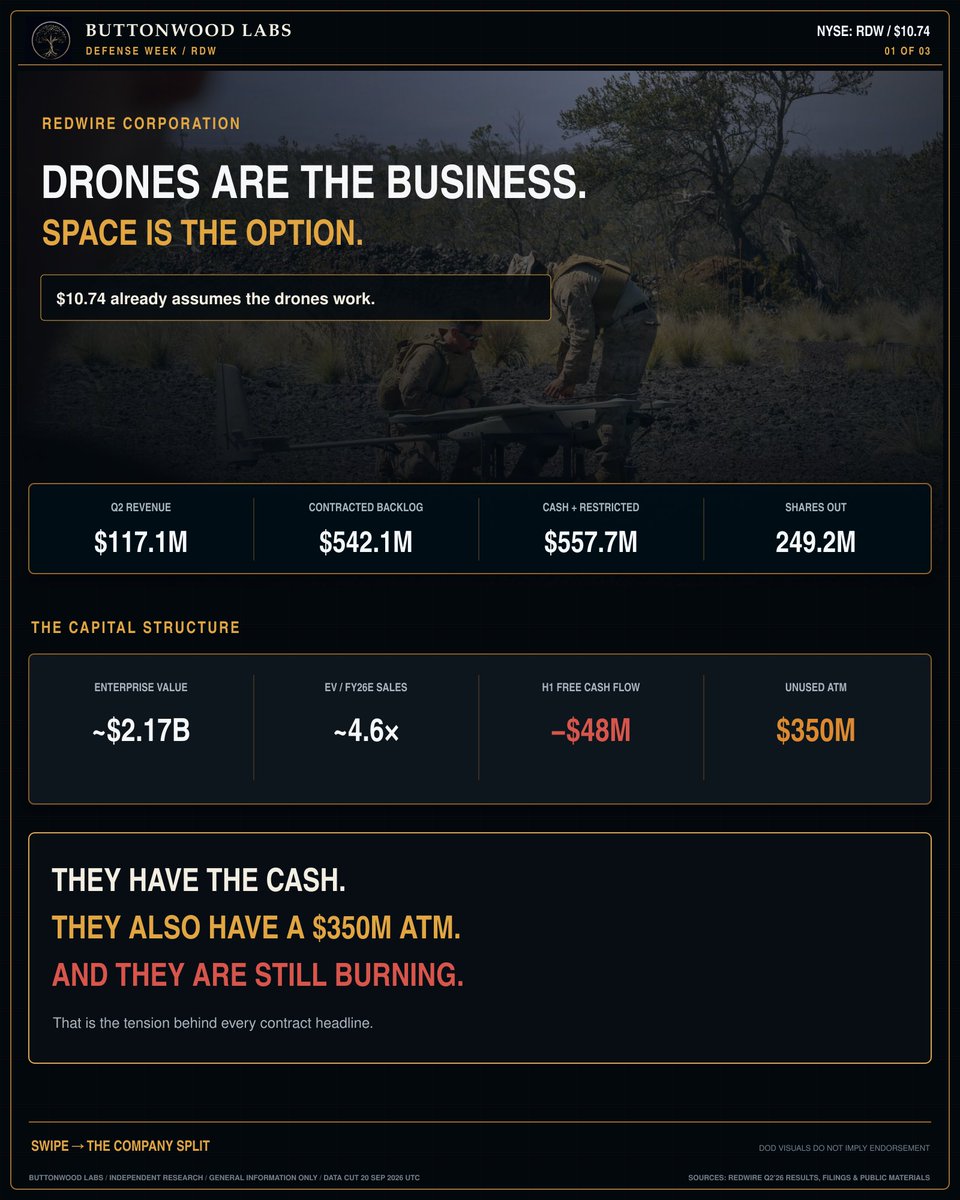
Redwire first. Three slides.
The drones are the company now. Space is the lottery ticket. They have half a billion in cash, a $350 million ATM, and they are still lighting money on fire.
At $10.74, the stock already pays for the good half. A year out, I land around $10.30.
That is not a bargain. That is me sitting on my hands.
Buy the proof, not the pipeline.
Defense Week has three more names. None of them come with a keynote.
$RDW #DefenseWeek #DefenseTech #SpaceStocks
Sources behind the card:
The Information — $517B tally
Nscale S-1
SpaceX S-1/A
Broadcom 8-K
Amazon 10-Q
Microsoft / NVIDIA — Nov 18, 2025
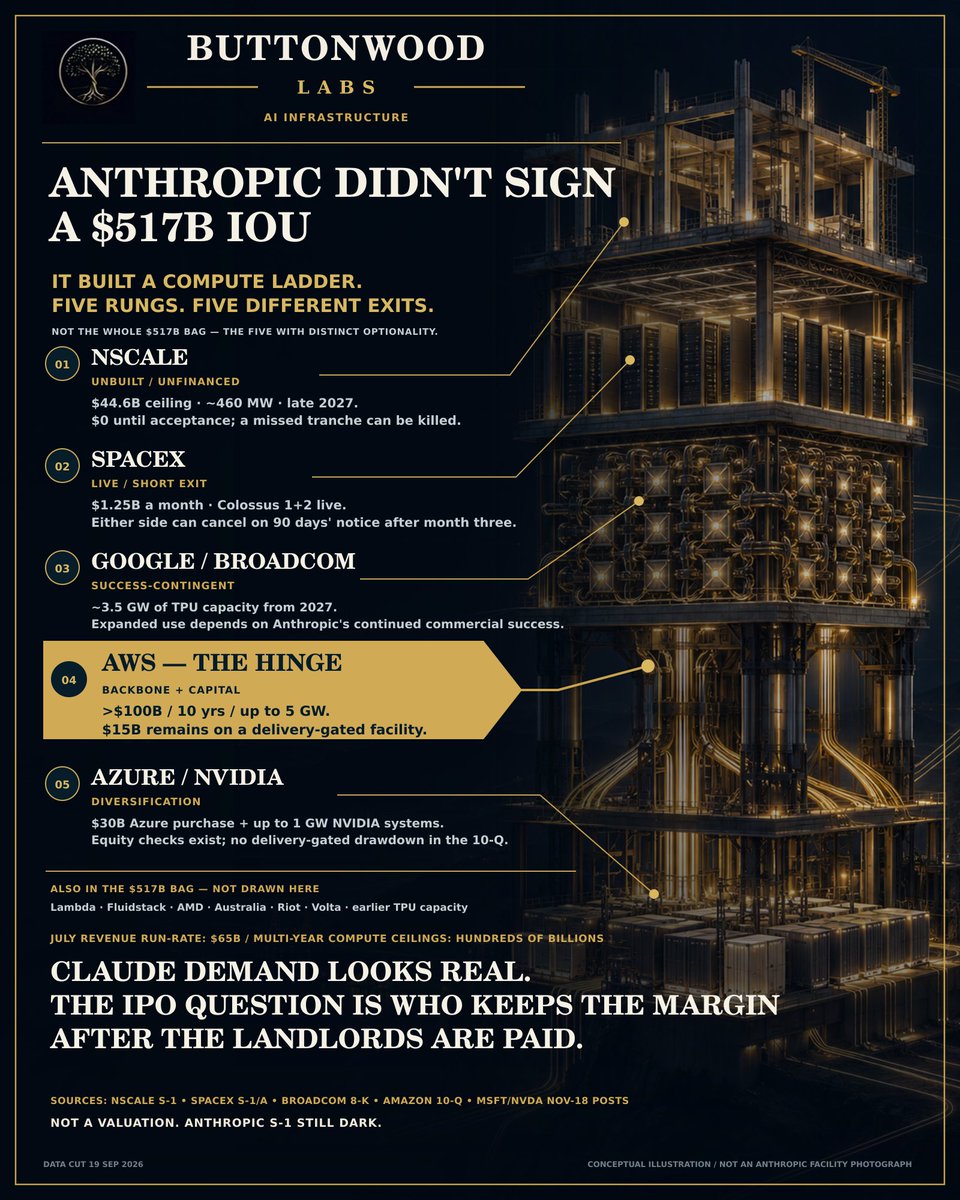
Not the whole bag. Lambda, Fluidstack, AMD, Australia, Riot, Volta, and earlier TPU capacity are in the $517B sum and not on the ladder.
Contract map, not a valuation. Anthropic’s S-1 is still dark. Data cut 19 Sep 2026.
The $517B Anthropic compute number is doing laps again.
I read the filings.
It is not a $517B bill. It is a prenup with five different in-laws.
Five contracts. Five exits. What stays dark until the S-1.
$AMZN $GOOGL $MSFT $NVDA $AVGO
Sources behind the card:
• The Information — $517B tally • Nscale S-1 • SpaceX S-1/A • Broadcom 8-K • Amazon 10-Q • Microsoft / NVIDIA — Nov 18, 2025
Not the whole bag. Lambda, Fluidstack, AMD, Australia, Riot, Volta, and earlier TPU capacity are in the $517B sum and not on the ladder.
Contract map, not a valuation. Anthropic’s S-1 is still dark. Data cut 19 Sep 2026.
V2 bandwidth is not the fight.
T-Mobile: satellite was 0.0002% of traffic. Carriers are filing who decides when the phone leaves the tower.
They lose if SpaceX sells the plan or the OS brokers it. Big Three JV still no 8-K.
@TMobile@ATT@Verizon@Starlink@AST_SpaceMobile https://t.co/9OTJRTL9ks
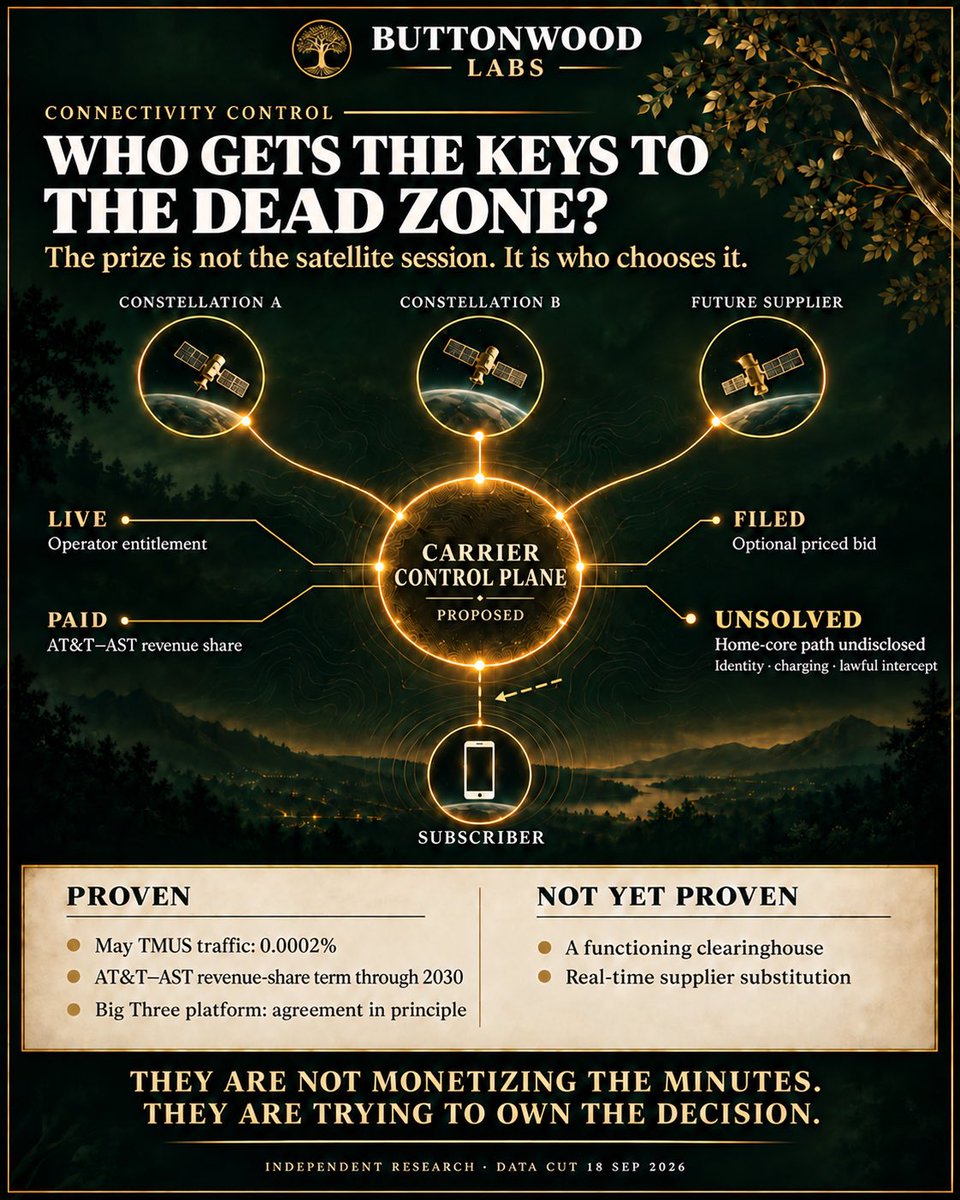
Satellite was 0.0002% of T-Mobile traffic in May. Not a typo. That is the point.
Carriers are not fighting over today’s minutes. They are trying to own the decision when coverage fails.
@FrontierLedger Exactly. Distribution can expand while pricing power compresses.
The hinge is whether the session stays in the home core. 81790 sketches selection and price. It does not say who charges.
Satellite was 0.0002% of T-Mobile traffic in May. Not a typo. That is the point.
Carriers are not fighting over today’s minutes. They are trying to own the decision when coverage fails.
Different layer than the array-and-thermal patents. US20260281790A1 is the carrier-side docket: who keeps identity, billing, and supplier choice when terrestrial coverage fails.
@FrontierLedger
Two ways this fails: SpaceX sells the plan, or the OS becomes the broker.
The prize is not the session. It is who chooses it. Trying is the story; succeeding takes a later 8-K.
JV closes: $ASTS distributed wholesaler—or price-taker?
$TMUS $T $VZ $SPCX #DirectToCell#D2D#NTN