I’m here for the commodities Bull Market run of our lifetime. $40T in US debt, $ debasement, need for clean base load power: silver +uranium. Real assets vs QQQ
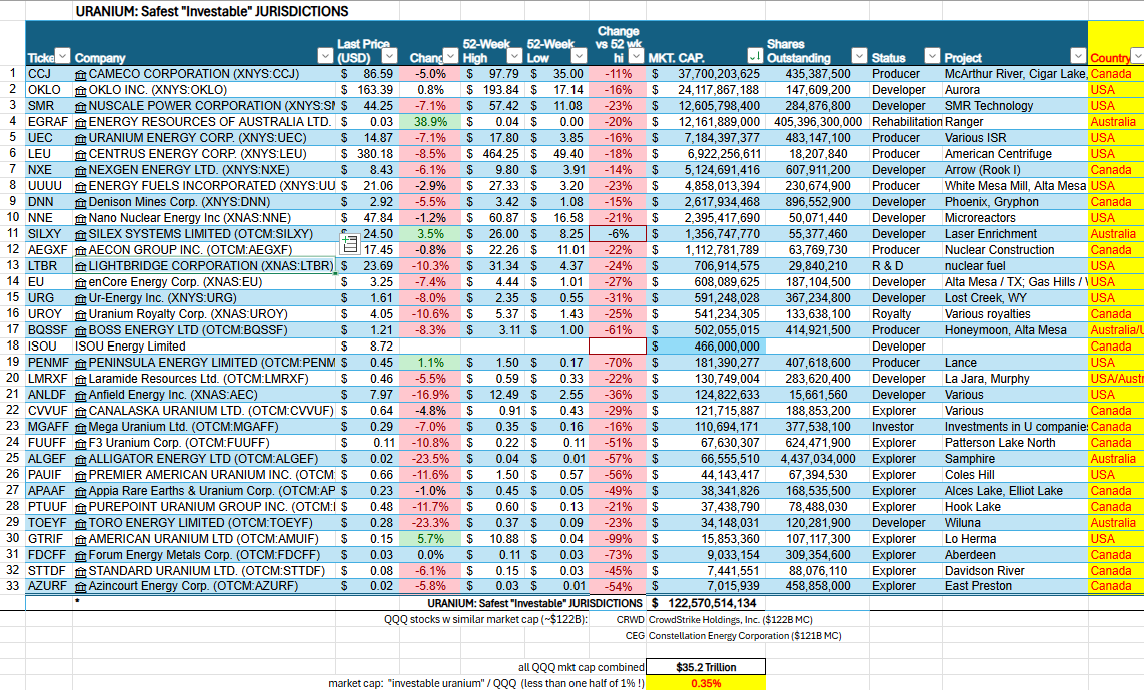
It's been a minute. #U308 stocks' MC was ~$18B in '21. Total '25 "investable #uranium " now ~$122B in mkt cap (Same MC as $CRWD or $CEG !) QQQ's MC: $35 Trillion. Wud u rather own 1 QQQ stock or hold 100% of best 🇺🇸🇨🇦🇦🇺 uranium reserves? $DNN $NXE $UUUU $APPAF $UEC $BQSSF $PALAF
B/c it would increase deficits notably at 125% debt/GDP which increases inflation now, while also lowering receipts, which then also promises higher future deficits (& inflation).
It would also strengthen USD, which would force foreigners short USD to sell USTs to raise USDs
WHAT IF the biggest bubble of our lifetime isn't crypto?
Not AI stocks.
Not real estate.
What if it's the one asset every pension fund, every retiree, every "safe" portfolio is loaded with?
Bonds.
200 years of rate cycles say the same thing:
Every peak lasts 56–67 years.
The 1981 top was 14% yields.
The 2020 bottom was 0%.
39 years of falling rates just ended.
What if we're now at the start of the next 50-year cycle — upward?
Most investors have never managed money in a rising rate world.
Their entire career happened inside the bull.
The unwind has barely started.
And no one is talking about it.
Big news! $DNN is launching. Name a more significant, new/ friendly jurisdiction #uranium mine w huge resources coming on line in next 5 yrs ?! You can’t. $NXE is 5+ years later. Both 🇨🇦 and incredibly important for western security. Baseload power > renewable. 🙌🏽🥇
Denison Announces Final Investment Decision for the Phoenix In-Situ Recovery Uranium Mine and Plans to Start Construction in March 2026.
Read the full press release here: https://t.co/VSfUsISoRB
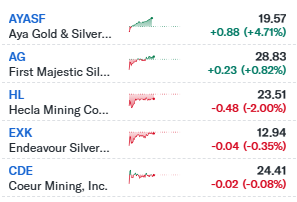
#1 juiciest #silver miner by far is $AYASF. A unicorn in the space. I’ve owned it since 2020 and added all the way up including yesterday, fortuitous timing given Boumadine’s expansion w ++ new drill results. It won’t lag forever. Best management. A producer and developer!
Gold is down a bit today, Silver is up a little bit. And my favorite silver mining stock is up significantly. Why?
1) Aya (AYASF) is not mining in Mexico
2) They just released more drill results indicating their next mine, Boumadine, is much bigger than previously indicated.
People have been asking me why I think Aya is the best pick of the silver mining stocks, here is my summery. Do your own reading also.
Aya currently produces (at Zgounder mine) 6 million oz of silver per year (est for 2026) at a cost of $21 per oz. At current silver prices above $85 per oz, they have operating cash flow of $300+ million per year. Free cash flow is likely around $250 million (after tax and royalties).
Their next mine, Boumadine, will be completed in 2030.
Boumadine will produce 37 million oz of Silver equivalent (AgEq). It will be a combo of gold, silver and other metals, but calculated in silver equiv, it will be 6x bigger than their first mine.
So even if gold and silver stay at current prices, AYASF is going to have a 6x (or more) increase in production. At current silver prices, Aya can build Boumadine with zero stock dilution. Their first mine, Zgounder producing 6 million oz per year, will be able to fund their second mine Boumadine.
The Boumadine projection of 37 million oz per year is based on 8,000 tpd of ore processed. If the resource is larger, and currently drill results indicate it potentially is, then they will build it for 15,000 tpd. In that scenario, Boumadine would produce over 60 million oz Silver (AgEq) per year.
This is a massive tier 1 mine and the major gold/silver companies will want to buyout Aya eventually.
Paladin is pleased to announce that it has received approval from the Government of Saskatchewan for its Environmental Impact Statement (EIS) for development of its Patterson Lake South (PLS) Project, located in the Athabasca Basin, Canada. The Environmental Assessment approval is an important regulatory milestone for the PLS Project and a prerequisite for permits and licences issued by provincial and federal authorities leading to construction and operation.
Saskatchewan Premier Scott Moe said: “We welcome the continuing focus by Paladin in progressing the development of the PLS Project in a sustainable and safe way to benefit the people and communities of Saskatchewan. Our province continues to be a leader in all aspects of uranium production and the Environmental Approval will assist this project to move forward and further enhance our world-class energy sector.”
Read further details and comments from Saskatchewan’s Minister of Environment Darlene Rowden and Paladin MD and CEO Paul Hemburrow here:
https://t.co/0cZ1fpm7mL
Denison Receives Final Regulatory Approval to Construct the Phoenix ISR Uranium Mine.
David Cates, President and CEO of Denison commented, "The Commission decision to approve the EA and issue the Licence represents a landmark achievement for Denison, as well as our staff, shareholders, Indigenous partners, and other stakeholders in the Project. We thank the Commission and CNSC staff for promptly delivering the positive results of the recently completed public hearing and extensive federal regulatory review process. Denison has successfully demonstrated to the Commission's satisfaction that Phoenix can be built in a manner that meets Canada's stringent standards.
Phoenix is the first uranium mine in Canada to be approved for ISR mining and is the first large-scale Canadian uranium mine approved for construction in more than 20 years. It is a nation building project that reflects the best of Canadian ingenuity and determination. Owing to the use of the ISR mining method, Phoenix has the potential to generate strong economics while also achieving a superior standard of sustainability when compared to conventional mining methods. With an approximately 2-year construction timeline, the timing of this approval means that the Project remains on track for first production by mid-2028."
Read the full press release here: https://t.co/x3shXHgO7d
We're at the part of the Ponzi scheme where the guy running it starts sweating.
The US has $38 trillion in debt. It grows by $6 billion per day—not per year, per day. The US added $1 trillion in debt in just 71 days last year.
Here's the problem: The US paid $1.2 trillion in interest on that debt in 2025. That's more than defense spending.
So how do you fix it?
1) Raise taxes? The wealthy leave (see: Britain)
2) Cut spending? Political suicide
3) Default? Game over
There's only one path:
Print Money.
Devalue the debt by making dollars worth less.
Ray Dalio: "If you devalue money, you devalue debt."
Translation: Your savings, salary, and retirement get quietly confiscated to pay for government debt.
The S&P was up 18% last year. Against gold? Down 28%. That 46% gap is the real inflation rate they're not telling you.
Currency devaluation isn't coming—it's official policy.
Precious metals miners were telling a story last week.
They were nowhere near as frenetic as gold and silver in those final days, so Friday’s move was probably the most interesting price action I’ve seen since I first sat on a trading desk in 1994 🙂
For context: at Hinde Capital, Mark Mahaffey and I ran the Hinde Gold Fund (2007–2015), before I went on to set up Glint Pay and then others...
I don’t run professional money anymore. But despite now running a healthtech business, my life is still deeply embedded in trying to understand the system we all live in.
So these aren’t recommendations, just observations from someone managing his own capital, both to grow it and to provide for family over the long term.
What stood out was this...
1. Gold and silver were hit hard, yet miners, even some explorers, actually held up better.
2. I honestly can’t recall many times (if any) when the metals were down roughly 2x as much as the miners.
Normally, it’s the other way round.
3. That tells you how hard it is for the market to value miners when the underlying is going vertical one minute and chaotic the next.
My read, shaped by too many cycles to count...
1. Miners need the metals to settle before operational leverage really shows up.
2. That probably pushes meaningful outperformance into Q3 / Q4.
3. Between now and then, I’d expect miners to chop around with the metals...sometimes better, probably not worse...unless gold and silver really break down (say $4,400 and $70).
What I’ve been doing...
1. Rotating metal exposure into a basket of miners, from big caps down into juniors.
2. Some I sold early, some I sold really well (ooh, look at me), but when a market rises 240% in months, you have to accept it can just as easily crater 40 to 50%.
3. These are long-only ownership markets. When leverage builds, and trend-followers pile in higher and higher...CTAs, Johnny come-latelies...the risk of a 1 to 2 day rout becomes an order of magnitude faster than the climb.
That asymmetry always catches people out, because it's structural.
(I’ll post separately on why precious metals behave this way.)
Zooming out, what still matters to me...
1. If the global monetary order is genuinely shifting, a regime change implies discontinuity.
2. Discontinuities don’t resolve smoothly. They tend to produce longer ascents and sharper verticals than most people can realistically hold through.
3. At some point, there will be a rotation into another asset (class) with value, not just momentum.
4. That time isn’t now, though there will be moments to rotate within the sector.
5. Right now, the breakdown in fiat confidence means gold is still widely misunderstood. It remains underowned and, in my view, undervalued for this kind of scenario.
6. Nothing fundamental has changed for me since 2005, when the BW2 system was already fully in force.
So if the Great Reset thesis is right, then...
1. You still need to own a zero-default-risk asset. That’s gold.
2 And miners, though they are a different animal. Be aware thoug, even in Tier-1 jurisdictions, they carry political risk. Windfall taxes may be a long way off, but they’re never zero.
3. That distinction matters, as for the record, I have experienced enough quality assets being expropriated in supposedly “safe” places to know it can happen even in Tier-1 designated countries where isolationism is rife.
For me:
1. The sweet spot is producers through to explorers funded, moving projects forward, steadily de-risking.
2. I’ve also taken positions in a few nascent, cash-light juniors where the resource potential is real but pricing still reflects a once-in-a-generation capital drought.
3. And, in time, the majors will come knocking.
I will write about a few of them in the next few weeks, caveat emptor! And hope this is useful...
@CaptainOrlov@ttmygh@LukeGromen@ArsenalStu
⏰ THIS IS INSANE.
#SILVER#MINERS are at an all-time bottom relative to #Silver.
We are at the same relative levels as:
• The 2016 bottom
• The COVID crash bottom in 2020
• Even lower than the weakest point of 2025
#RSI is also at its lowest level since the 2020 COVID bottom.
Since #SILJ started trading 13 years ago, buying #SILJ (silver junior miners) in this zone has historically delivered life-changing gains.
I never thought we would revisit the “LOAD THE FUCKING TRUCK ZONE”, but here we are.
Right now, #SILJ is cheaper today than it was before it ran +276% over the last 12 months, relative to #Silver.
What are investors waiting for?
This is the window.
THE window.
Possibly the last window for anyone still not exposed to the sector to get in.
RT and get the word out.
@Michael_Khouw Timely…of more interest: the entire “investable universe” of top 3 jurisdiction 🇺🇸 🇨🇦 🇦🇺 nuclear U308 firms/miners is ~same mkt cap as $SBUX. ~ $102B last wk. Rather have a latte or 100% clean baseload power? Hard assets > QQQ. $DNN $UUUU $NXE $UEC Flows moving #silver too.
In other words… you haven’t missed the train. it’s early- this sector has yet to be noticed by mainstream. #AI#DataCenters + world’s need for much more clean, baseload power is changing that rapidly. Real assets, hard #Commodities, metals > fully valued $QQQ. @Convertbond
It's been a minute. #U308 stocks' MC was ~$18B in '21. Total '25 "investable #uranium " now ~$122B in mkt cap (Same MC as $CRWD or $CEG !) QQQ's MC: $35 Trillion. Wud u rather own 1 QQQ stock or hold 100% of best 🇺🇸🇨🇦🇦🇺 uranium reserves? $DNN $NXE $UUUU $APPAF $UEC $BQSSF $PALAF
Reconcile this, please: Oatly $OTLY went public and is now valued @ $13B. This oat milk co. is now equal to the approx COMBINED value of 6 of the world’s most important #U308 companies: $CCJ $NXE $DNN $UUUU $PALAF $BQSSF ... 🙏 @trader_ferg@quakes99 what’s more critical? 🤔
@jtourzan $DNN Denison …you cannot compete w their world class resource and grades (along w $NXE) + favorable 🇨🇦 jurisdiction. It is also a Reddit favorite for more future gamma squeezes as we saw mid Feb. Other near producers: $PALAF $BQSSF $GLATF. $APAAF for world class #REE grades