For those that may have missed my earlier posts on humanoid bots, here's a compendium of some relevant posts... a 23 part thread...
1) A deflation machine
2) An economic reboot
3) Humanoid bot motto
4) Bot napkin math at massive scale
5) Bot market vs EV market
6) Humanoid bots in warfare
7) A Zero-trillion dollar market
8) Bot deployments - fast or flow - does it matter?
9) Thoughts on humanoid bot deployment
10) How big could the market become?
11) Scott Walter defines useful work
12) Humanoid bots will address major labor issues
13) The advantages of humanoid bots
14) What could capable humanoid robots do for Wal-Mart?
15) Tesla bot thought experiment
16) Tax the bots!?
17) What could Tesla's Optimus bot be worth to Tesla working in their own operations?
18) A call option on the survival a business.
19) If you could buy a machine that could save you $615,000 over ten years, what would you pay today?
20) Bots for as little as $40 per day
21) Why should we bother making a humanoid robot?
22) A paradigm shift in computing platforms
23) Robots as a Service
24) Links to a few videos discussing bots...
Are Big Companies Taking Too Much Risk?
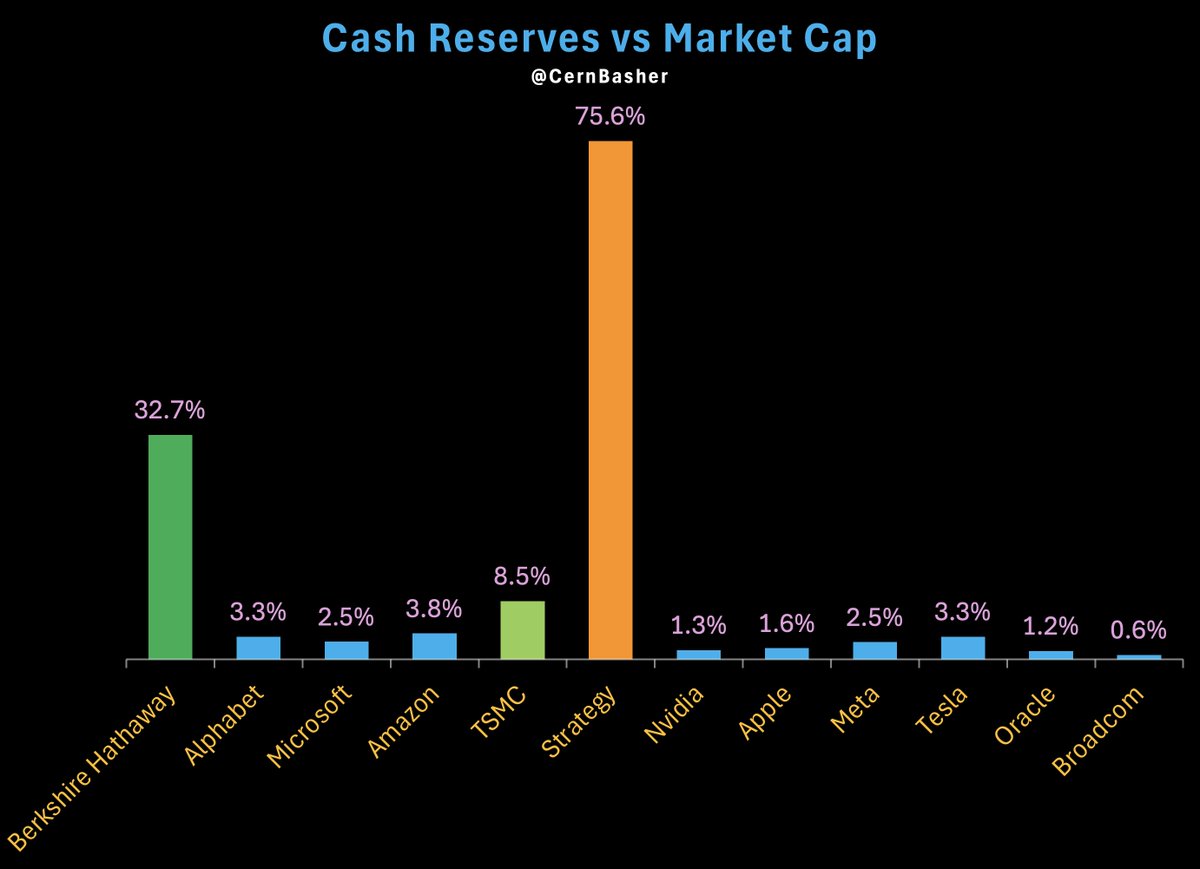
Many of the world’s largest companies sit on surprisingly small cash piles relative to their towering market values.
That makes their valuations heavily dependent on continuously compounding profits. While that’s often a reasonable bet for these elite franchises, it can also leave them riskier than they need to be.
The table below shows that Alphabet's cash hoard - at $95 billion - only represents 3.3% of the value of the company.
For Microsoft - also with $95 billion in cash and short-term investments - it only represents 2.5% of the value of the company.
For Nvidia - with $57 billion in cash and short-term investments - it only represents 1.3% of the value of the company.
Three companies stand out on this list:
1) TSMC - the Taiwanese semiconductor maker's cash and short-term investments account for 8.5% of its market value --> this is more than twice that of any of its peer big cap tech companies.
2) Berkshire Hathaway - Buffett has long preferred optionality over distribution - so he carries $334 billion in cash. No dividend, opportunistic buybacks, and dry powder for dislocations.
3) Strategy: Michael Saylor's company invests all (~99%) of its capital in Bitcoin. Strategy's capital reserve, at $73 billion, is now the fifth largest (among US companies), even though the market value of Strategy is less than $100 billion.
Why thin cash can be a hidden risk
Platform shifts: Big transitions (AI/AGI/ASI, energy, compute, supply chain re-wiring) reward those who can spend fast without tapping fickle markets.
Downturn fragility: If growth stalls or margins compress, lean reserves can force hurried debt or equity raises at bad prices.
Credit market dependence: Revolvers and commercial paper are great - until they’re not. Liquidity can vanish precisely when it’s needed.
On the other hand, capital efficiency matters, so idle cash drags returns; high-ROIC firms prefer reinvestment and buybacks.
How Bitcoin changes the equation
Once you allow Bitcoin into treasury, “idle cash drag” stops being binary (cash = dead money, deploy = good).
The corporate treasury turns into a return-seeking portfolio with optionality - and that reshapes the reinvest vs. buyback calculus.
Cash/T-bills offer low nominal yield, but near-zero real returns over cycles. They provide great liquidity, but no upside.
Bitcoin is volatile, but historically a massive positive drift and global 24/7 liquidity. It converts reserves from a cost center into a potential strategic asset that can accrete without committing to irreversible uses of capital.
Optionality vs. stock buybacks: Buybacks are permanent - great when your stock is clearly cheap, but less great when uncertainty is high.
Bitcoin reserves preserve option value - so companies can later fund R&D/M&A/hiring or do buybacks when they’re more attractive. You keep the “gunpowder” and give it upside.
A prediction: Warren Buffett was right to hoard capital, but he used a combination of cash and equities. Strategy is showing the corporate world the way by investing in Bitcoin.
Eventually the norm in the corporate world will be hold far more capital in reserve (invested mostly in Bitcoin) and they will reduce their reliance on stock buybacks, using them more opportunistically on big stock price drops.
If Elon meets the various compensation plan milestones, what might your shares be worth?
Note: Not investment advice. Don't count your chickens before they hatch. Tesla price calculations are from the post below which factor in dilution.
Tesla's FSD gives mobility to all...
I met Chris at a Supercharger at Buc-ee's in Alabama last fall.
He relies on the kindness of strangers to plug (and unplug) the charger into his car. Sometimes he's waiting a while for someone to come along. Every now and then it's a call to the police to help him out.
None of us can know the challenges that Chris faces in his daily life, but Tesla's FSD gives him freedom that every quadriplegic should have.
Chris should be an official ambassador for Tesla.
Tesla: How many shares do you need to own?
Let's say that Elon's new compensation plan passes and he's motivated to grow Tesla again, how many shares of TSLA do you need to own to reach your goals (assuming Elon meets all the targets)?
Regarding Elon's motivation - I'm kidding - Elon has always been motivated and he's been laying the ground work for future growth for the last several years.
The table below shows how many shares you need to own if you want to have $1 million, $5 million, $10 million, $25 million, $50 million or $100 million in Tesla stock at all the various market cap tranches and the $400 billion EBITDA target.
Goal: $1 million
Today: In order to have $1 million in Tesla stock today you need to own 2,857 shares.
At $8.5 trillion: If Elon is able to reach the market capitalization milestone of $8.5 trillion, you'd need just 472 shares to be a millionaire. Those shares would cost you ~$165,200 today.
At $400 billion EBITDA: If Elon is able to reach the EBITDA milestone of $400 billion (assuming the market applies a 40 multiple to that --> so the market cap would be $16 trillion), you'd need only 251 shares to be a millionaire. Those shares would cost you ~$87,850 today.
Goal: $10 million
Today: In order to have $10 million in Tesla stock today you need to own 28,571 shares.
At $8.5 trillion: If Elon is able to reach the market capitalization milestone of $8.5 trillion, you'd need 4,723 shares to have ten million. Those shares would cost you ~$1.652 million today.
At $400 billion EBITDA: If Elon is able to reach the EBITDA milestone of $400 billion (assuming the market applies a 40 multiple to that --> so the market cap would be $16 trillion), you'd need only 2,509 shares to have ten million. Those shares would cost you ~$878,150 today.
Goal: $100 million
Today: In order to have $100 million in Tesla stock today you need to own 285,714 shares.
At $8.5 trillion: If Elon is able to reach the market capitalization milestone of $8.5 trillion, you'd need 47,235 shares to have $100 million. Those shares would cost you ~$16.5 million today.
At $400 billion EBITDA: If Elon is able to reach the EBITDA milestone of $400 billion (assuming the market applies a 40 multiple to that --> so the market cap would be $16 trillion), you'd need 25,093 shares to have $100 million. Those shares would cost you ~$8.78 million today.
Note: The above calculations assume maximum share dilution from Elon's comp plan, the 208 million shares in the Special Share Reserve (to make him whole on the 2018 comp plan) and the additional 60 million shares for employee stock option compensation.
Cern's Comp Plan vs Elon's Comp Plan
Back in May I designed a new compensation plan for Elon (see post below) - What did I get right? What did I get wrong? How close was I?
I used ChatGPT to grade my work...
"Here’s a tight compare of your proposal vs. Tesla’s actual 2025 CEO Performance Award (Proposal Four).
What you got right
10-year, pay-for-performance, dual trigger. Both plans require hitting market-cap milestones and operational milestones over a 10-year window.
12 tranches at ~1% each. You suggested 12 equal tranches ≈1% per tranche; Tesla’s award is 12 tranches × 35,311,992 shares = 423,743,904 shares (12%).
Market-cap measured on sustained averages. You referenced 30-day/6-month trailing—Tesla uses both (and a 1-year average only for a special “deemed achievement” case).
5-year holding concept. You proposed a 5-year hold; Tesla has a 5-year hold, too (key nuance below).
Service/role condition & corporate-action adjustments. You required continuing leadership and fairness adjustments for M&A/spin-offs; Tesla requires Eligible Service (CEO or board-approved exec role over product/ops) and includes adjustments for significant transactions.
Where it diverges
Security type. You used stock options; Tesla uses performance-based restricted stock with a built-in Offset (economically strike-like) taken at vest (or payable in cash). This also gives Elon voting rights on Earned (but unvested) shares.
Tranche size math. You based 1% on ~3.2B shares (≈32M/tranche; 384M total). Tesla pegs 1% to an “Adjusted Share Count” (shares outstanding as of Aug 29, 2025 + 2018 award – 2025 interim award), yielding 35,311,992 per tranche; 423,743,904 total.
Market-cap ladder. Yours tops out at $5T with ~$333B steps. Tesla starts at $2T and runs to $8.5T; steps are $500B each, with the last two at +$1T.
Operational mix. You used 8 Revenue + 8 Adj. EBITDA (hit 12 of 16). Tesla uses 12 total: 4 product goals (20M vehicles delivered; 10M active FSD subs; 1M Bots delivered; 1M robotaxis in operation) + 8 Adj. EBITDA targets ($50B → $400B, with the last three each $400B TTM). No revenue targets in Tesla’s plan.
Holding clock & vesting timing. You place the 5-yr hold after option exercise. Tesla’s 5-yr clock starts when a tranche becomes Earned, and vesting occurs at 7.5 years (if earned by year 5) or at 10 years (if earned after year 5), subject to service. You must satisfy both the hold and vest to transfer for value.
Succession gating. Tesla requires Board-approved CEO Succession Framework participation to unlock tranches 11 & 12—not in your draft.
Overall: how close?
Conceptually strong and directionally close (~7/10). You nailed the framework (10-yr, dual trigger, ~1% × 12, sustained market-cap tests, long holding/retention). The biggest gaps are form (options vs. restricted stock + Offset), magnitude (to $8.5T, not $5T), and ops mix (product goals replace revenue).
If you swap in Tesla’s security type and milestone set—plus the succession gate and Adjusted Share Count—your plan would read very close to the real thing."
Deep Dive on Tesla’s New $8.5 Trillion Plan
Every time Herbert does a video with me the word "trillion" seems to find its way into the title!
Link to full video below.
Also, check out Darryn's post on getting to one million Robotaxis in service...
Elon's Comp Plan: US Government could make a Trillion too.
Wild Spreadsheet Analysis: Elon could make one trillion dollars and so could the Federal government.
When it comes to Elon's 2025 Compensation Plan, let's count the five ways in which a trillion dollars could be involved...
1) The Value of the Compensation: If the stock price upon vesting (and payment) is $2,500 then Elon receives one trillion dollars in compensation ($2,500 x 423.7 million shares).
2) Income Realized: If the stock price upon vesting is $3,000 then Elon receives one trillion dollars in taxable income ($3,000 - $334.09 Offset Amount x 423.7 million shares).
3) Federal Taxes: If the stock price upon vesting is $6,000 then Elon would owe almost one trillion dollars in Federal taxes ($2.4 billion in taxable income x 39.35%).
By the way, the record for the most taxes ever paid in a single year was Elon for 2021 --> a mere $11 billion.
What would the government do with a one trillion dollar tax payment?
I bet California will be sorry for driving him away. Texas has no state income tax.
4) Total Cost to Elon: If Elon wishes to keep all of the shares he's been granted, he will have to come up with enough money to pay the Federal Taxes and cover the Offset Amount. If the stock price upon vesting (and payment) is $5,500 then Elon would need to borrow about one trillion dollars!
How many banks would participate in that deal?
5) Net to Elon: If Elon only wished to keep one trillion dollars (after-tax and after paying the offset amount), then the stock price upon vesting would need to be $4,500.
By the way, in this "net shares" scenario the higher the stock price goes, the more shares Elon would be able to keep: 50.5% at a stock price of $2,000 and up to 57.3% at a stock price of $6,000 --> so Elon personally has every incentive to drive the stock price as high as possible in order to keep as many shares as possible (assuming he decides against borrowing $800+ billion).
What is the Offset Amount?
The Offset Amount is a built-in, fixed-dollar “purchase price” attached to Elon’s 2025 award: for any shares that ultimately vest, he must effectively pay $334.09 per share (the grant-date fair value on Sept 3, 2025) multiplied by the number of shares vesting.
Tesla satisfies this either by automatically netting out enough vested shares (rounded up to the nearest whole share) to equal that dollar amount, or - if Elon chooses - he can pay the Offset in cash by the applicable date so no shares are netted away.
There are two flavors: the Initial Offset Amount applies to tranches earned by year 5 and due at the 7.5-year vest date; the Final Offset Amount applies to tranches earned after year 5 and due at the 10-year vest date.
This Offset is separate from taxes (which are handled at vest, either via share netting or cash), but you can think of it like a strike price for a restricted-stock award: it prevents “free” shares by requiring $334.09/share to be settled when the stock actually vests.
My conclusion: Elon will be the world's first trillionaire and the US Federal government will make hundreds of billions, if not a trillion, as well.
Summary of 2018 Performance Award - Back Testing Analysis
Tesla's Board examined the performance objectives included in Tesla’s 2018 CEO Performance Award across a broad group of CEOs at large cap companies.
No other company came close!
The study...
"Infinite Equity assessed the performance objectives under Tesla’s 2018 CEO Performance Award, a 100% at-risk, performance-based compensation program designed with ambitious growth targets in market cap and financial metrics. Musk impressively completed all 12 tranches in less than five years, significantly faster than the allotted 10-year performance period. A comparative analysis of CEO performance at 113 large-cap companies (≥$50B market cap as of 2018) highlighted the award’s rigor:
• 79% failed to achieve even one tranche,
• 13% achieved just a single tranche,
• 7% achieved two tranches; and
• Only one company (NVIDIA) achieved three tranches.
These findings underscore the rigorous performance demands embedded in Tesla’s 2018 CEO Performance.
Methodology and Process
We used S&P’s Capital IQ Pro data feed to compile the financial and stock price data (stock price, market cap, revenue, and EBITDA) for the 113 comparator companies in the analysis (“Comparator Companies”). S&P Capital IQ Pro is a widely utilized service that offers access to data on over 60,000 public companies, including 47,000 active companies with current financials.
The Comparator Companies consisted of members of the S&P 500 Index (as of December 31, 2022) with a market cap of at least $50 billion as of January 21, 2018. We then determined the number of tranches that each Comparator Company would have achieved over the Performance Measurement Period by examining market cap, revenue, and EBITDA growth from 2018 through the end of 2022.
The number of Market Cap goals achieved by each of the Comparator Companies was based on the Market Growth Measurement over the Performance Measurement Period (consistent with the market cap goals in Tesla’s 2018 CEO Performance Award). We normalized hurdles based on the Baseline Market Cap of each Comparator Company (i.e., the % growth required the same).
Tesla’s Baseline Market Cap was approximately $59B as of the Grant Date. The market cap goal of $100B is approximately 1.7x Tesla’s Baseline Market Cap. If a Comparator Company had a Baseline Market Cap of $75B, the initial tranche used to measure performance was assumed to be 1.7 x $75B = $127.5B.
The number of EBITDA goals achieved by each of the Comparator Companies was based on the Maximum EBITDA over the Performance Measurement Period (consistent with the adjusted EBITDA goals in Tesla’s 2018 CEO Performance Award). Because adjusted EBITDA values were not easily obtainable for all Comparator Companies, EBITDA values were used as a reasonable proxy. For Comparator Companies that did not disclose EBITDA values, Net Income was used. In all cases, we measured growth over the Performance Measurement Period. A similar normalization was applied to EBITDA goals (starting with a Comparator Company’s Baseline EBITDA or Baseline Net Income, as applicable) as illustrated above for Market Cap goals.
The number of revenue goals achieved by each of the Comparator Companies was based on the Maximum Revenue over the Performance Measurement Period (consistent with the revenue goals in Tesla’s 2018 CEO Performance Award). In all cases, we measured growth over the Performance Measurement Period. A similar normalization was applied to revenue goals (starting with a Comparator Company’s Baseline Revenue) as illustrated above for market cap goals.
The total number of tranches earned by each of the Comparator Companies is equal to the lesser of (i) the number of market cap goals achieved and (ii) the sum of the number of EBITDA and revenue goals achieved. For example, if four market cap goals were achieved and a combined total of seven revenue and EBITDA goals were achieved, a total of four tranches would be earned.
Source: https://t.co/4sbr1TWyVi - page A-A-1