#Ratnaveer Precision
The company is trying to build a new growth engine beyond its traditional business.
I listened to the conversation with Vijay Sanghvi, Founder & MD, and noted down a few points that I found interesting.
Key takeaways from the interview👇
Worth listening to the full interview for the management’s perspective.👇
https://t.co/fFPIcoqKrw
#Ratnaveer #CCL #PCB #Stocks
#ParagMilk
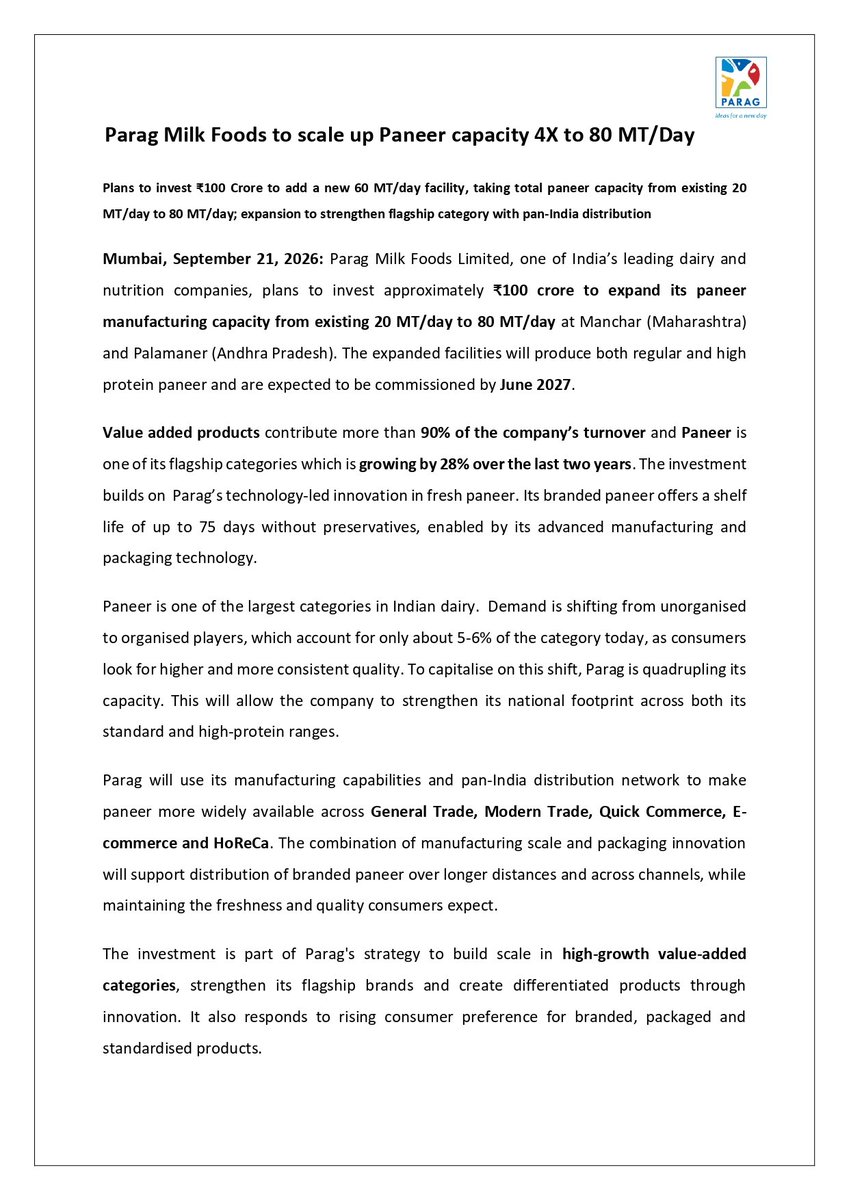
Parag Milk Foods – Paneer expansion
A few things that caught my eye:
• Paneer capacity to rise 4X: 20 → 80 MT/day
• ₹100 Cr investment planned
• Existing capacity already near full utilisation
• Paneer business grew 28% in 2 years
• New capacity expected by June 2027
• Organised paneer still only 5–6% of the category.
P.S. - The dairy space is going through a structural Demand change & there is no evident decline in demand especially in VAP category despite recent price hikes.
Hence it will be worth tracking this space in coming couple of qtrs especially on the margin front as companies are able to pass on the price hike to customers without any evident demand decline.
#SudeepPharma
The key takeaway from Q1 is that demand is not the constraint anymore but capacity & execution will be the key.
PFN growing, phosphate demand is ahead of capacity and bisglycinate is scaling rapidly. Nandesari ramp-up from FY27/FY28 therefore becomes the key earnings trigger.
On margins front it will be interesting to watch if utilisation + specialty recovery can take margins back towards historical levels.
SAM remains optionality for now.
In short: the next leg is about converting strong demand into capacity utilisation, operating leverage and margin expansion. Sudeep Pharma us definitely worth tracking.✌️👌
#IPO# Analysis.
#Rentomojo# .
Positives ✅️
-Strong Growing Financials.
- Strong D2C presence in the segment.
Caution⚠️
- More than 80% of issue size is OFS.
- High Borrowing.
- Major Part of IPO funds to be used for debt repayment.
#IPO# Analysis.
#KanoharElectricals#.
Positives ✅️
- Decent Financials strength.
- High Entry Bearier in the segment.
Caution⚠️
- More than 70% of issue size is OFS.
- A little on the expensive side with PE of 38-39.
#SyrmaSGSTechnology
Sector Analysis | Electronics Manufacturing
India’s EMS opportunity is expanding rapidly as China+1, electronics localisation and global supply-chain diversification drive manufacturing towards India. Automotive, industrial, healthcare and consumer electronics remain key demand areas.
Why Syrma stands out: Its diversified customer base, design-to-manufacturing capabilities and growing export exposure provide multiple growth engines, while increasing value-added/ODM work can improve the business mix.
Key monitorables: Export growth, new customers, ODM/value-added business & margins.
#Powerequipment space and why #TDPowerSystems stands out
A thread 🧵
#TDPowerSystems Q1 FY27 Result: the one thing that actually matters this quarter
Profit grew exactly as fast as revenue — not faster. The margin story hasn't even started yet.
1️⃣ Revenue up 72% YoY (₹372 Cr → ₹640 Cr) 📈 — a huge scale-up in one year.
2️⃣ EBITDA (Earnings Before Interest, Tax, Depreciation, Amortization) margin? Basically flat at ~19.3% ⚠️ — the company grew fast without losing efficiency, but hasn't gained any either.
3️⃣ ROE steady at 24.7% 💰 — and it's real profit, not debt. Company is almost debt-free.
🎯 The real story: This is volume-led execution, not margin-led re-rating. If margins ever do expand on top of this growth, that's the next leg up.
#TDPowerSystems #CapitalGoods #EquityResearch #QuarterlyResults #IndianStocks
A Thread on TELECOM EQUIPMENT & INFRA | TTM & why #HFCL stands out basis Q1FY27 Performance.
#HFCL is emerging as the strongest all-round player among its telecom peers.
The headline numbers look strong across HFCL and Sterlite Technologies.
But the real story is HFCL’s combination of growth, profitability, returns and valuation — leading in 9 out of 10 metrics.
Here’s peer scorecard 👇
🟢 HFCL — STRONGEST
Revenue: +59% YoY | Profit: +1,591% YoY
Operating Profit Margin: 19%
Why: HFCL leads on revenue growth, profit, margins, ROE, ROCE and has the lowest P/B at 7.01x Its TTM net profit stands at ₹604 Cr.
🟢 STERLITE TECHNOLOGIES — STRONG GROWTH
Revenue: +36% YoY | Profit: +1,490% YoY
Operating Profit Margin: 15%
Why: Strong earnings recovery and the highest 1-year stock return of 374%, but returns and valuation remain behind HFCL.
🔴 ITI LTD — BELOW AVERAGE
Revenue: -41% YoY | Profit: +51% YoY
Operating Profit Margin: 2.5%
Why: Profit growth is positive, but the sharp revenue decline, low margins, negative ROE and 14.6x P/B remain concerns.
### SECTOR VERDICT
HFCL stands out as the strongest all-round performer in this peer set.
It combines 59% revenue growth, ₹604 Cr TTM profit, 19% OPM, 6.95% ROE and 10.9% ROCE — while still trading at the lowest P/B among the three.
🟢 Best performer: HFCL
🟡 Need to watch: Sterlite Technologies
🔴 Biggest concern: ITI Ltd
The key question for the next quarter:
👉 Can HFCL sustain its exceptional growth and profitability as its optical fibre, 5G and telecom equipment order book continues to scale?
Overall: HFCL currently looks like the strongest risk-reward story in this peer comparison.
#HFCL #SterliteTechnologies #ITILtd #Telecom #TelecomStocks #StockMarketIndia #IndianStocks #StockComparison #GrowthStocks #FinTwitIndia
Specialty Chemicals Sector Q1FY27 Analysis & Why Acutaas has come out as clear winner in the sector: Acutaas vs Anupam Rasayan vs Neogen
While Anupam Rasayan leads in scale, Acutaas Chemicals stands out on quality of performance in Q1 FY27.
Here’s what makes Acutaas different:
📈 59.1% YoY revenue growth — highest among peers
💰 34.3% EBITDA margin — strongest profitability
📊 22.7% PAT margin — significantly ahead
🏆 24.0% ROE | 31.6% ROCE — superior capital efficiency
💪 0.02 Debt-to-Equity — virtually debt-free
Anupam Rasayan brings scale with ₹6,675 Cr revenue, but its margins and returns are lower.
Neogen Chemicals* remains smaller, with weaker profitability and higher leverage.
Acutaas isn't the biggest player — but in Q1 FY27, it delivered the strongest combination of growth, profitability, returns and balance-sheet strength.
Is Acutaas emerging as the strongest specialty chemicals bet among the three?
#AcutaasChemicals #AnupamRasayan #NeogenChemicals #SpecialtyChemicals #Q1FY27 #ChemicalStocks #StockComparison #IndianStocks #GrowthStocks #StockMarketIndia
Private banks Q1 FY27: margins bottomed, provisions did the heavy lifting. 5 banks, 5 different stories behind similar headlines.
🟢 ICICI — the clean one: NII +12.7%, PAT +16% to ₹14,804cr, NIM 4.36% (↑2bps), GNPA down to 1.38%. No one-offs, best print of the quarter.
🟡 HDFC — headline lies both ways: PAT +5% looks soft (last year had a ₹6,949cr HDB IPO gain; adjusted growth ~9.8%), but NIM hit a record-low 3.26% and RoE slipped to 13.8% from ~18%.
🟡 Axis — the beat with an asterisk: PAT +22.5% to ₹7,114cr, but provisions fell ~44% doing the work while NIM cratered 34bps to what mgmt called the "cycle bottom."
🟢 Kotak — quiet outperformer: best RoA (2.1%) and asset quality (GNPA 1.18%) in the pack, PAT +25.6%, broad-based and clean.
🔴 IndusInd — recovery, not a beat: PAT +71.7% is off a rock-bottom base from last year's derivatives stress; core revenue fell 5% YoY, GNPA still 2-3x every peer.
Sector tell: every bank but ICICI saw NIM compress or flatten — FY27 profitability now hinges on deposit mix and credit cost, not lending margins.
#PrivateBanks #Q1FY27#Earnings#IndianBanks#Q1Results
AUTO SECTOR — Q1 FY27 scorecard
The sector grew well. But growth quality separated the winners from the laggards.
Here’s how the major auto players fared:
• 🟢 STRONG — Bajaj Auto: Revenue +37%, EBITDA (Earnings Before Interest, Tax, Depreciation and Amortization) margin improved to 20.9%, while profit jumped 42%. Strong growth + better margins = highest-quality quarter.
• 🟢 STRONG — Eicher Motors: Revenue +31.5% and profit +21%. EBITDA margin held near 24%. Costs rose across the sector, but Eicher largely protected profitability.
• 🟡 MIXED — TVS Motor: Revenue +38%, profit +51%. Looks excellent — but ₹150 Cr fair-value gain contributed to the profit growth. Underlying operating performance deserves more attention.
• 🟡 MIXED — Mahindra & Mahindra: Revenue +23% and consolidated profit +34%. But underlying auto PBIT (Profit Before Interest and Tax) margin fell 170 basis points YoY. Growth was strong, efficiency wasn't.
• ⚪ AVERAGE — Tata Motors: Revenue +23%, profit +8%, but EBITDA margin slipped to 11.7%. Reported numbers are also affected by the CV/PV demerger, making comparisons less clean.
• 🔴 WEAK — Maruti Suzuki: Revenue surged 36%, yet profit fell 9%. EBITDA margin collapsed from 11.6% to 8.9%. This is the clearest example of revenue growth without earnings growth.
• 🔴 WEAK — Tata Motors PV/JLR: Revenue +9.3%, adjusted EBITDA margin fell to 7.4%, while profit declined sharply. The headline ROE (Return on Equity) looks high, but ROCE (Return on Capital Employed) was only 2.73% — showing why reported returns need context.
Sector takeaway: Q1 FY27 wasn't simply about demand. Pricing power, product mix and cost absorption decided who converted revenue growth into profit.
Management guidance / next-quarter outlook: Not disclosed in the provided sector snapshot.
Verdict: 🟢 Bajaj Auto & Eicher lead on earnings quality. TVS & M&M need closer scrutiny. Maruti and JLR show the biggest margin/profitability concerns.
Which Q1 result do you think has the strongest earnings quality?
#AutoStocks #Q1Results #StockMarketIndia #NiftyAuto #FinTwitIndia
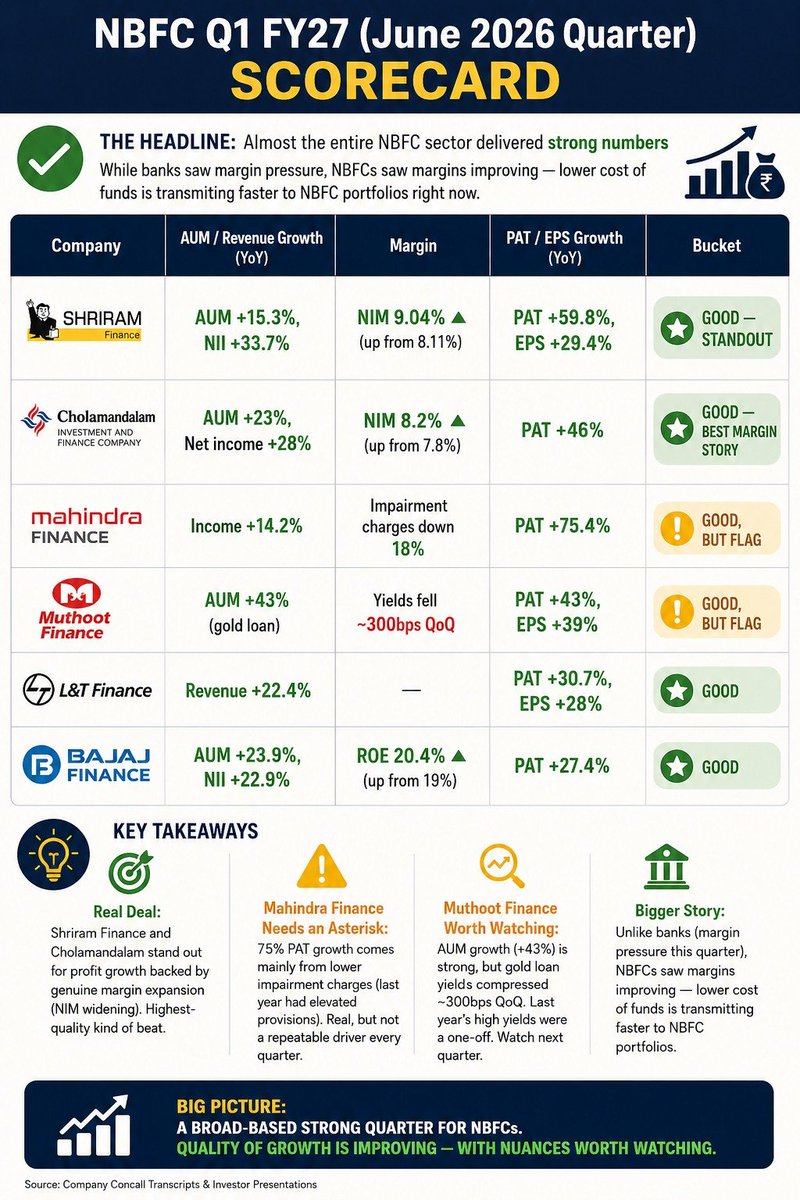
Banks had a rough Q1 FY27.
NBFCs did not.
While #HDFCBank and #SBI wrestled with margin pressure, most listed NBFCs quietly had one of their best quarters in years. Falling funding costs are hitting NBFC books faster than bank loan books — and the numbers make it obvious.
#shriramfin : profit up 60%. But the real number is NIM — up to 9.04% from 8.11%. That's margin expansion, not just a bigger balance sheet.
#Cholamandalam : PAT up 46%, margin widened to 8.2% from 7.8%. Same story, different name.
#BajajFinance did the boring-but-brilliant thing — AUM, NII, and profit all moved together, and ROE crossed 20% for the first time.
Now the twist.
#MahindraFinance posted 75% profit growth. Impressive — until you check income, which grew just 14%. Almost the entire "beat" came from lower provisions vs last year. Not core growth. Not repeatable.
#Muthoot Finance grew AUM 43%. Sounds great — until you see gold loan yields fell ~300bps in a single quarter. Management themselves called last year's yields a one-off.
Same headline. Very different quality of quarter.
That's the difference between reading a results PDF and reading a scorecard.
#NBFC #Q1Results #StockMarketIndia #NiftyBank #FinTwitIndia