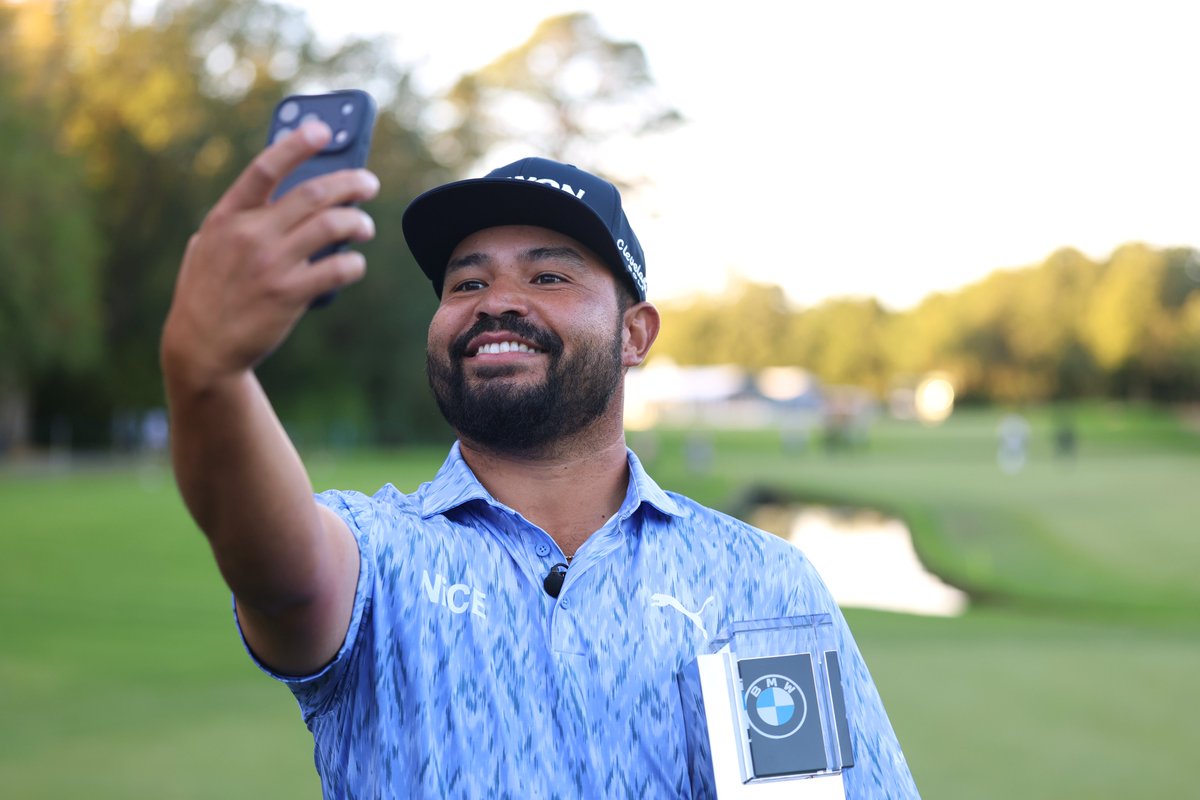
JJ Spaun learned he missed the President's Cup team via a 45-second call. Snedeker told him he was "the odd man out." Spaun had conversations throughout the year that led him to believe he would be on the team. #Golf#PresidentsCup#JJSpaun
🚨BREAKING: Brad Garlinghouse is hinting that $XRP could become part of America’s financial system after Ripple spent $150,000,000fighting the SEC.
Some projections now point ABOVE $30,000 per XRP.
This is MUCH bigger than people realize.
So the ECB just went ALL IN on its tokenization push.
I did a deep dive, and it made me 100x more bullish on $XRP and $QNT. Why? You’re going to love this long read.
Something changed in Europe on September 21 that I think a lot of crypto people are going to underestimate.
Pontes is live.
The Eurosystem can now connect tokenized markets with its existing TARGET Services so the cash side of a tokenized securities transaction can settle in central-bank money. And Reuters reports the ECB plans to put part of its roughly €23 billion own-funds portfolio into highly rated, euro-denominated blockchain securities issued by public institutions.
Read that slowly.
The central bank is providing the settlement infrastructure.
European financial institutions are connecting to it.
And the ECB itself intends to own tokenized securities.
I’ve been deep in $XRP and $QNT, and following this whole tokenization shift has made the thesis around both much easier for me to understand.
Because the financial world they were built around is starting to become real.
Let me make this very simple.
Suppose a bank tokenizes a €500 million bond.
Putting that bond on a distributed ledger solves only part of the problem.
Somebody buys the bond.
Money needs to move in the opposite direction.
If the bond moves on modern DLT infrastructure but the money still has to leave that environment, travel through separate systems, get reconciled and settle later, you lose a huge part of the advantage.
Europe needed a trustworthy cash leg.
Pontes gives institutions one.
A tokenized security can now connect back into central-bank euro settlement through TARGET Services. The ECB says synchronization can support Delivery-versus-Payment transactions where the asset and money are linked together.
That sounds technical.
In everyday language:
the asset moves and the money moves together.
That is a massive step toward making tokenized finance usable by banks and asset managers at scale.
And look at the institutions already onboarded:
ABANCA, BayernLB, Caisse des Dépôts et Consignations, Cecabank, Deutsche Bank, DekaBank, DZ BANK, European Investment Bank, KfW, Memo Bank, NRW BANK, Santander and Société Générale.
The initial DLT operators include Axiology, Cashlink, Clearstream and SWIAT, while Deutsche Bundesbank has also onboarded.
These aren’t people gathering around a whiteboard wondering whether tokenization could work someday.
The infrastructure is available now.
And one comment from Christine Lagarde explains how important that settlement piece really is.
The ECB spoke with more than 60 market participants, and Lagarde said the message from the market was clear: they would not commit to issuing digital assets at scale until they could settle in central-bank money.
That sentence changed how I looked at Pontes.
Europe already had institutions interested in tokenization.
The missing piece was confidence in settlement.
Now the Eurosystem is providing it.
And the ECB has openly described central-bank-money access as one of the conditions needed for tokenized finance to reach critical mass.
So I started asking myself:
If more European bonds, funds, money-market instruments, deposits, repos and other financial assets begin moving onto DLT because the settlement problem is being solved, who benefits from connecting all those systems and moving liquidity between all those assets?
That brought me straight back to $QNT and $XRP.
$QNT first.
The ECB’s long-term project is called Appia.
Pontes handles the bridge into central-bank settlement today.
Appia is looking at what the wider European tokenized market should eventually become.
And the ECB is openly considering several architectures:
one shared European network,
multiple interconnected networks,
or some combination of both.
If Europe ends up with multiple networks, the ECB says a high degree of interoperability will be required to stop assets and liquidity from becoming fragmented.
Seriously.
Read those words again:
multiple interconnected networks.
-Interoperability.
-Tokenized assets.
-Central-bank money.
-Private settlement assets.
-Legacy infrastructure.
-Programmability.
I’ve followed Quant for a long time, and that is almost a description of the problem Overledger and QuantNet were created around.
A bank already has decades of systems.
It cannot wake up Monday morning and throw everything away because blockchain exists.
It still has core banking infrastructure.
-Payment rails.
-Risk systems.
-Legacy ledgers.
-RTGS connections.
-Private DLTs.
-Maybe public blockchains.
-Tokenized deposits.
-Stablecoins.
-Tokenized bonds.
Potentially several different settlement networks.
Quant’s approach is to let those environments communicate and coordinate without asking the institution to replace everything underneath.
And this connection to Europe is not coming from nowhere.
Quant Network Europe Limited was officially listed by the ECB as a Pioneer in its Digital Euro Innovation Platform.
Quant worked on programmability and conditional payments around the ECB’s digital-euro environment.
So Quant has already been inside an ECB-led digital-money experiment.
Then look at what Quant did with Murex in March.
Murex and Quant integrated Quant’s programmable-money infrastructure into MX.3, allowing banks and capital-markets firms to issue, settle and manage tokenized deposits and digital bonds using existing institutional workflows.
The setup uses Quant’s Flow and Overledger technology for programmability, cross-rail payment orchestration and interoperability across public and private blockchains.
That matters because banks do not want twelve disconnected tokenization systems.
They want their existing trading, risk, reporting and post-trade infrastructure to work with the new rails.
And Quant is already attacking that problem.
Then there is the UK.
Quant was selected to provide infrastructure to the Great British Tokenised Deposits project involving Barclays, HSBC, Lloyds Banking Group, NatWest, Nationwide and Santander.
Its role includes programmable money and interoperability between bank ledgers, RTGS, Faster Payments, Open Banking and tokenized-deposit platforms.
And notice one name:
Santander.
Santander is also one of the first institutions onboarded to Pontes.
I’m not saying Santander uses Quant for Pontes. There is no announcement saying that.
The deeper point is more interesting anyway.
A bank such as Santander can end up operating across several forms of digital financial infrastructure at the same time.
Pontes.
-Tokenized deposits.
-Traditional banking systems.
-DLT markets.
-International payment networks.
-Potentially public chains.
Once large banks operate across multiple environments, connecting them becomes more valuable.
That is Quant’s whole addressable problem.
And Pontes itself is only going to become more capable.
The ECB plans to extend operating hours toward 22.5 hours per business day, then move toward 24/7 service by mid-2028, together with greater programmability, stronger resilience and multi-currency capability.
Multi-currency really matters to me.
A European tokenized market becomes much more complicated once you move beyond a euro security settling against one euro cash asset.
Now you can have different currencies.
Different banks.
Different networks.
Different digital-money forms.
Different assets.
Different jurisdictions.
Somebody has to coordinate the movement.
That is exactly the kind of market where interoperability stops being a nice extra and becomes basic financial plumbing.
So my $QNT thesis from this ECB move is simple:
Europe is starting to build the multi-network financial architecture Quant has spent years preparing to connect.
The ECB doesn’t need to announce that it is buying QNT for the underlying opportunity to expand.
If interoperability becomes mandatory infrastructure across tokenized banking and capital markets, the market Quant is targeting becomes much larger.
And then there is $XRP.
The XRP side of this story works differently.
Europe now has a trusted central-bank settlement anchor.
Great.
That can unlock more issuance.
-More bonds.
-More tokenized funds.
-More money-market instruments.
-More private money.
-More trading.
-More collateral.
-More digital assets.
And Ripple has spent years building inside European finance before that market reached this stage.
Ripple received its full MiCA CASP authorization from Luxembourg’s CSSF in July, giving its regulated cryptoasset services coverage across all 30 EEA countries. Ripple also has its European EMI licence and says its global regulatory portfolio exceeds 75 licences.
That gives Ripple a serious regulated position as Europe’s tokenized market begins moving from experimentation toward production.
Then look at the banks.
BBVA Spain uses Ripple Custody technology in its digital-asset custody service.
Intesa Sanpaolo uses Ripple Custody in its digital-asset initiatives.
DZ BANK uses Ripple Custody for institutional digital assets, including crypto securities such as tokenized bonds under Germany’s electronic-securities framework.
And DZ BANK is also one of the first Pontes participants.
Again, I’m keeping the connection precise.
That does not say Pontes runs on Ripple.
It says the same major European bank is participating in the ECB’s new tokenized-settlement infrastructure while already operating Ripple technology elsewhere in its digital-asset business.
That overlap matters because these systems are starting to meet inside the same institutional world.
Then look at Société Générale.
This one is even more interesting to me.
Société Générale is among the initial Pontes participants.
Its digital-asset subsidiary Société Générale-FORGE launched its regulated EUR CoinVertible, EURCV, directly on the XRP Ledger in February 2026.
The XRPL deployment is supported by Ripple Custody, and SG-FORGE has said it intends to explore further uses, including integrating EURCV into Ripple products and using it as trading collateral.
So one major European banking group is operating in both worlds:
the ECB’s emerging central-bank-money settlement infrastructure,
and private regulated euro money on XRPL.
You can start to see the market taking shape.
-Central-bank euros.
-Tokenized deposits.
-Private euro settlement assets.
-Tokenized securities.
-Different DLT networks.
-Custody.
-Trading.
-Liquidity.
-Collateral.
This is exactly the messy multi-asset financial world where both XRP and QNT become much more interesting.
XRPL also has EURØP from Schuman Financial.
EURØP is a MiCA-compliant, euro-backed stablecoin issued by a French electronic-money institution regulated by ACPR, and it is natively integrated into XRPL. Its reserves are held through European institutions including Société Générale.
Then add Aviva Investors.
Aviva is working with Ripple to explore tokenizing traditional fund structures directly on XRPL, with both sides planning to continue the initiative through 2026 and beyond.
Then add Ripple’s investments in ZILO and Licuido, which connect transfer-agency, issuance and collateral-mobility capabilities into Ripple’s broader capital-markets strategy.
Now think about the kind of European market that can emerge as Pontes removes the settlement bottleneck.
A German bond exists digitally.
A French money-market fund exists digitally.
EURCV sits on XRPL.
EURØP sits on XRPL.
A tokenized bank deposit sits somewhere else.
An Aviva fund sits onchain.
A U.S. Treasury exists on another network.
Institutions need to move between all of it.
Some transactions want central-bank euros at final settlement.
Pontes can provide that anchor.
But between those endpoints, the market still needs trading liquidity.
-FX.
-Collateral.
-Cross-border movement.
-Asset conversion.
-Secondary markets.
Movement between different forms of money.
XRPL was built around exchanging different representations of value on one ledger.
And XRP is the issuerless native asset inside that market.
That is the XRP opportunity I care about.
XRP does not need to become “the euro.”
It does not need to replace TARGET.
It does not need the ECB to hold XRP.
The much more believable long-term utility is liquidity.
If a growing European tokenized market contains hundreds or thousands of assets and multiple forms of digital money, liquidity becomes a real problem.
Some markets will have direct pairs.
Others will not.
Some cross-border routes will be deep.
Others will be fragmented.
Some assets may need a neutral intermediary.
That gives XRP a potential economic job.
And Ripple has already spent years building the custody, tokenization, regulated access and institutional infrastructure around the ledger where XRP lives.
Then Appia makes this even bigger.
The ECB wants a blueprint for an integrated European tokenized financial ecosystem by 2028.
Its own documents talk about interoperability, asset transfers, collateral mobility, cross-border transactions, central-bank money, private settlement assets and a market where issuance, trading, settlement, custody and servicing evolve together.
That is an enormous architecture.
In my head, $QNT and $XRP sit in very different places inside it.
QNT can matter because all those systems need to communicate.
XRP can matter because all those assets need liquidity.
Quant handles orchestration.
XRPL can host assets and markets.
Ripple supplies regulated institutional infrastructure around it.
XRP can provide native liquidity where it makes economic sense.
And Europe has just made one of the biggest pieces of that whole system operational.
The ECB did not announce XRP or QNT as Pontes components.
I actually think the factual setup is more powerful without pretending it did.
Pontes validates the market they have been positioning around.
The central bank is now giving tokenized securities a trusted cash settlement layer.
It intends to invest some of its own portfolio in blockchain securities.
Banks are onboarding.
Private DLTs are connecting.
Appia is planning an interoperable future.
Pontes is moving toward 24/7 and multi-currency.
Ripple already has European banks, euro assets, custody, MiCA authorization and asset-manager tokenization work around XRPL.
Quant already has an ECB Digital Euro relationship, Murex integration and major-bank tokenized-deposit infrastructure.
A year ago, people could call all of this a future narrative.
Today the rails are switching on.
And I’m sitting here thinking about what happens after millions, then billions, then potentially much larger pools of financial assets start living across multiple digital networks.
Somebody has to connect the networks.
Somebody has to move the liquidity.
That is exactly why this ECB move made me even more bullish on $QNT and $XRP.
Holding these two? You’re gonna make it.
Pontes is Latin for bridges. $XRP is already the bridge asset sitting in front of banks and regulators. You don’t name the door Bridges unless value has to leave that door and meet another currency or another ledger. What sits in the middle is XRP. The name is the job.
If you look at the last two years, it's clear President Trump is preparing for something big.
He's securing permanent security control over Greenland, kicked China out of the Panama Canal, and locked up 65 billion barrels of Venezuelan oil. For 25 years, China quietly bought up our backyard to gain a strategic stranglehold on our side of the globe. In just 20 months, Trump pulled the rug right out from under them.
While the rest of the world fractures, Trump is building a completely self-sufficient Western Hemisphere. One where America controls its own destiny without bowing to Beijing or Tehran.
🚨 HOLY SMOKES. A jaw-dropping investigation founds a NETWORK of Somali daycares in Seattle where bystanders say children NEVER GO INSIDE, despite receiving up to $70K monthly
The Somalis came outside, panicked and RAGED when confronted: "GET OUT OF HERE!"
"Red necks are here!"
"Are you Trump people?!"
@KatieDaviscourt asked one man: Are kids going into the daycare? He said: "THERE'S NO KIDS."
It could be a massive fraudulent RACKET to steal more taxpayer funds to the tune of MILLIONS 🤯
Seattle is deep-blue and has a sizeable Somali population, though not as large as Minneapolis
It's CLEAR that it's time for a surge in Seattle just like we've seen in other cities across America. Too many foreign pirates getting away with robbery
Send police to their doors, investigate their records and find out if they are LYING to receive these huge sums of money
Citizen journalism wins again!
XRP didn’t need an oil crisis narrative to rise in price.🙇♂️
It needs more regulatory clarity.
And that is exactly what is being delivered to the market through the SEC and CFTC.✅
Retail investors waiting for crypto to crash as a result of oil or the yen will be sidelined.🔻
👇
You don’t need the exact bottom to make real money. You need the nerve to buy while everyone else is still waiting for the perfect moment.
Full breakdown + notes in the report.
Trinidad Chambliss, Ole Miss Rebels ⭐️ QB, is this year’s feel-good story, following in the footsteps of Indiana Heisman Trophy 🏆 QB Fernando Mendoza.
Grounded in faith, he explains the powerful impact God has on his life. He also prays with his mom and hugs her before every game.
Will he follow the same trajectory as Mendoza, win the Heisman, and lead the Rebels to a national title?
Opine ⬇️ Even depressed LSU fans are welcome to reply.
@ESPNCFB
Trends come and go, but God’s Word never changes. Scripture shows us His unshifting design for our identity, Our relationships, every life, and our salvation. Culture may push back, but His truth remains our solid Rock. Stand firm on what He has spoken! 🤍
Somehow I can’t see Luke Donald treating a recent major champion and a #17 player in the world such as J.J. Spaun like this…
Maybe that’s why @RyderCupEurope keep the good vibes.
After JJ Spaun’s impressive victory at the BMW PGA Championship, he said he felt like he had something to prove and had “imposter syndrome” after winning the US Open in 2025:
“I believe this year was a tough year for me because internally I was fighting all these expectations of being a worthy Major Champion.
“I felt like I still had to prove to everyone that I wasn't a fluke and I wasn't some money-in-the-bottle Major Champion. You hear things about that, and it kind of eats inside a little bit. I put way too much pressure on myself to start the year.
“But once I kind of stopped caring so much, I mean, I know it's easy to say that, I mean obviously but that was kind of mantra all last season. That's why I played so well. I was on the verge of losing my job in 2024 and then I backdoored it to keep it, and I was like, Oh, this is house money, I wasn't even supposed to be here in 2025. That sort of attitude, along with obviously skill and developing and playing good, that was a breakout year.
“And then here we are back in January and I'm back to this ball of pressure and expectation and thinking I have to be this perfect golfer and to validate whatever I did in 2025.
“Once I kind of let go of that and stopped caring what other people think or what the media thought of me, I started relaxing and playing better. Then I won in San Antonio, and then once I won in San Antonio, okay, I'm pretty content with everything I've done. If I were to die tomorrow, I'd feel like I have.
“It was just getting over that hump of expectation and mindset that I had last year and I started playing better. Like this week, I didn't have a ton of expectation. I couldn't play the Tour because I woke up with a stiff neck and couldn't turn it. So I had two weeks to get ready for this and I did it.
“Sometimes no expectation is the best thing to have.”
In JJ’s last 2 seasons he’s won his first major, won again on the PGA Tour, won the DP World Tour’s flagship event and finished runner up to Rory McIlroy at The Players Championship. He’s definitely not an imposter, he’s a certified champion and he has nothing to prove to anyone.
@DPWorldTour@BMWPGA
J.J. Spaun was left off the U.S. Presidents Cup team.
So, he went to the BMW PGA at Wentworth and beat a stellar field that included Rory McIlroy, Matt Fitzpatrick, and Adam Scott.
https://t.co/sC1E3lJP50