@ZelenskyyUa Peace must honor the victims, protect the living, and preserve Ukraine’s dignity. A ceasefire cannot erase memory or replace justice. It can offer a chance to rebuild, to care for one another, and to let LOVE help heal the wounds of war.
In 1994, Ukraine chose to give up its nuclear weapons in exchange for international security assurances. Yet Russia seized Crimea in 2014 and launched a full-scale invasion of Ukraine in 2022. The security assurances provided under the Budapest Memorandum failed to prevent either of these events.
When countries that give up nuclear weapons become victims of aggression, while those possessing credible nuclear deterrents can make even the most powerful adversaries think twice, the greatest danger to the international community is not that one particular country decides to acquire nuclear weapons. It is that more and more nations begin to believe that their security ultimately depends not on international law or security guarantees, but on the nuclear weapons they possess themselves.
If a country can launch a war, seize its neighbor’s territory, and ultimately force that neighbor to recognize the occupied land as its own through a peace agreement, the international community will face a fundamental challenge: how to prevent the redrawing of borders by force from becoming a precedent that other countries can follow.
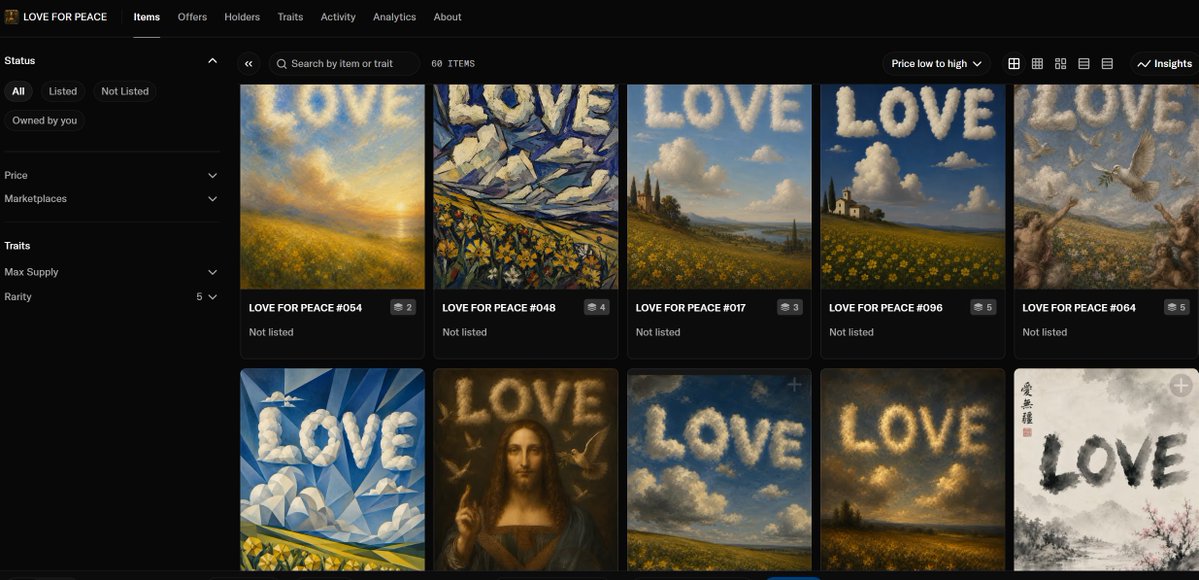
LOVE FOR PEACE now has a home of its own.
https://t.co/7T7llnxJq4
Genesis: 100 pieces. Sealed forever.
Chronicle: One NFT for every historic turning point on the path to peace. Minted only by burning LOVE.
Every war leaves scars. Every love leaves hope.
This crypto market cycle is fundamentally different from previous bull and bear cycles. Meme coins and NFTs, which once generated extraordinary wealth and spectacular returns, now seem increasingly unlikely to replicate their former glory.
The reason is not simply a lack of market liquidity. Rather, the capital structure, investor composition, and mechanisms of wealth creation in the cryptocurrency market are undergoing profound changes.
First, the market is no longer an early-stage speculative arena dominated by retail investors, narratives, and market sentiment. The introduction of spot Bitcoin ETFs, along with the growing participation of institutional investors and professional trading firms, has concentrated an increasing share of capital in Bitcoin and a handful of highly liquid assets. Institutional capital is generally far less inclined than early retail investors to chase meme coins and NFTs that lack fundamental value.
Second, the barriers to issuing new tokens have fallen to virtually zero. During the previous cycle, a new meme coin or NFT project could quickly attract widespread attention partly because of its novelty and perceived scarcity. Today, countless new tokens can be created every single day, fragmenting both attention and liquidity across an enormous number of competing projects. When anyone can effortlessly create a new asset, the truly scarce resource is no longer the token itself, but market consensus.
Third, the extraordinary wealth effects generated by meme coins and NFTs in the previous cycle were fundamentally dependent on a continuous influx of new capital. When early investors achieved returns of tenfold, fiftyfold, or even a hundredfold, fear of missing out drove successive waves of new participants into the market.
However, after multiple cycles of spectacular rallies and crashes, projects collapsing to zero, insider trading, and liquidity crises, investors have developed a much greater awareness of the risks associated with these assets. Relying solely on community slogans, cultural symbolism, and expectations of rising prices is becoming increasingly insufficient to sustain long-term demand.
Of course, this does not mean that meme coins and NFTs have no future. They may still experience explosive growth driven by unique cultural events, strong community consensus, or innovative applications.
For NFTs, the most promising opportunities may no longer lie in issuing 10,000 images and hoping their prices appreciate. Instead, the future may belong to NFTs that represent genuine historical significance, cultural value, digital identity, or practical utility.
Similarly, the meme coins that survive over the long term may not simply be those with amusing names or the ability to generate short-lived internet hype. Rather, they may be projects capable of transforming cultural identity into sustained community engagement, lasting influence, and genuine demand.
Aleo’s strategic direction has become increasingly clear, and its commercialization efforts have made encouraging progress. From programmable privacy technology and the USDCx stablecoin to the gradual development of wallet integrations, exchange support, and enterprise payment infrastructure, Aleo is working to build a new generation of financial infrastructure that combines privacy protection, regulatory compliance, and real-world commercial utility.
However, technological superiority does not necessarily translate into commercial success. The greatest uncertainty facing Aleo is no longer simply whether its technology can deliver, but whether demand for privacy-preserving stablecoins can grow rapidly enough—and, more importantly, how much of that growth can ultimately translate into value for the $ALEO token.
In my view, Donald Trump may already be the most favorable negotiating partner Vladimir Putin could possibly hope to find within the American political system. A Trump who emerges victorious from the midterm elections, with Republicans retaining control of Congress, could potentially offer Russia far greater advantages than a Trump whose party loses its congressional majority and who faces strong opposition from the Democrats.
Yet Putin seems in no hurry to seize this rare political opportunity.
Judging by Russia’s current strategic choices, Putin apparently still believes that time is on his side. He may assume that the United States and Europe are growing increasingly weary of the prolonged war in Ukraine, that Ukraine’s financial resources, manpower, and military capabilities are steadily being depleted, and that the rise of right-wing political forces across Europe will eventually further weaken Western support for Kyiv.
By this logic, Russia only needs to hold out longer to secure more favorable terms at the negotiating table.
But reality may prove otherwise.
Putin appears to be overlooking one critically important variable: Trump’s political power is not indefinite, and the American political landscape will not remain frozen in its current state forever.
If Republicans lose control of Congress in the 2026 midterm elections, Trump’s domestic political position could change dramatically. Democrats could use their legislative, budgetary, and oversight powers to push for renewed or expanded military assistance to Ukraine, impose tougher economic sanctions on Russia, and exert greater pressure on Trump’s approach to the war.
Under such circumstances, even if Trump remains willing to negotiate a deal with Putin, his ability to offer political assurances, policy commitments, and diplomatic concessions could become increasingly constrained.
More importantly, the rise of right-wing political forces in Europe does not necessarily mean that Russia’s strategic position will improve. Europe’s right wing is far from a unified political bloc. While some factions advocate reducing support for Ukraine, others remain deeply suspicious of Russia and strongly favor strengthening European defense capabilities. If Putin simply equates Europe’s political shift to the right with the eventual collapse of Western support for Ukraine, he may be making a serious strategic miscalculation.
International politics is never static. What appears advantageous today can be completely transformed tomorrow by an election, a major policy shift, or even a military setback.
For Putin, the real question may not be how much longer Russia can sustain the war, but whether the additional gains he hopes to extract by prolonging it are worth the risk of a future reversal in the political environment.
History has repeatedly demonstrated that one of the most dangerous strategic mistakes in warfare is to confuse a favorable short-term trend with an irreversible historical inevitability.
Putin may be trying to squeeze the very last coin off the negotiating table, without fully considering that by the time he finally reaches for it, the entire table may already have been overturned.
In international politics, greed does not always produce greater rewards. Sometimes, true strategic wisdom lies not in pushing your opponent to the absolute limit, but in knowing when to strike a deal while you still hold the advantage.
Aleo has an extraordinarily ambitious vision. If it can achieve a genuine breakthrough in privacy-preserving stablecoins and become a critical financial infrastructure connecting private payments, enterprise finance, and regulatory compliance, its long-term market valuation could have enormous upside potential.
However, technological superiority does not automatically translate into commercial success. Aleo’s greatest challenge is not proving that USDCx is technologically more advanced than traditional stablecoins, but creating genuine, sustainable, and compelling demand that existing solutions cannot adequately satisfy.
Today, USDT and USDC have already established mature ecosystems. Exchange support, liquidity depth, wallet compatibility, and established user habits have collectively created powerful network effects. For the vast majority of users, if existing stablecoins already meet their payment needs, why would they deliberately switch to USDCx? Privacy alone may not be enough to change deeply entrenched habits.
Therefore, Aleo must first answer a fundamental question: Which existing financial and commercial activities have a pressing need for privacy-preserving stablecoins that traditional USDT and USDC cannot adequately fulfill?
A more realistic strategy would be to identify a specific market segment with strong privacy requirements, frequent payment activity, an established business model, and a clear regulatory compliance pathway—and concentrate resources on achieving a breakthrough there.
Potential opportunities include B2B settlements, cross-border supplier payments, payroll, privacy-sensitive digital services, and institutional treasury operations.
These scenarios share one defining characteristic: Privacy is not an optional feature. It is a fundamental requirement tied to trade secrets, competitive advantages, customer trust, and sometimes the very feasibility of a transaction.
In terms of practical adoption, Aleo could integrate privacy-preserving payments directly into existing business workflows through partnerships with payment service providers, enterprise wallets, and commercial platforms, allowing users to adopt USDCx naturally through familiar payment experiences.
What truly matters is not how many people know about USDCx, but how many people consistently use it because of genuine commercial needs.
Even if the initial breakthrough comes from just one major payment platform, one established digital services industry, or a few dozen enterprises regularly settling transactions in USDCx, establishing a sustainable cycle of capital inflows, payments, receipts, and repeated use would already represent a major milestone.
First, identify a market that genuinely needs privacy-preserving stablecoins, then build a complete payment ecosystem around it. Establish real demand before scaling liquidity. Validate the business model before expanding into broader markets.
As real transaction volumes grow, wallets, payment gateways, liquidity providers, exchanges, and developers will gain stronger commercial incentives to participate. The network effects generated through genuine economic activity will be far more sustainable than those driven purely by marketing campaigns or speculative token price appreciation.
At the same time, Aleo must establish a clear mechanism for capturing economic value. Growth in USDCx transaction volume, circulation, and ecosystem activity does not necessarily translate into proportional appreciation in the market value of the ALEO token. Only when increasing network usage generates sustained demand for ALEO can ecosystem expansion and token economics reinforce each other.
Technology determines how far Aleo is capable of going. Real demand determines whether it will ever get there.
Aleo’s vision is highly promising. Judging by its technological direction, ecosystem development, and stablecoin strategy, Aleo clearly aspires to be more than just another privacy-focused blockchain. It aims to become a next-generation financial infrastructure connecting private payments, stablecoins, enterprise finance, and regulatory compliance.
The launch of USDCx, in particular, represents a meaningful step forward in the privacy stablecoin sector. Rather than focusing solely on anonymity, Aleo places greater emphasis on programmable privacy, regulatory compliance, and real-world commercial applications. In my view, this approach has enormous market potential.
However, Aleo faces a significant challenge that cannot be ignored: its current market valuation, liquidity depth, and ecosystem scale remain far below the ambitions of the financial markets it seeks to serve.
The stablecoin market cannot be conquered through technological superiority alone. It requires deep liquidity, seamless exchange on-ramps and off-ramps, mature wallet infrastructure, and major commercial customers capable of generating sustained, real-world transaction demand.
More importantly, stablecoin circulation and a blockchain’s native token market capitalization do not need to correspond directly. The real issue is not that Aleo’s market capitalization is too small to support a massive stablecoin market, but that its limited liquidity and ecosystem activity may constrain its ability to attract institutions, market makers, and payment service providers.
What Aleo needs most right now is not to keep demonstrating how advanced its zero-knowledge technology is, but to prove that private stablecoins can solve real-world commercial problems.
From cross-border trade and business-to-business settlements to digital content payments and autonomous AI agent transactions, private payments have enormous potential demand. If Aleo can successfully establish itself in even a few scalable use cases, generating consistent transaction volume and a steadily growing user base, liquidity, developers, and institutional capital could follow.
Aleo has already demonstrated its technological vision and begun building the infrastructure needed to realize it. However, a substantial gap remains between technological leadership and commercial success.
I remain optimistic about Aleo’s long-term direction. But its future value should not rest solely on the scarcity of privacy technology. It should be grounded in genuine payment demand, sustained economic activity, and, crucially, how much of that economic value the ALEO token itself can capture.
If Aleo eventually becomes a major settlement network for private stablecoins worldwide, today’s market valuation may prove to be merely an early stage in its development.
But until then, what will determine Aleo’s future is not the size of its potential market, but the speed at which it can turn that potential into real commercial adoption.
When it comes to Ukraine, the price Europe has paid goes far beyond the hundreds of billions of euros in financial and military assistance. Disruptions to Russian energy supplies, sanctions and counter-sanctions, and the rising costs associated with restructuring energy markets have profoundly affected European manufacturing and global competitiveness. European economies that have traditionally relied on industrial production and affordable energy are now facing sustained structural pressures.
If the war continues, Russia and Ukraine will keep paying a devastating price in human lives, while Europe risks further losses in industrial competitiveness, investment opportunities, and economic growth.
Europe must reassess its strategic priorities. Bringing the Russia-Ukraine war to an end as quickly as possible should be one of Europe’s highest strategic priorities.
However, peace cannot simply mean a cessation of hostilities, nor should it mean forcing Ukraine to accept a ceasefire agreement that could be violated at any moment without credible security guarantees.
Europe should work to establish a postwar security framework built on credible deterrence, long-term military support, and clear enforcement mechanisms. Such a framework would enable Ukraine to preserve its national security, sovereignty, and independence after the war, while creating the conditions for Europe to restore economic stability, reduce energy costs, and rebuild its industrial competitiveness.
What truly serves Europe’s long-term interests is neither an indefinite continuation of the war nor a fragile peace purchased at the expense of Ukraine’s future security. It is ending the war as soon as possible while establishing a European security order that makes another war far less likely.
The 2015 HRT internship program lasted just three weeks and was structured as a competition. Jeff Yan and Scott Wu consistently took the top two spots in every round.
Scott Wu also revealed that many of them had known each other since high school through the Mathematics and Informatics Olympiad communities, long before they joined HRT.
Perhaps the most fascinating takeaway isn’t how many billionaires HRT produced, but how mathematics and informatics Olympiads created an extraordinarily concentrated network of exceptional talent.
A decade later, these individuals have gone on to build companies across artificial intelligence, AI-powered coding, enterprise AI agents, and crypto finance.
Their success demonstrates the remarkable transferability of strong mathematical foundations and algorithmic thinking across industries.
Of course, building a successful company also requires product vision, leadership, and the ability to seize market opportunities.
But one thing is becoming increasingly clear: in the age of AI, mathematical ability is an extraordinary competitive advantage.
@_ABhoomi I agree that Aleo’s market cap is relatively low compared to its potential. What interests me most is whether USDCx can achieve widespread adoption in institutional payments.
What $Aleo is doing now is enabling stablecoins, corporate funds, and institutional assets to operate on blockchain infrastructure while protecting commercial confidentiality and personal privacy, without compromising identity verification, auditing, or compliance with applicable laws and regulations.
Every French person seems to be saying that France is finished, blaming illegal immigration and endless aid to Ukraine.
I think solving France’s problems is actually quite simple: just pass one law.
Force all illegal immigrants to be sent to the Ukrainian battlefield. Those who survive two years of combat would be granted French residency.
If this law were strictly enforced, France’s situation would improve dramatically in a very short time.