CBDT Circular No. 4/2007, dated 15th June, 2007 [F. No. 149/287/2005-TPL]
Distinction between shares held as stock-in-trade and shares held as investment - tests for such a distinction:
1. The Income-tax Act, 1961 makes a distinction between a “capital asset” and a “trading asset”.
2. Capital asset is defined in Section 2(14) of the Act. Long-term capital assets and gains are dealt with under Section 2(29A) and Section 2(29B). Short-term capital assets and gains are dealt with under Section 2(42A) and Section 2(42B).
3. Trading assets are dealt with under Section 28 of the Act.
4. The Central Board of Direct Taxes (CBDT), through Instruction No.1827 dated August 31, 1989, had brought to the notice of the assessing officers that there is a distinction between shares held as investment (capital asset) and shares held as stock-in-trade (trading asset). In the light of a number of judicial decisions pronounced after the issue of the above instructions, it is proposed to update the above instructions for the information of assessees as well as for guidance of the assessing officers.
5. In the case of Commissioner of Income Tax (Central), Calcutta Vs Associated Industrial Development Company (P) Ltd (82 ITR 586), the Supreme Court observed that:
“Whether a particular holding of shares is by way of investment or forms part of the stock-in-trade is a matter which is within the knowledge of the assessee who holds the shares, and it should, in normal circumstances, be in a position to produce evidence from its records as to whether it has maintained any distinction between those shares which are its stock-in-trade and those which are held by way of investment.”
6. In the case of Commissioner of Income Tax, Bombay Vs H. Holck Larsen (160 ITR 67), the Supreme Court observed:
“The High Court, in our opinion, made a mistake in observing whether transactions of sale and purchase of shares were trading transactions or whether these were in the nature of investment was a question of law. This was a mixed question of law and fact.”
7. The principles laid down by the Supreme Court in the above two cases afford adequate guidance to the assessing officers.
8. The Authority for Advance Rulings (AAR) (288 ITR 641), referring to the decisions of the Supreme Court in several cases, has culled out the following principles:
“(i) Where a company purchases and sells shares, it must be shown that they were held as stock-in-trade and that the existence of the power to purchase and sell shares in the memorandum of association is not decisive of the nature of the transaction;
(ii) the substantial nature of transactions, the manner of maintaining books of accounts, the magnitude of purchases and sales and the ratio between purchases and sales and the holding would furnish a good guide to determine the nature of transactions;
(iii) ordinarily the purchase and sale of shares with the motive of earning a profit would result in the transaction being in the nature of trade/adventure in the nature of trade; but where the object of the investment in shares of a company is to derive income by way of dividend etc. then the profits accruing by change in such investment (by sale of shares) will yield capital gain and not revenue receipt”.
9. Dealing with the above three principles, the AAR has observed in the case of Fidelity Group as under:-
“We shall revert to the aforementioned principles. The first principle requires us to ascertain whether the purchase of shares by a FII in exercise of the power in the memorandum of association/trust deed was as stock-in-trade, as the mere existence of the power to purchase and sell shares will not by itself be decisive of the nature of transaction. We have to verify as to how the shares were valued/held in the books of account i.e., whether they were valued as stock-in-trade at the end of the financial year for the purpose of arriving at business income or held as investment in capital assets. The second principle furnishes a guide for determining the nature of transaction by verifying whether there are substantial transactions, their magnitude, etc., maintenance of books of account and finding the ratio between purchases and sales. It will not be out of place to mention that Regulation 18 of the SEBI Regulations enjoins upon every FII to keep and maintain books of account containing true and fair accounts relating to remittance of initial corpus of buying and selling and realizing capital gains on investments and accounts of remittance to India for investment in India and realizing capital gains on investment from such remittances. The third principle suggests that ordinarily purchases and sales of shares with the motive of realizing profit would lead to inference of trade/adventure in the nature of trade; where the object of the investment in shares of companies is to derive income by way of dividends etc., the transactions of purchases and sales of shares would yield capital gains and not business profits.”
10. CBDT also wishes to emphasise that it is possible for a taxpayer to have two portfolios, i.e., an investment portfolio comprising securities which are to be treated as capital assets and a trading portfolio comprising stock-in-trade which are to be treated as trading assets. Where an assessee has two portfolios, the assessee may have income under both heads, i.e., capital gains as well as business income.
11. Assessing officers are advised that the above principles should guide them in determining whether, in a given case, the shares are held by the assessee as investment (and therefore giving rise to capital gains) or as stock-in-trade (and therefore giving rise to business profits). The assessing officers are further advised that no single principle would be decisive and the total effect of all the principles should be considered to determine whether, in a given case, the shares are held by the assessee as investment or stock-in-trade.
12. These instructions shall supplement the earlier Instruction no. 1827 dated August 31, 1989.
The most expensive part of a hospital bill may never touch the hospital at all.
A patient admitted for care has no way of knowing whether the price on a medical consumable reflects its actual cost or a markup fixed long before it ever reached the ward. That gap in information is, at its core, a public health issue.
A survey of hospital consumables in Maharashtra found an IV infusion set with a trade price of ₹11.05 carrying a printed MRP of ₹325 ; a markup of 2,841%. A syringe procured at ₹6.75 carried an MRP of ₹57.20. A catheter procured at ₹29.41 carried an MRP of ₹310.
These are not elective purchases. Patients cannot compare prices, seek alternatives, or question a number printed on a box while receiving care and the MRP itself is often fixed upstream by manufacturers and distributors, disconnected from the trade price by a wide, unexplained margin. The result is a system where the party bearing the cost has the least information to evaluate it.
The regulatory gap is structural: scheduled medicines are capped under the Drugs (Prices Control) Order, 2013. Most medical devices and consumables are not leaving both the pricing and the information around it almost entirely unmonitored.
A review of these findings and clear guidelines on the permissible gap between trade procurement price and declared MRP have been recommended to the Department of Pharmaceuticals and the NPPA ; a step toward closing not just a pricing gap, but the information gap patients are left to bear alone.
#PublicHealth #GoodGovernance #Leadership #TukaramMundhe
https://t.co/Ye9CVzr8qU
@wittysiddharth But if you have a REAL friendship, why would it bother you that he doesn't throw a bday party on his kid's bday? Why wud u not invite him? If he had thrown a party and now invited you, it wud hv been a different case. But he never gave a party! Why this kolaveri di?!
@ankitdewan@wittysiddharth Ditto!
Sailing in the same boat...
I would rather make memories with my family and give exposure to my kid, then spend recklessly at another play area!!
cancer treatment in 2025:
find the tumor, cut it out, poison the rest with chemo, hope the patient survives
cancer treatment in 2026:
sequence the tumor's DNA, identify the exact mutations driving it, design a treatment built around those mutations specifically, train the patient's own immune system to hunt them down
it's coming fast, bio/acc.
• Antibiotics destroy the gut.
• Birth control destroys the gut.
• NSAIDs destroy the gut.
• Omeprazole and Tums destroy the gut.
• Chronic dieting destroys the gut.
• Ultra-processed foods destroy the gut.
• Mold and toxins destroy the gut.
• Chronic stress destroys the gut.
• Poor sleep destroys the gut.
• Processed supplements destroy the gut.
• Unregulated peptides destroy the gut.
• Constant caffeine destroys the gut.
• Artificial sweeteners destroy the gut.
• Plastics and chemicals destroy the gut.
• Seed oils destroy the gut.
• Sugar spikes destroy the gut.
• Sedentary habits destroy the gut.
And we are still wondering why autoimmune rates, thyroid disorders, infertility, cancer, heart disease, anxiety, depression, obesity, and chronic fatigue keep skyrocketing.
Root cause care is no longer optional.
It is the blueprint for survival in a world that is pushing the human body past its biological limits.
Too many DMs so below is the email template I sent to:
HDFC Bank: [email protected]
ICICI Bank: [email protected]
SBI: [email protected], [email protected]
Axis Bank: [email protected], [email protected]
YES Bank: [email protected]
Template:
Subject: Request for Home Loan Interest Rate Revision – Account No. [Loan Account Number]
Dear Home Loan Team,
I am writing to request a formal review and downward revision of the interest rate on my home loan (Account No. [Loan Account Number]).
I have maintained a consistent, spotless repayment track record since the inception of my loan. Additionally, my credit standing remains strong, with a current credit/CIBIL score of [Your Credit Score, e.g., 800+]. In light of my clean repayment history and current prevailing market rates, I request that my interest rate be reduced to align with competitive benchmark offerings.
Regarding the terms of this rate revision/conversion, I have specific requirements:
- Maintain Monthly Outflow: I would like to keep my current EMI amount of [₹ Current EMI Amount] unchanged.
- Tenure Reduction Objective: I request that the financial benefit of the revised interest rate be applied directly toward reducing my remaining loan tenure, rather than lowering the EMI.
- Confirmation Against Tenure Reset: Rate revision processes occasionally trigger an automated reset of the loan tenure back to the original sanctioned term. I strictly do not consent to any tenure reset or extension. The revised tenure must be recalculated strictly against the current outstanding principal and remaining balance.
Kindly share the applicable revised rate, any associated processing/conversion fees, and written confirmation that the loan tenure will not be reset to the original sanctioned period before processing this request.
Thank you for your assistance. I look forward to your prompt response.
Warm regards,
[Your Full Name]
[Your Contact Number]
[Your Registered Email Address]
Like, share and report if it helped you.
Food Commodities
Dry Fruits, Soyabean & Corn Prices are rising up from the last few weeks
Next leg of big move is expected in companies which are in a business of these Commodities
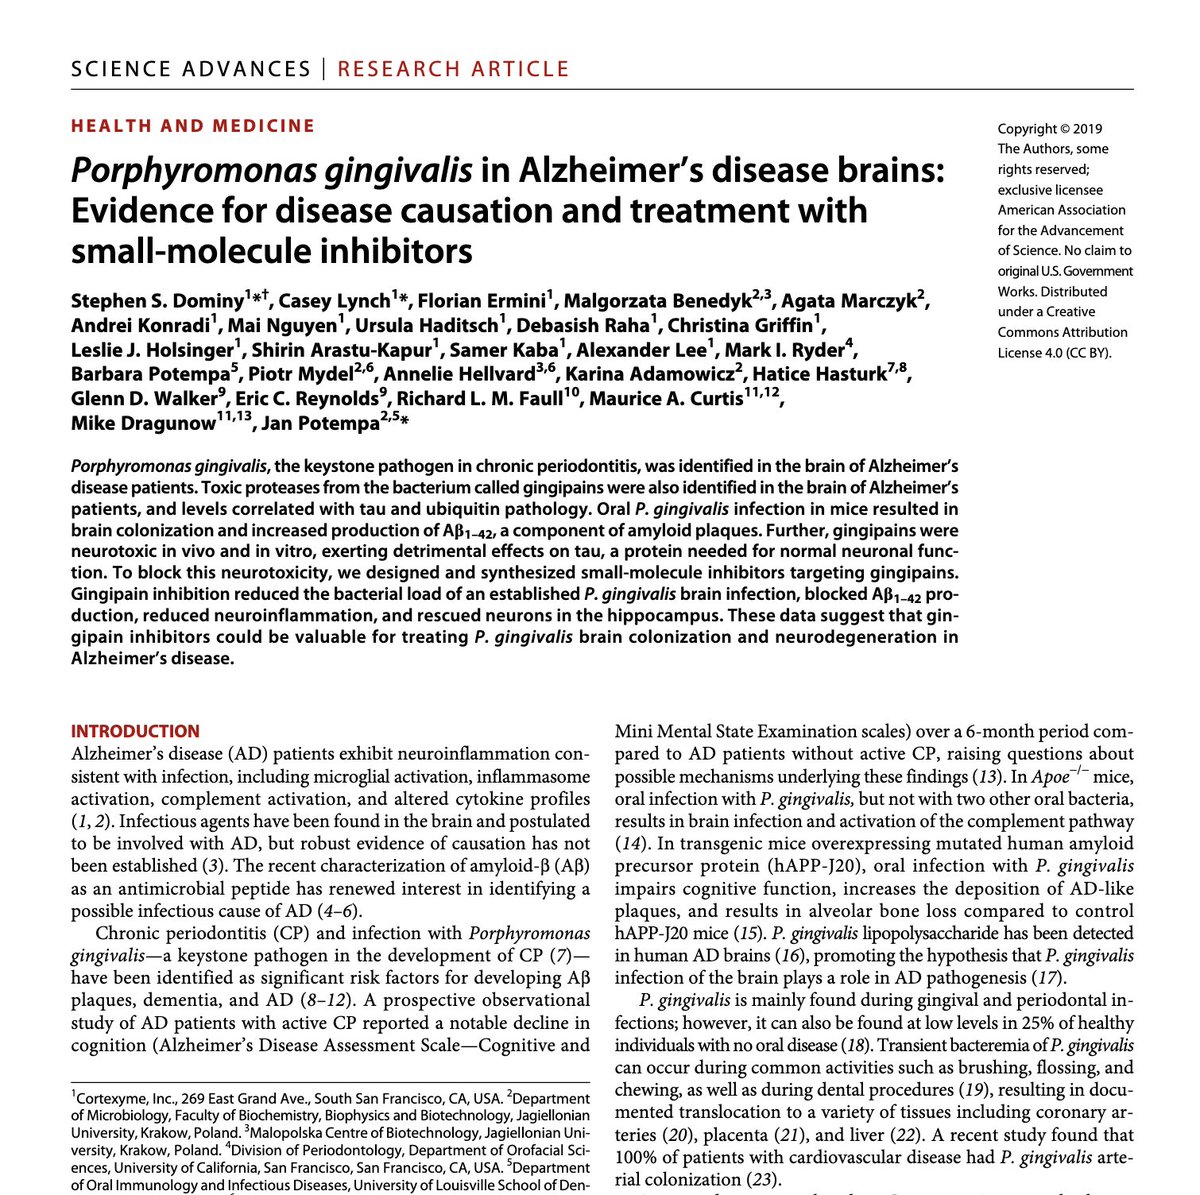
Researchers cut open the brains of Alzheimer’s patients and found a bacteria living inside 90% of them.
It’s the exact same bacteria that lives in your mouth right now.
For decades, medicine treated Alzheimer’s as an unavoidable genetic flaw or a random protein glitch.
The leading theory blamed "amyloid plaques”, sticky protein buildups that choke off brain cells. Big Pharma spent billions trying to destroy these plaques.
Almost every single drug trial failed.
A groundbreaking study published in Science Advances revealed why.
The protein plaques aren't the primary cause of the disease.
They are the brain's desperation defense mechanism against an invader.
The culprit is Porphyromonas gingivalis, a common bacterium that thrives in infected gums.
When your gums bleed, the bacteria enters your bloodstream. Over years, it breaches the blood-brain barrier and secretes toxic enzymes called gingipains.
These toxic enzymes literally slice up brain tissue, destroy neurons, and trigger devastating memory loss.
To defend itself, the brain produces amyloid proteins to trap the bacteria.
We weren't looking at the cause of Alzheimer's.
We were looking at the crime scene aftermath.
When researchers infected healthy mice with the gum bacteria, the mice developed brain infections, amyloid plaques, and rapid neural damage.
When they gave the mice a targeted drug to block the bacterial enzymes, the brain infection cleared, neuroinflammation dropped, and dying neurons were rescued.
Alzheimer’s may not be an irreversible decay of the mind.
It might be a chronic bacterial infection we’ve been ignoring for decades.
The solution to one of humanity's most terrifying diseases might not start in a neurology ward.
It might start in your mouth.
Indian fathers with 30 years in manufacturing are committing a massive generational mistake of funding sterile retail showrooms for their Gen Z kids just to protect them from the factory floor.
Every 24 year old today wants to launch a D2C retail brand from an air conditioned coworking space. They want the pastel packaging, the Shopify dashboard and the Instagram storefront so they can call themselves a Founder in front of their friends.
They are completely allergic to the sweat, the noise, the labor management and the boring daily grind of actual production.
If 99% of this generation is busy fighting over retail margins, customer acquisition costs and Instagram likes. who is actually making the product?
I am in manufacturing and looking around the floor, there is rarely a single person in their 20s willing to operate in the dirt. Everyone wants to sell the product but nobody wants to endure the friction of building it.
The 1% of Gen Z kids who swallow their ego, abandon the cafe aesthetic and build a boring & unglamorous manufacturing line are going to absolutely crush this entire generation.
Mark my words “Manufacturing in india is biggest opportunity of this generation”
You can keep your cute D2C retail brand. The guy grinding on the factory floor is going to end up owning your entire supply chain.
THE JAPANESE METHOD OF RAISING CHILDREN WHO LISTEN THE FIRST TIME.
By age, from Japanese practice:
1. They keep their voice low, especially when the child is loud.
One of the best recent podcasts on AI. Neil has a gift for explaining all of the jargon and insights simply.
(I’m not involved, just found it unusually educational).
Subhash Chandra just settled ₹22,006 crore of admitted claims for ₹6.5 crore.
That’s a 99.97% haircut.
You’re out here refreshing CIBIL after one late credit-card payment like it decides your citizenship.
Same banks.
Same country.
Two different recovery manuals.
Moral of the story:
CIBIL is only mandatory if your debt is small enough to collect.
#CIBIL #NCLT #HaircutEconomy #subashchandra #zeetv
“At each of the last 40 Dhanteras, if you bought 10 grams of gold, you would have accumulated 400 grams of gold. Your total investment would have been around Rs. 8 lakh.”
“But if you had divided that Rs. 8 lakh into 40 equal amounts Rs. 20,000 every year and invested that fixed amount in gold, you would have accumulated around 1,111 grams of gold instead of 400 grams.”
“Why? Because in the first case, you bought a fixed quantity at changing gold prices. In the second, you invested a fixed amount, buying more gold when prices were lower and less when prices were higher.”
“This is the power of SIPs and rupee-cost averaging. The problem? It’s too simple. And human beings don’t like simple things.” 😄
- Vijai Mantri