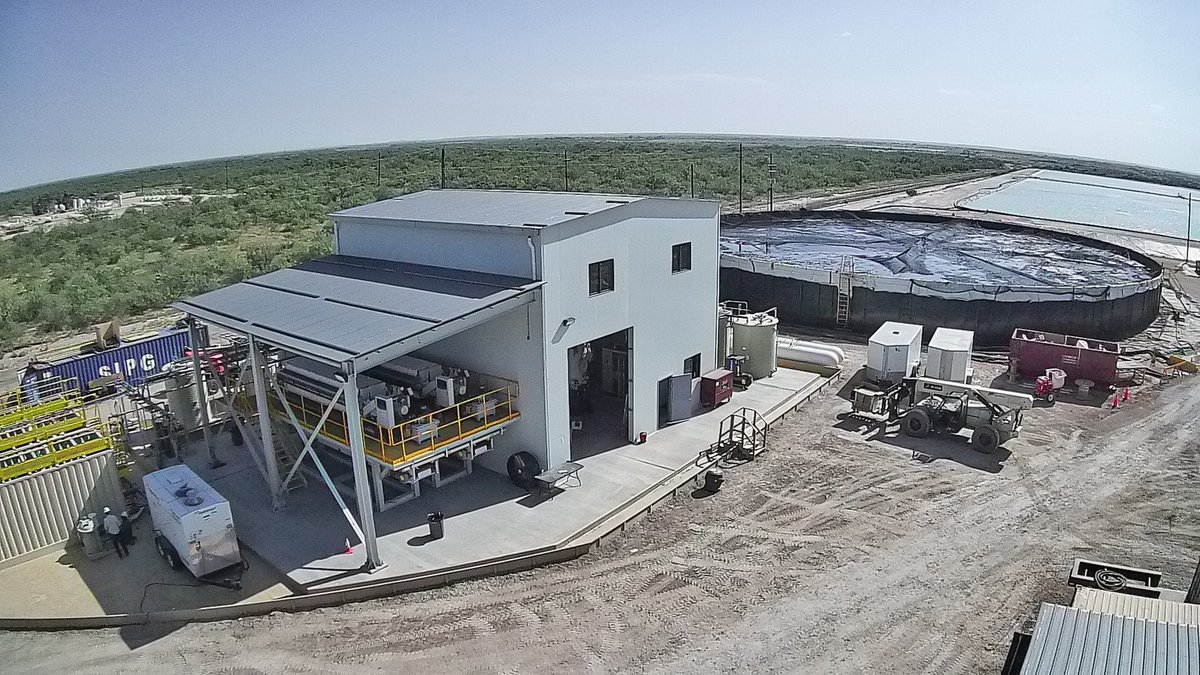
$LIB.V / $VLTLF is being priced like a science project that only works in the lab, and this could not be further from the truth.
They're producing 99.7%+ purity lithium at their Freedom Launchpad field platform, they've signed their first 600tpa offtake agreement, and they've signed a term sheet for up to US$95M in project financing. And they're about to become one of the first DLE lithium producers in North America, at a time when domestic supply has never been more strategic.
The gap between the price and the value is the entire thesis. 🧵
$LIB.V / $VLTLF LibertyStream just postponed its shareholder meeting from October 15 to late November, with only six days notice.
I recently received the proxy materials in the mail, with all dates slated for October 15th, meaning that they were confident enough that they spent money and printed everything, which they have committed to resend out again, so something important must have caused this last minute change.
What’s interesting is that the company says it's so shareholders can see “business updates” prior to the meeting.
My honest thoughts: either a deadline, like an offtake or midstreamer agreement slipped, or something potentially significant just popped up that they didn’t want investors to miss before the meeting. Your guess is as good as mine for which one it is, but only time will tell. Curious to hear everyone’s thoughts on this.
@LongGameEquity Share buy backs, because dividends are cool but what if the underlying stock loses so much value that the dividend doesn't even matter? Plus, buybacks indicate that management is dedicated since they think the company is undervalued
People like to compare investing with gambling, which I completely disagree with. But all of the things mentioned above help to blur the lines between investing and gambling, which is unfortunate because it prevents people from studying and getting better and instead promotes reckless actions
$LIB.V / $VLTLF produce DLE lithium from oilfield brine, first 1,000 tonne per annum commercial plant under construction targeting end of 2026, 600 tpa offtake already signed.
Current market cap ~C$212M, my bull case (assuming US$25k spot price) is ~US$450M on 4 modules, about 3x from here. Assuming each module costs ~US$37M capex at ~US$6.2k/t.
The mispricing: its trading on the TSX Venture exchange and the Nasdaq uplisting hasn't happened yet (confidential S-1 filed August, targeting Q4). Also execution risk from the pilot plant to commercial plant.
I am long, NFA.
@tradesbymustii I have told myself I will always leave dry powder since good opportunities always come along, but it’s so hard because every time I think it can’t get any better, but usually there always ends up being a better entry
@haydeninvestsX I would agree but sometimes I’ve seen instances where good news is announced, the stock rips, and then bad news like dilution is announced shortly after. In that case the fade was because of insiders unloading. Hopefully you just got a bargain, best of luck!