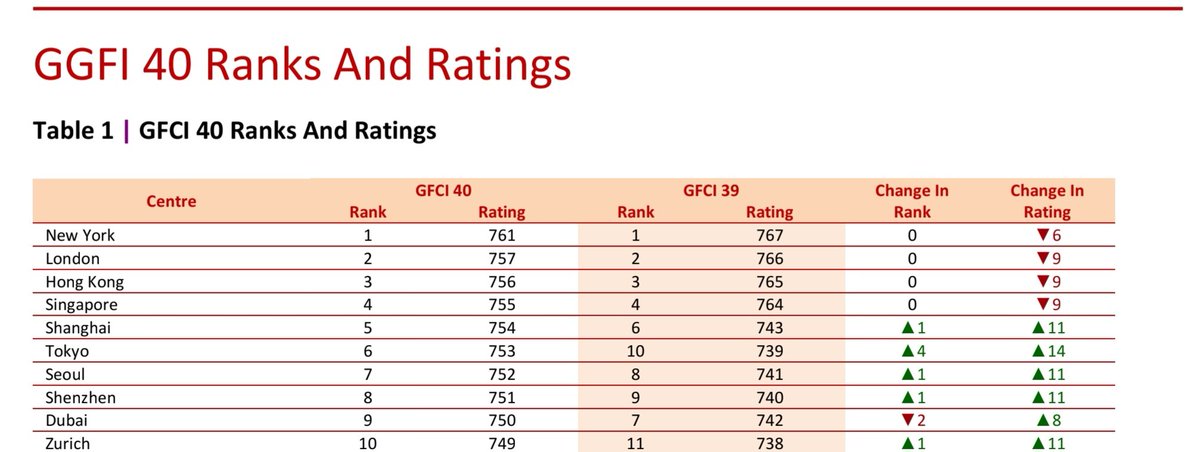
@AlanJLSmith Looking at the September 2026 Global Financial Center Index, London still ranks 2nd globally, just behind NYC, as it has done for years/decades. IPOs are just one amongst many indicators, and not even a particularly important one.
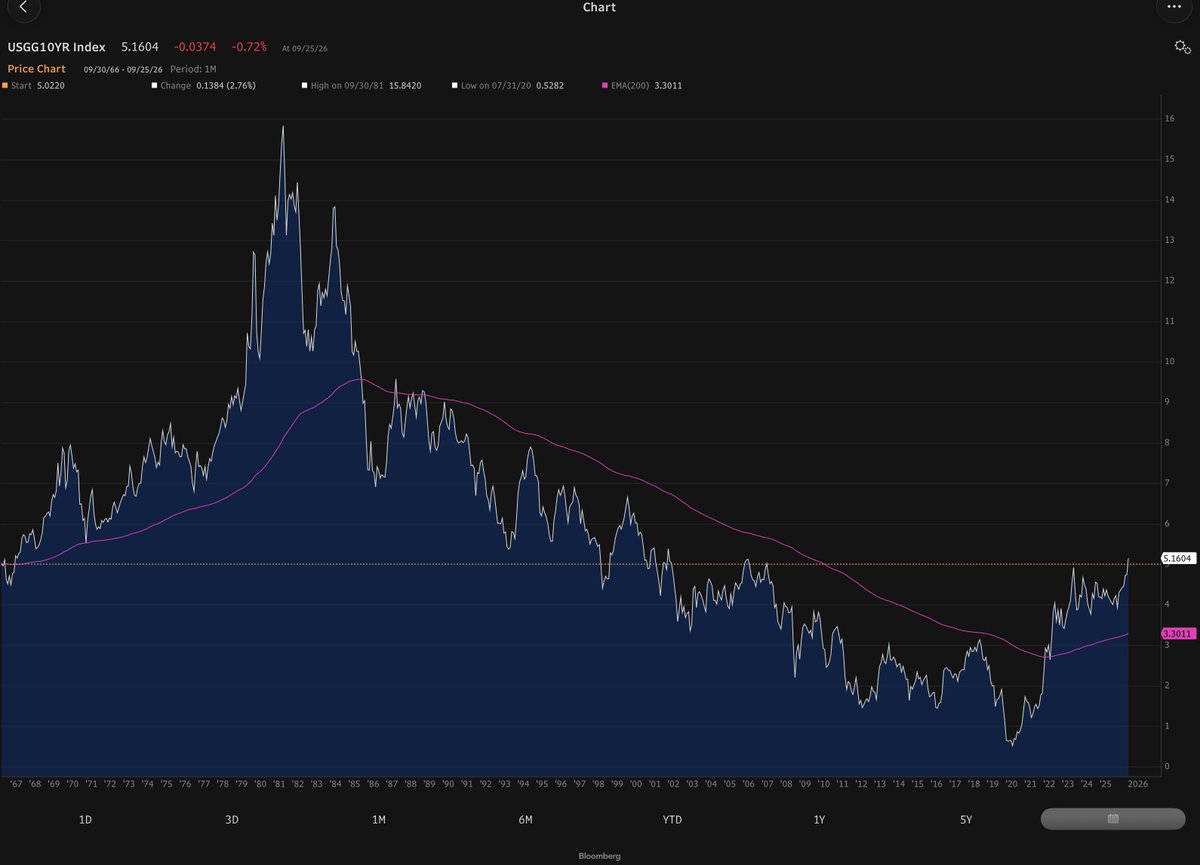
@Justdoitalex Is the reason things are supposedly "breaking", that yields have reached levels they have been at in the early 2000s (and much higher for much of the prior decades)?🙂
@robin_j_brooks No, but 1) there is a global oil/gas/inflation shock driving ST rates. And 2) w/ the (AI-driven) growth resilience in the US this leads to higher expected policy rates which leads to higher UST yields which are well known to have significant spillovers to global ex US yields.
@Mr_Derivatives Yeah, people sometimes forget what a volatile thing the ERP is. 19.3% standard deviation in the US since 1900. Higher than World ex-US. And longest period of negative real returns for US equities over that period is 16 years...
@izakaminska@PeterMcCormack Risk-free means credit risk-free. No one ever said that duration wasn't a risk, which is why the risk-free rate is often proxied by (secured) overnight ratesand not by a 100Y sovereign bond. It's not that complicated.
@Handre Completely wrong. The Schaufenstereffekt was a dishoarding of goods due to Allied currency reform. Most prices (basic food, rent, coal, energy) stayed controlled and wages remained frozen until November 1948.
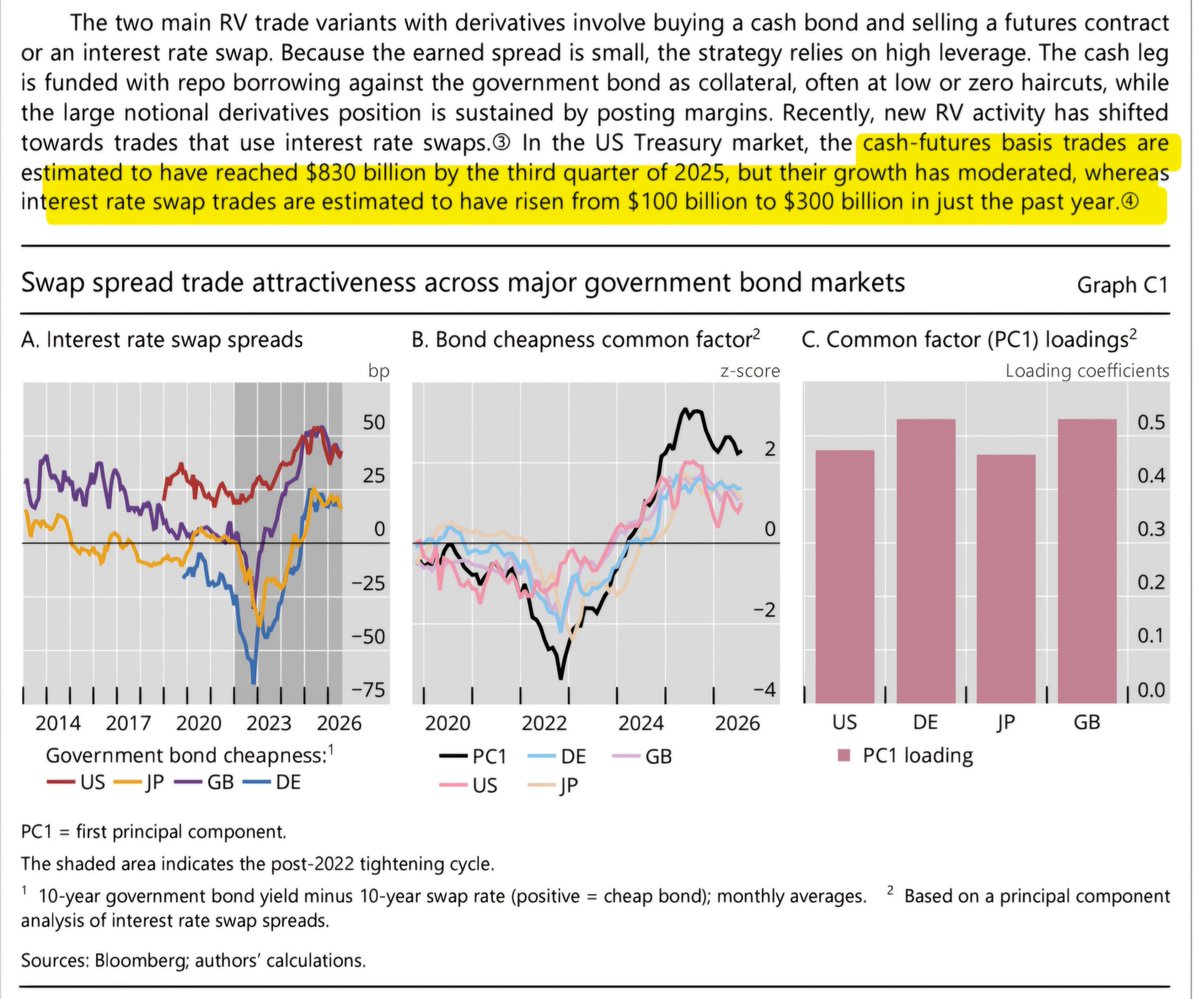
@staylorish@DEhnts You are exactly right. This growth in UST holdings by RV funds is due to the huge size (and growth of) basis trades and IRS trades, which combined are >$1tn. Has nothing to do with hedge funds betting on lower yields.
@robin_j_brooks Robin, Germany's CA surplus vs. other EA countries has been mentioned already, but wouldn't you agree that this is also due to APP and PEPP instead of "German altruism"? NCBs in the EA buying EGBs from international investors, who hold those in Germany?
@adam_tooze@michaelxpettis Adam, would you say if EA instead absorbs the Chinese surplus, a ESDC repeat could be on? EA CA deficit financed by fragmented national bonds leading to spread widening? China playing the role German surpluses played back then?
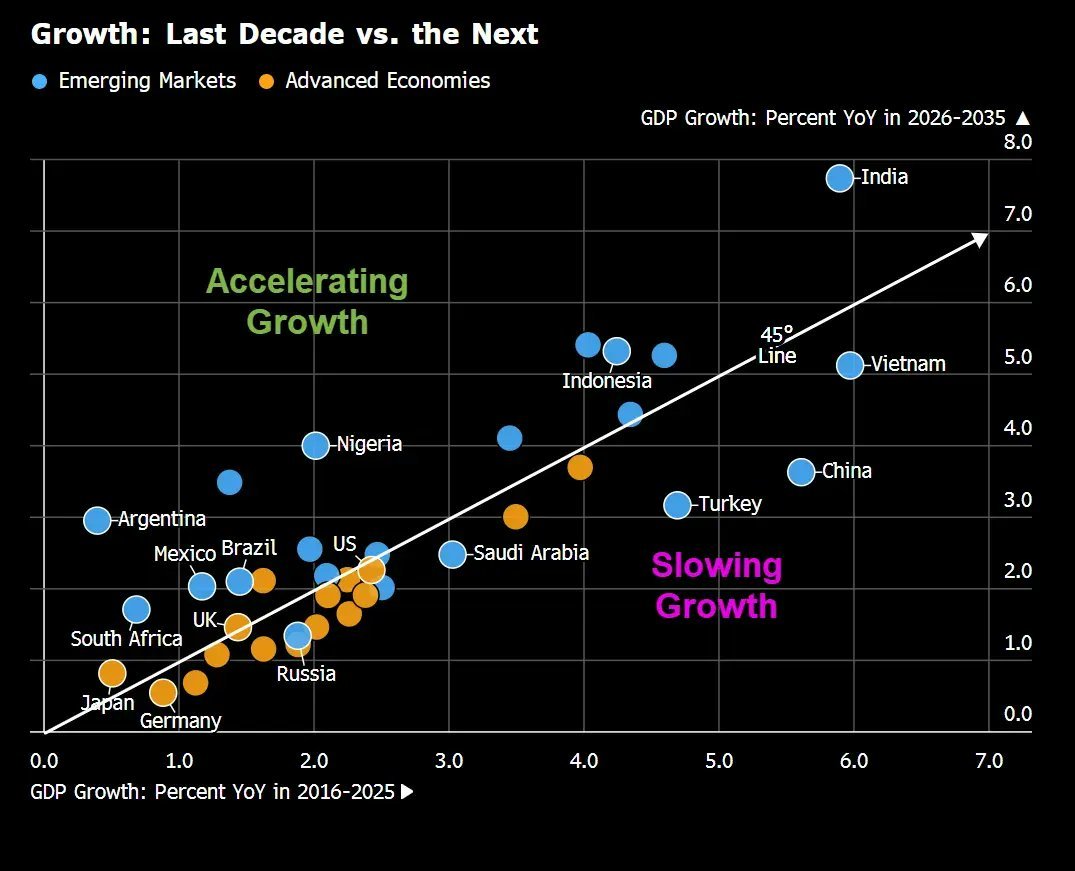
Someone should show this to the public figures claiming that we are seeing a "massive increase in term premia globally" due to "deteriorating fiscal positions". The changes in recent weeks might have more to do with e.g. upward revisions to growth.
@robin_j_brooks Looking at shorter- instead of longer-term and real instead of nominal yields changes the picture. 3Y real rate differentials have widened (in favor of the US) 100 bps since February-end, alongside the JPY depreciation.