On day one, the risk model and the book agree completely. After that? Drift.
A tiny 0.44% slice of an auto portfolio defaulted at 50% vs a 20% baseline while top-level metrics reported calm.
Spot velocity shifts before repricing turns into charge-offs ⤵️
https://t.co/FTkOsBXN2I
Faster loan decisions won't save a broken credit model, they just scale mispriced risk at 10x the speed. 🚗📉
Why "instant AI approvals" are quietly eroding auto portfolio P&Ls, and what to verify before your next tech RFP:
Full breakdown 👇
https://t.co/kvp68qlykd
Your charge-off report isn't a forecast, it's a 24-month-old postmortem.
Standard scorecards hide toxic sub-segments inside stable portfolio averages until collateral cushions are already gone.
Here's how to spot the driver signals 6–12 months earlier:
https://t.co/mMySt8sln8
Congress overturned the CFPB’s dealer markup guidance, but ECOA never left.
If your pricing committee only monitors rate sheets, you're missing the spread between buy and contract rates.
That markup is a price your sheet never set 👇
https://t.co/QjmrUDQLWK
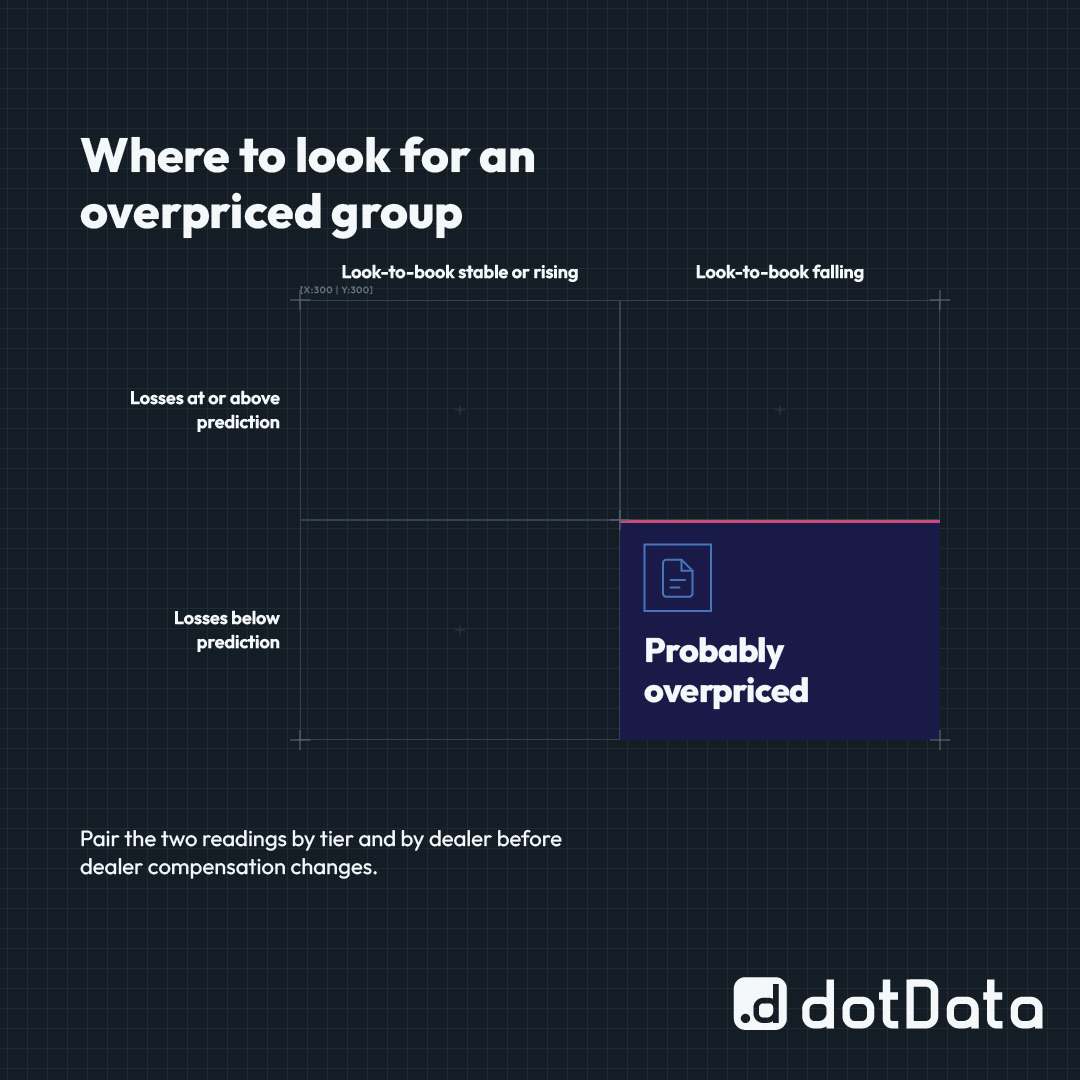
Auto delinquency hit 3.00% in Q2 2026. Cutting broad near-prime rates to defend volume without loss visibility compounds risk, your churners & charge-offs aren't the same borrowers.
See how granular segment data replaces guesswork ⤵️
Headline bank NIM hit 3.32% in Q2 (+6 bps YoY), but don't let that fool you, auto spreads moved the opposite way.
A strong total NIM easily masks narrowing auto loan margins.
Here’s how to separate the two before portfolio yields take a hit ⤵️
#AutoLending#dotData
We’re excited to share that dotData was recently featured in AutoFin Journal, offering strategic guidance on how auto lenders can safely deploy AI without exposing their portfolios to hidden credit risks or regulatory penalties.
Check out featured articles in the thread below 👇
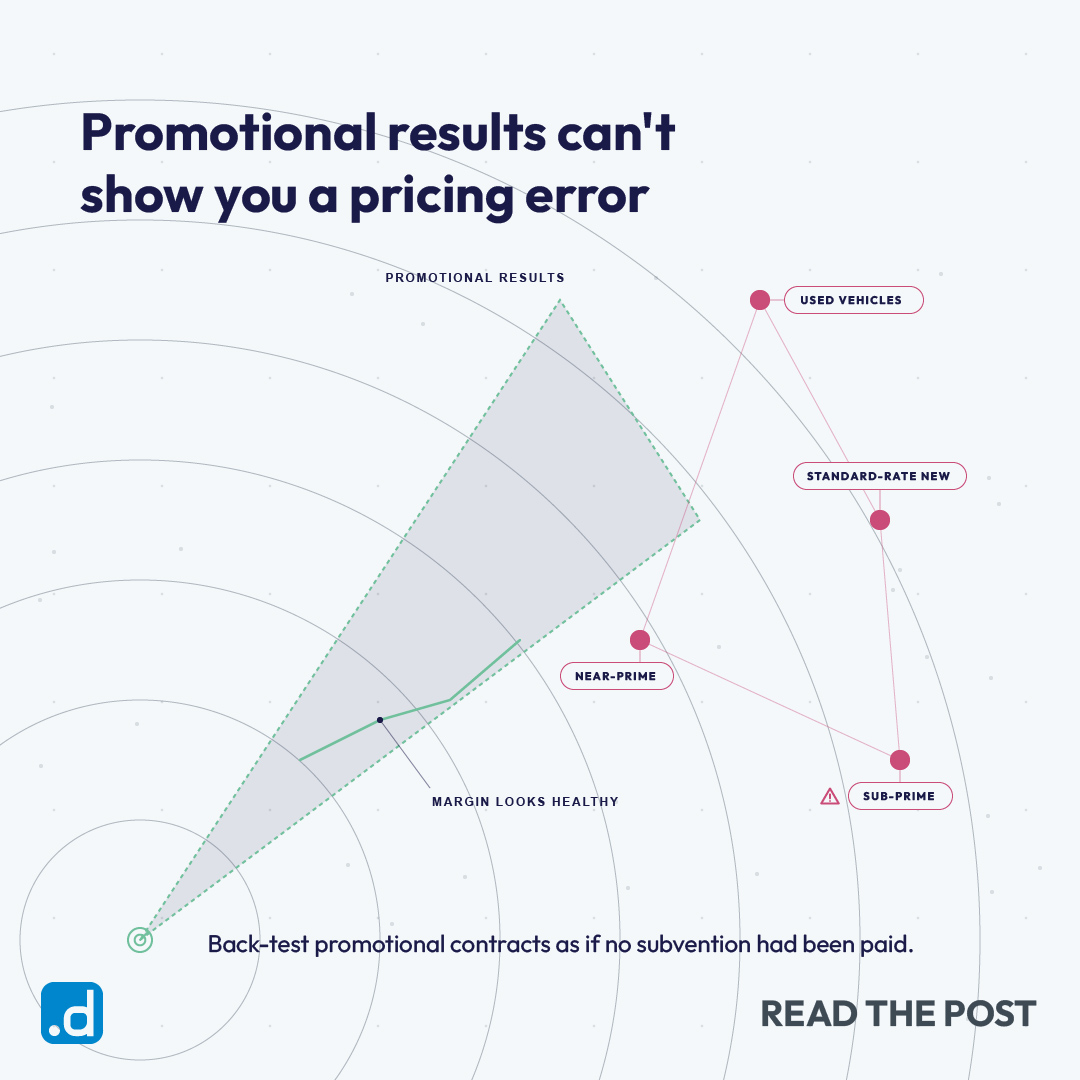
Subventions hide bad pricing. A promo contract looks profitable only because the manufacturer pays the gap.
The test: back-test promo loans without subventions to find underpriced tiers, the same ones pricing today’s standard book.
Read the analysis ⤵️
#Lending#RiskManagement
Blended averages hide major auto lending risks. Prime 60+ DPD is 0.42% vs subprime at 6.90%, a 15x risk gap lost in portfolio averages.
Is your software missing critical risk signals?
Read how to spot flaws in your next vendor demo 👇
https://t.co/QexCBah8mP
Yokohama Rubber and dotData Begin Joint Development of an AI Agent for Manufacturing R&D
Read the announcement 👇
https://t.co/74qI3Tm2i5
#Yokohama#dotData#AIAgent#AIforManufacturing