The $SOFI debate isn’t really $30 vs $130.
The bigger question is what EPS looks like once the newer businesses have 12–18 months to mature.
$1 EPS × 35 = $35
$2 EPS × 35 = $70
$3 EPS × 35 = $105
Same multiple. Completely different outcome.
Curious where you land on the 2029 framework now @Tim_Sweeney_TAR @Jbird00427 👀
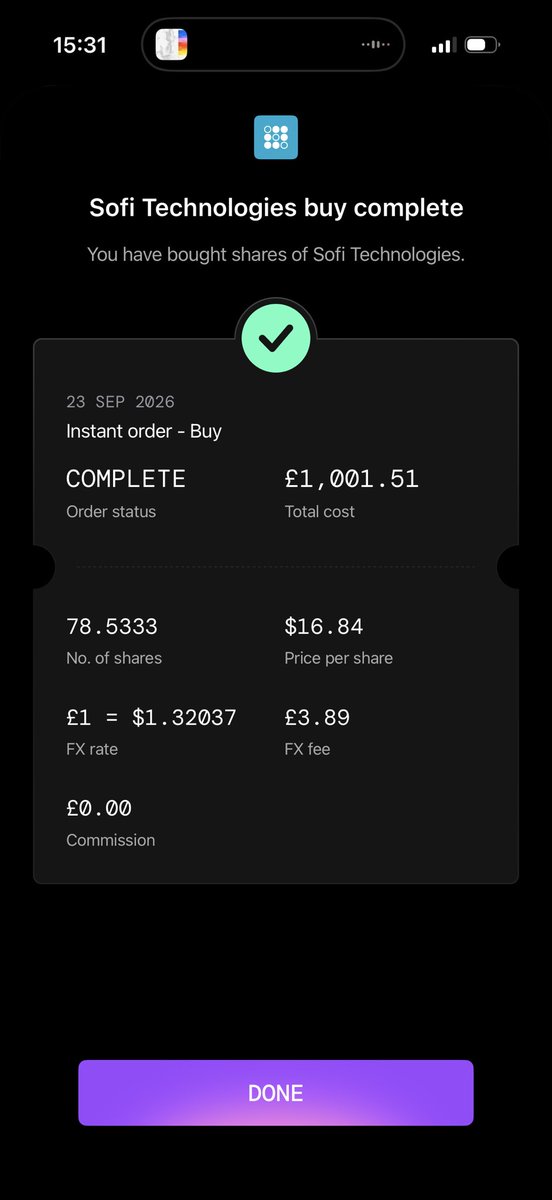
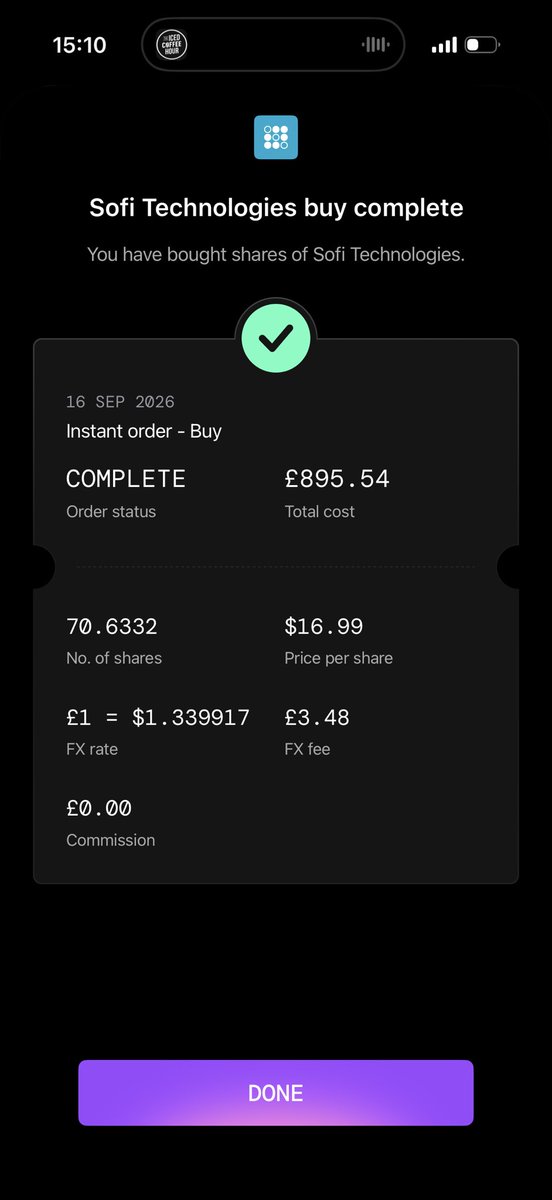
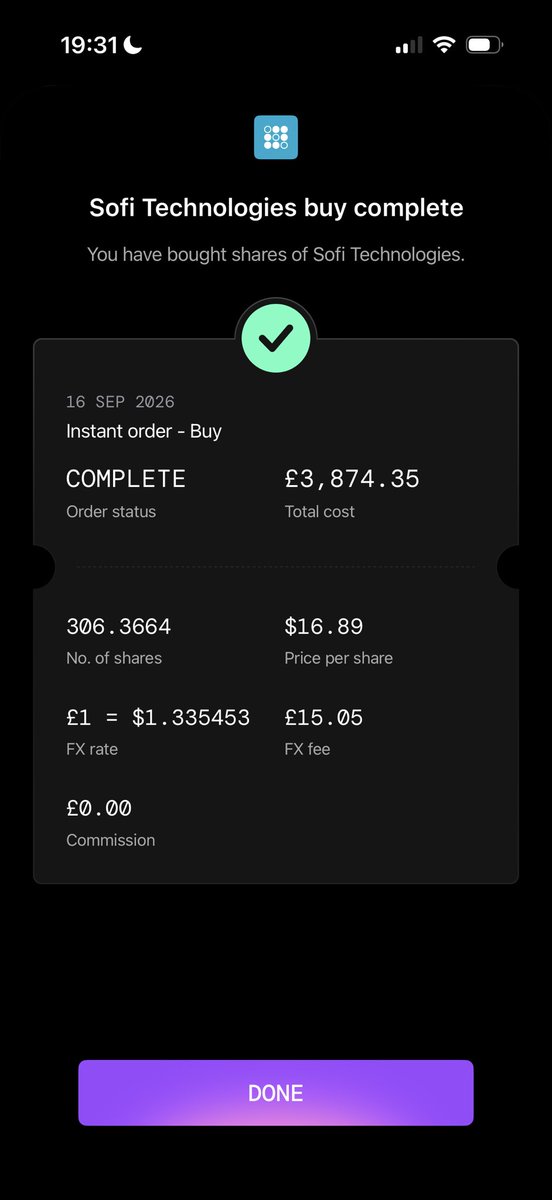
Receipts over hype.
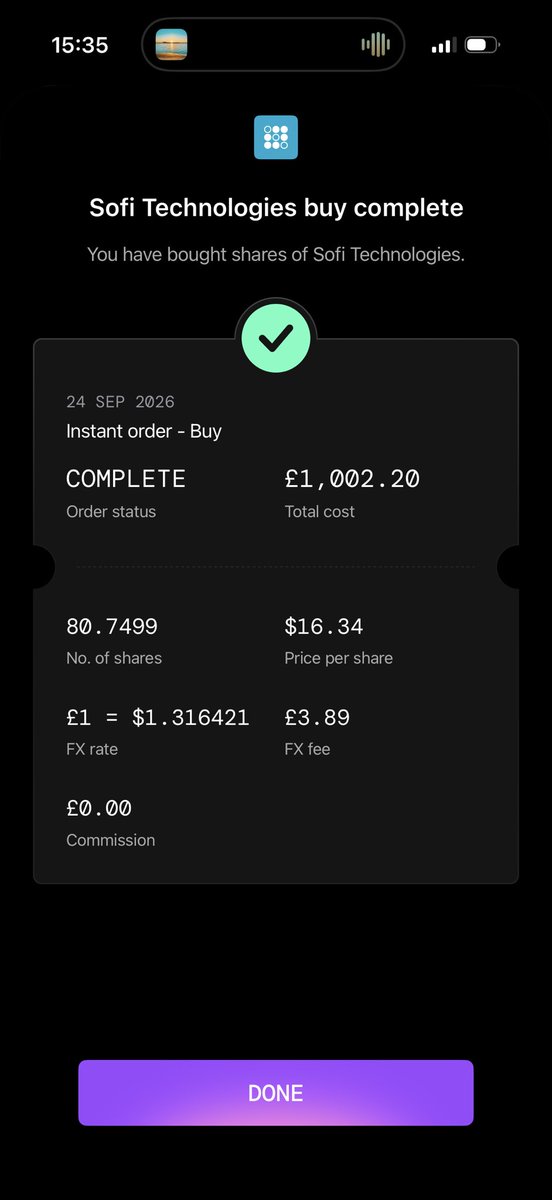
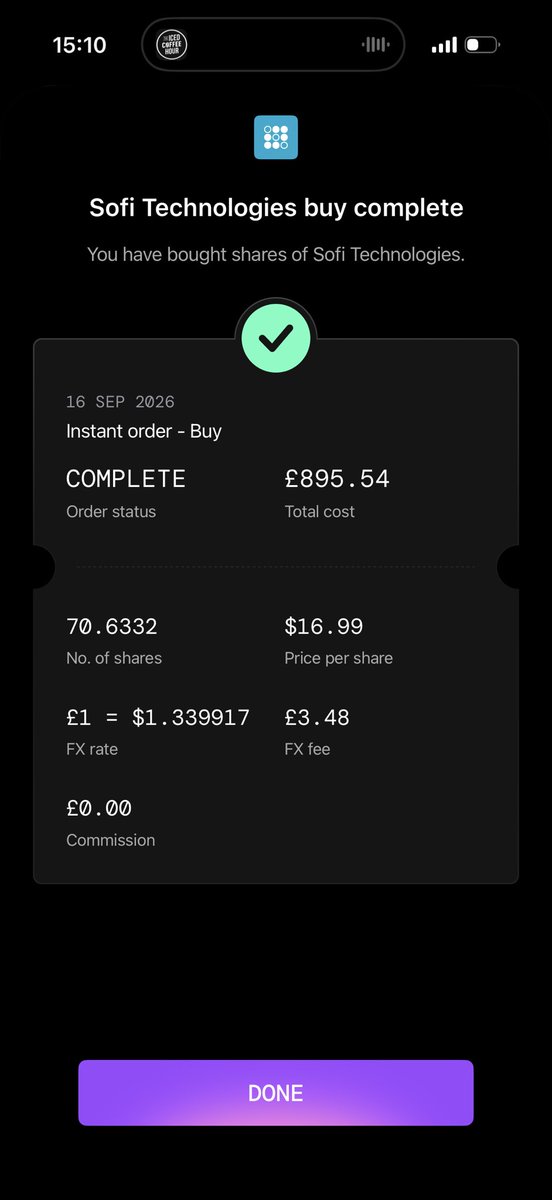
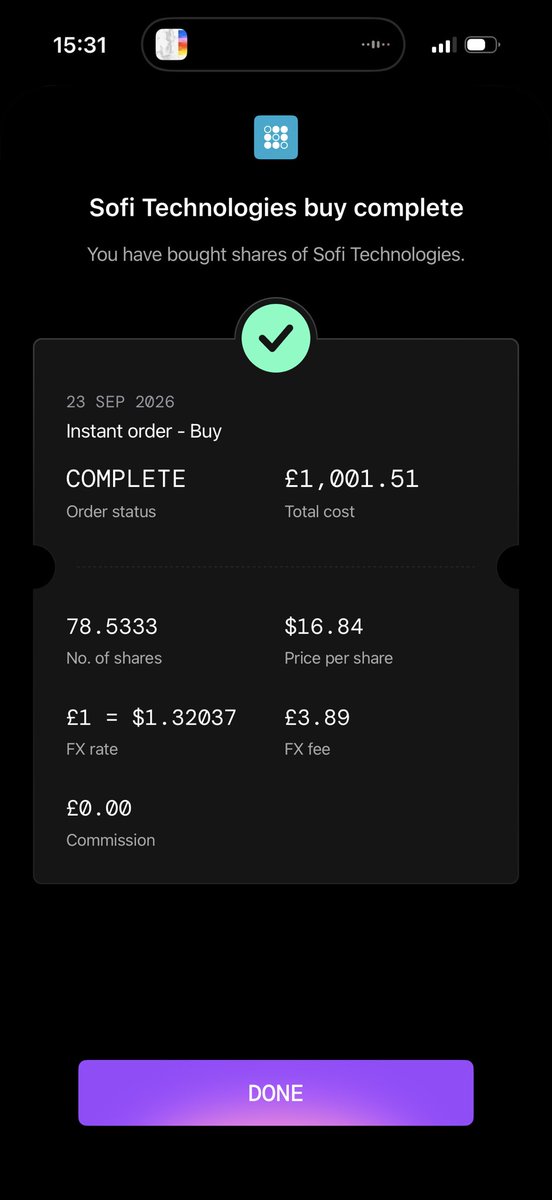
$SOFI add @ $16.34
25x on $0.60 = $15.
35x = $21.
I’m $1.34 above the bank case.
I still added.
Would you wait for $15
or buy $16 because $21 still works?
@UltraVested@Tim_Sweeney_TAR $25 on 2027 at 30x is a different year.
I mark 2026: $0.60 × 35x = $21.
If $0.84 prints in 2027, $25 is fair.
I added $17 on the 2026 number.
$SOFI is $17.
I use $0.60 2026 EPS × 35x = $21.
Two separate risks:
Tax stays 21% → $0.60 might not print.
It’s just a lender → 25x / $15.
I added $17 assuming fee mix holds and EPS is close to $0.60.
Which breaks first - the tax line or the multiple?
@Tim_Sweeney_TAR
@stevenfiorillo $25B of card volume on-chain is infrastructure.
It’s not $21 by itself.
Throughput ≠ fee mix.
I added $17 because 35x on $0.60 still works if this becomes fees.
If it’s just rails with thin take-rate, it’s a 25x bank.
I think this is too simplistic.
“Rates ease and SOFI works” isn’t really the thesis.
Banks make money on the spread between what they earn on assets and what they pay for funding.
If rates rise, asset yields can rise too - and the impact depends on how quickly deposits/funding costs reprice.
For $SOFI, I’m watching NIM + funding mix + EPS, not just the direction of rates.
That’s a much more interesting debate.
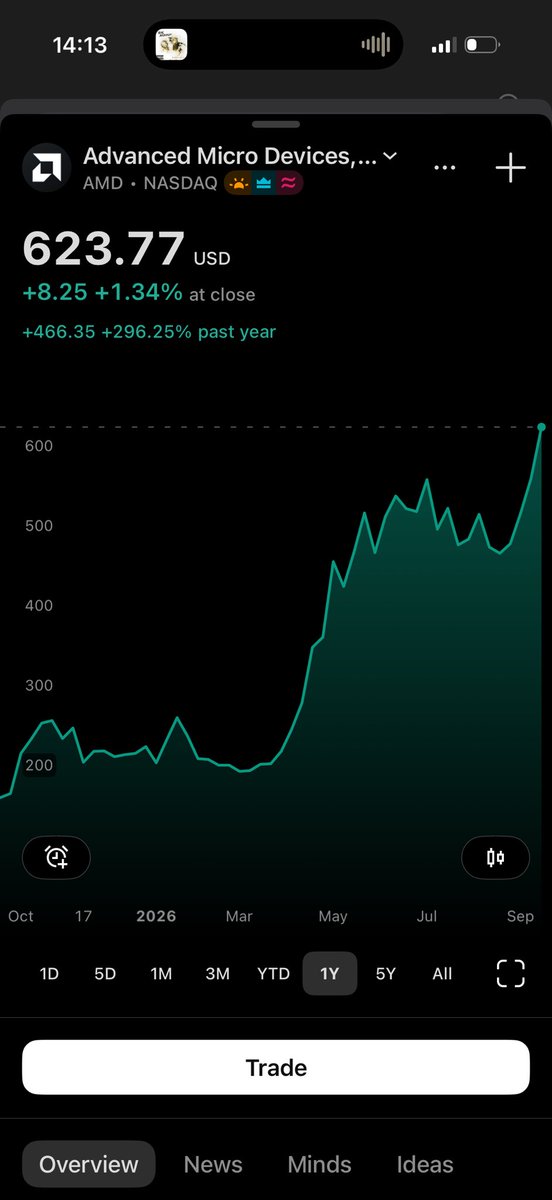
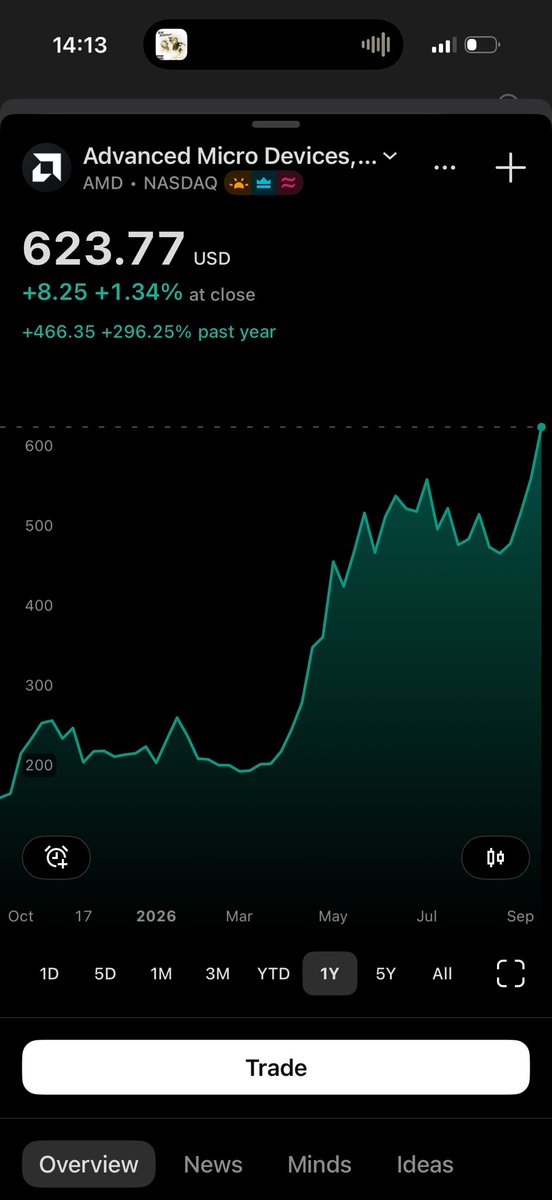
$AMD is running.
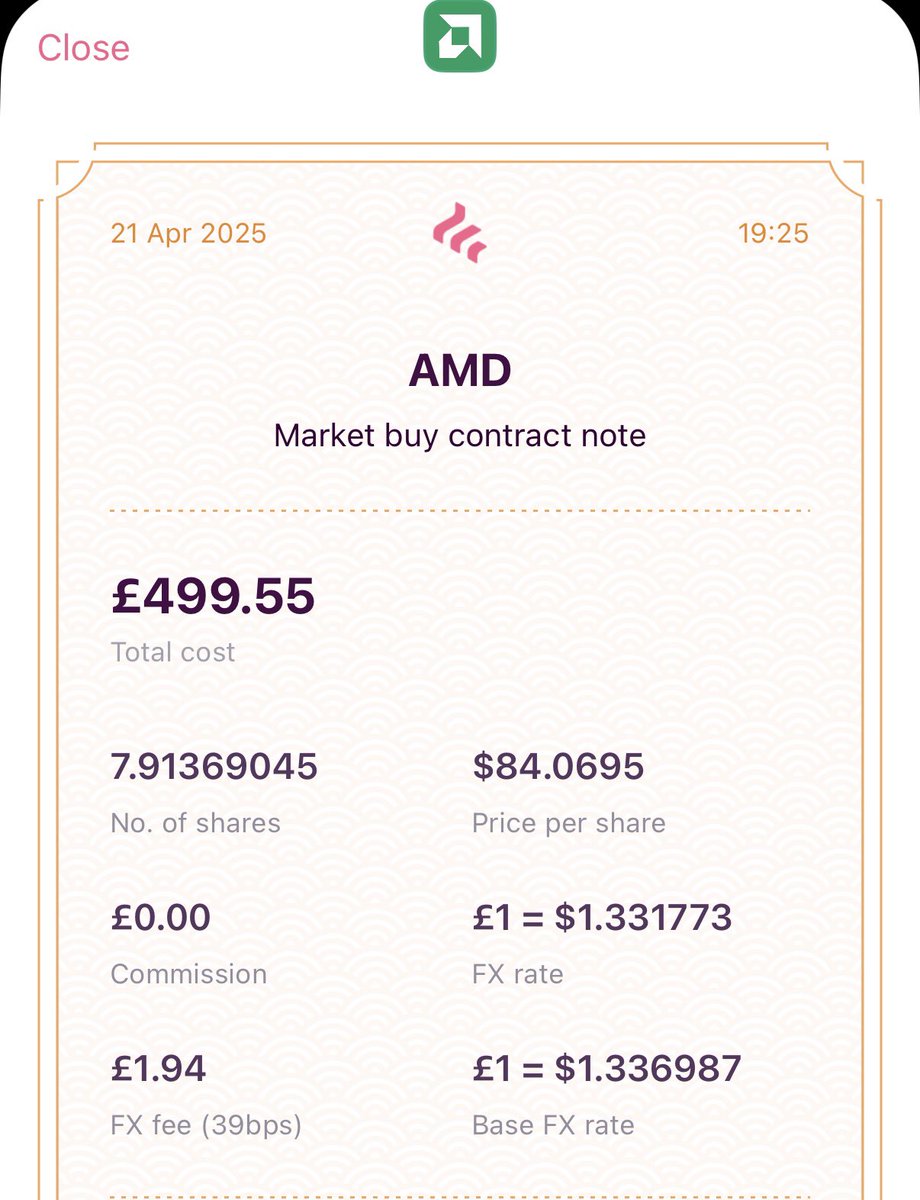
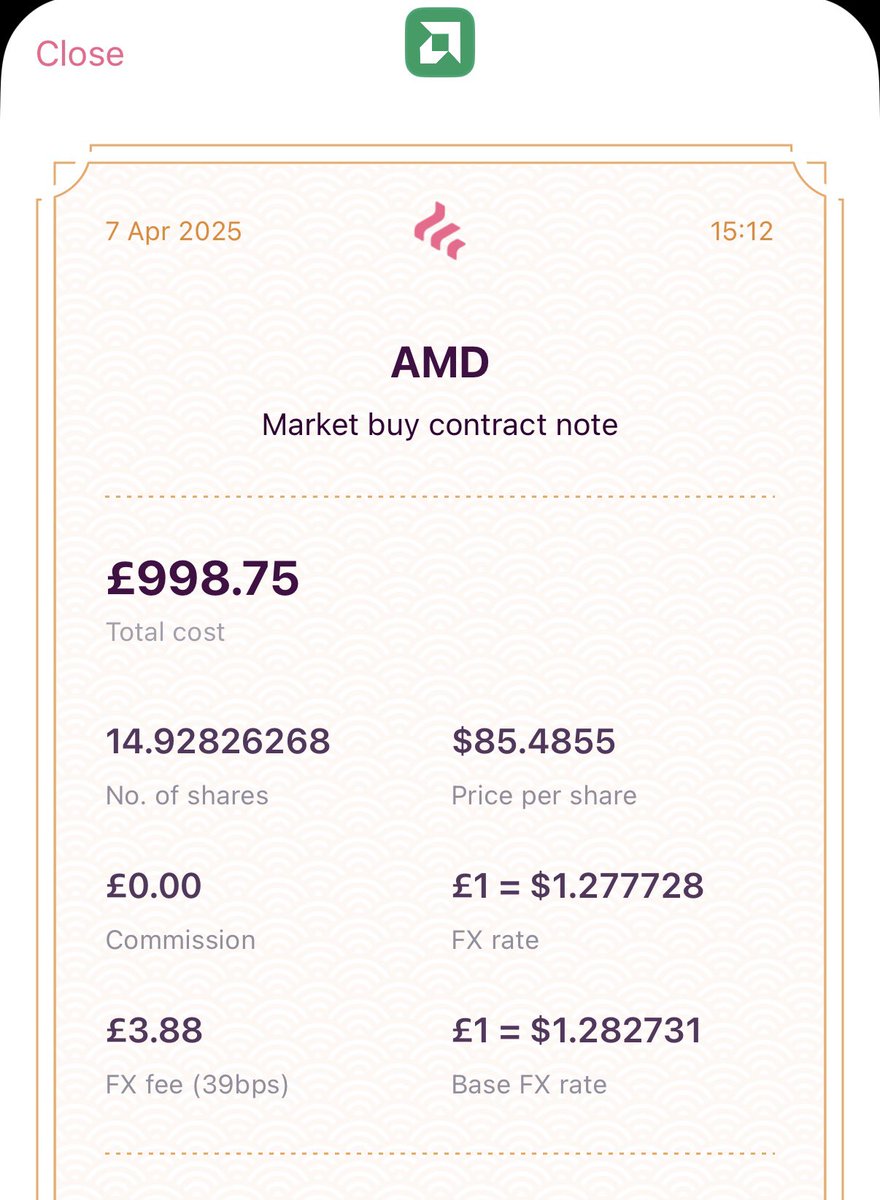
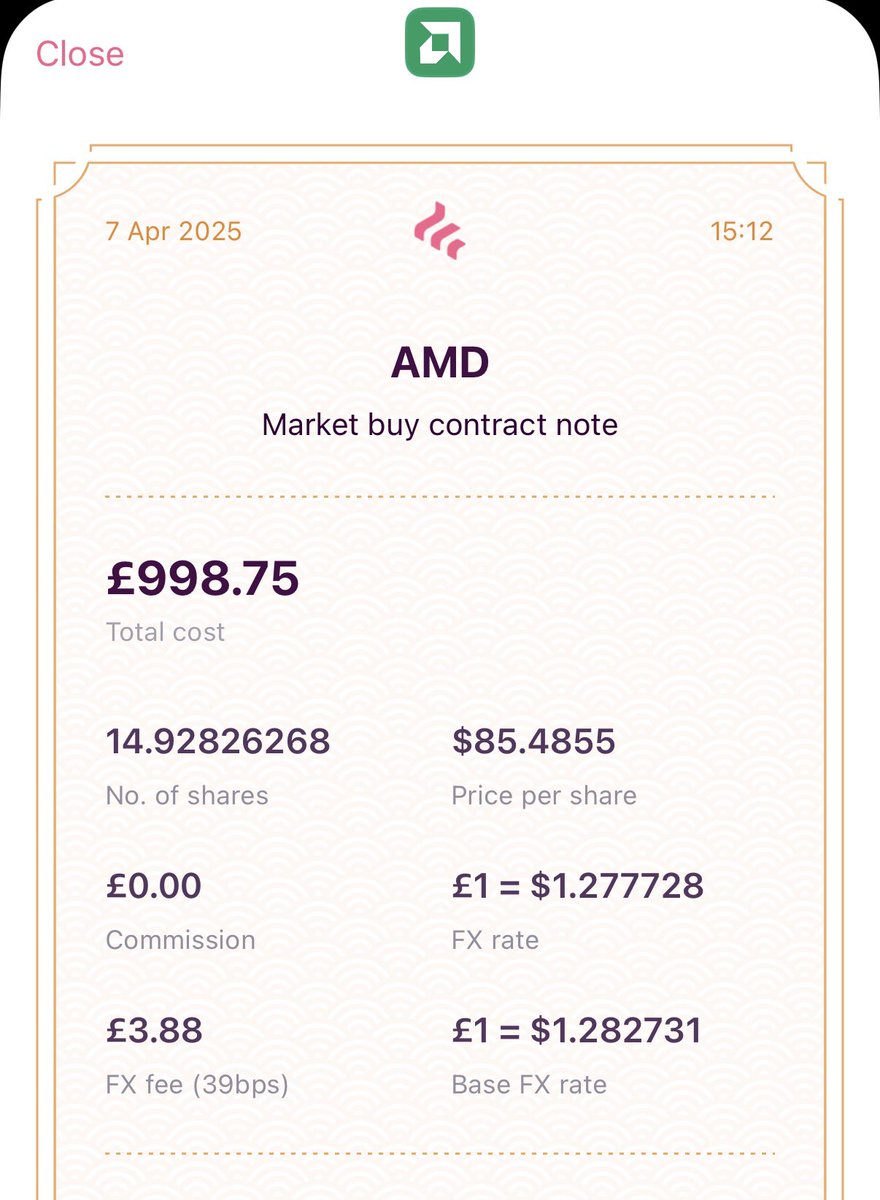
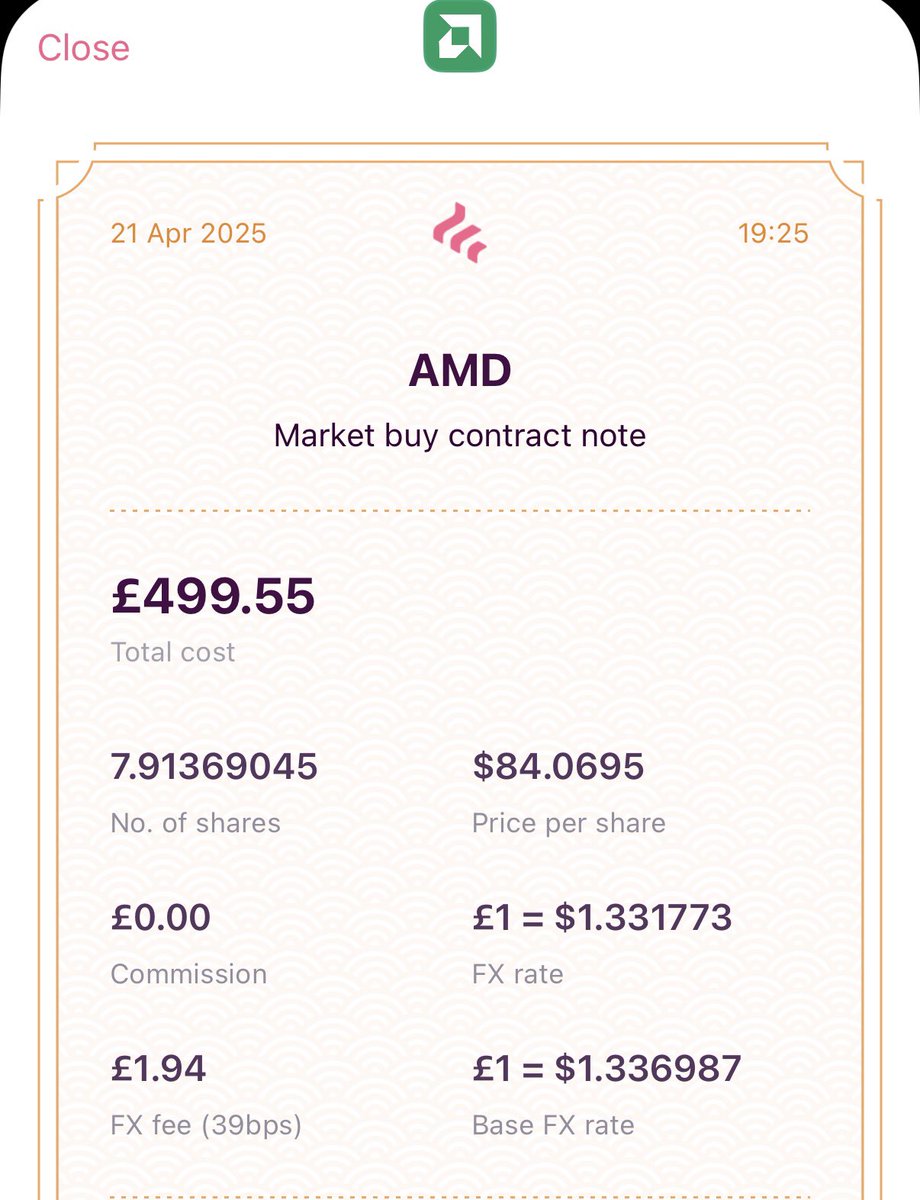
I bought it multiple times at $84–$85 in Apr 2025.
I would not start that position at a $1T tape.
Hold what I have. Not chase.
Would you still buy $AMD here - Or only if you already paid $85?
I don’t chase stocks.
I find them early, value them, and show the receipts.
Follow to see what I’m buying before it becomes obvious.