How do I rank U.S. stocks?
My Strategic Quant Model combines six factors: growth, earnings revisions, momentum, cash quality, valuation and balance-sheet strength.
Here’s how the framework works, what the scores mean and what remains to be tested. ↓ https://t.co/Dxgl6MnVzF
Rate hikes don't break great businesses. They reprice them.
The ECB has hiked twice this year, taking the deposit rate to 2.50% on the back of an energy-driven inflation shock, and markets see more to come. Tighter policy weighs on equity multiples, so European stocks could see further drawdowns from here. But sell-offs in tightening cycles often hand patient investors a discount on quality.
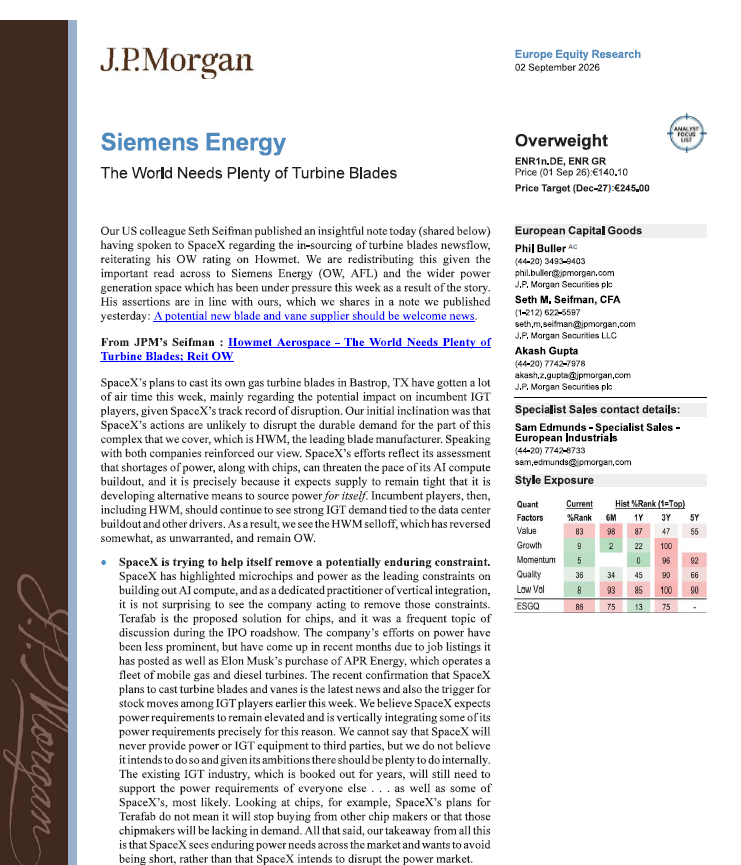
J.P. Morgan's latest note on Siemens Energy (Overweight, Analyst Focus List) is a good example of what that looks like:
- PT €245 (Dec-27) vs €140.10 at publication → ~75% implied upside
Shares down ~8% over 3 months, partly on SpaceX turbine-blade in-sourcing headlines.
JPM's read: SpaceX is securing its own power supply, not disrupting the market.
The gas turbine industry is booked out for years
FY25A → FY28E: revenue €39bn → €57bn
Adj. EBITDA margin 10% → 19%,
Adj. EPS €1.98 → €8.76
Gas Services contracts lock in profitable, recurring FCF into the 2040s - Electrification + AI power demand = multi-year grid & turbine cycle - Wind business expected to break even before end-2026 - Valuation: 24x CY2028E EV/EBITDA.
Macro sets the price. Fundamentals set the value. Details in the screenshots 👇 Not investment advice.
#SiemensEnergy #PowerGeneration #GasTurbines
#AIInfrastructure #Electrification #ECB
#EuropeanStocks #Investing #SMNEY #ENR #SPCX
Another signal that the AI infrastructure cycle may have further to run:
#TSMC affiliate #Vanguard, together with NXP, is considering a second semiconductor plant in Singapore.
The key comment from Vanguard’s chairman:
“The supply shortage will last for a while.”
What I find more interesting than the factory itself is the broader signal:
AI demand → Data centers → Semiconductor demand → Capacity expansion
The AI trade is increasingly becoming a much broader infrastructure and capex story — not just an Nvidia story.
Semiconductors, memory, networking, power and data center infrastructure all sit somewhere in that chain.
#Semiconductors #AI #tmsc #nvda #mu #sndk
One chart I’m watching closely right now:
Oil ↑
Inflation risk ↑
Bond yields ↑
Discount rates ↑
This is more than a macro story.
If higher energy prices persist, the relative attractiveness of equity factors can change as well.
High-duration growth becomes more sensitive to rates, while profitability, cash flow strength and pricing power may start to matter more.
This is exactly why I prefer multi-factor models over looking at valuation, momentum or growth in isolation.
Market regimes change.
Factor relationships change with them.
#Investing #QuantFinance #nasdaq #sp500
Thank you 🙏Really appreciate the thoughtful feedback. The point-in-time backtest and weight stability across different market regimes are definitely two areas I want to explore next.
I’m also curious to see how much of the model’s performance comes from the factor selection itself versus the weighting scheme, so equal-weighted and more dynamic approaches are on my list as well.
Still a lot to test, but that’s exactly where I want to take the framework next. Thanks for following along!
How do I rank U.S. stocks?
My Strategic Quant Model combines six factors: growth, earnings revisions, momentum, cash quality, valuation and balance-sheet strength.
Here’s how the framework works, what the scores mean and what remains to be tested. ↓ https://t.co/Dxgl6MnVzF
#ardyz beğendiğim şirketlerden.Büyüme ve momentum tarafıyla güçlü hareket ediyor.Görüleceğe üzere değerleme puanı diğer metriklere göre düşük. Yani 29 F/K ve 10 FD/FAVÖK ile diğer beğendiğim şirketlere göre daha pahalı duruyor. 62-65 bölgesi destek seviyesi.Oraları kırarsa stop loss öneririm ama bir sonraki bilançoda bol yeşilli rakamlar göreceğiz intron birleşmesi nedeniyle. O döneme kadar düzeltme yaparsa alım fırsatı yaratabilir.2026 başından bugüne kadar getirisi %110. Bir süre dinlenmek isteyebilir. Kademeli alım bu dönemde daha rasyonel görünüyor.
@ahtapot07 3 iş günü içinde açıklama hakları var. Açıklama yapacak taraf Tekfen değil de payları sıfırlanan Can Kültür ve pay alımı yapan ON investment üzerinden olacaktır.
#tkfen TMSF'nin yönetimindeki %42,8 oranına karşılık gelen pay OYAK'a satıldı. Pay devirleri yapıldı.
Yakın zamanda işleme konu olan fiyat açıklanır diye tahmin ediyorum.
Bedelsiz bölünmeler teknik anlamda bilançoda olumlu/olumsuz bir değişikliğe neden olmuyor. Yatırımcı nezdinde ise, daha önce yüksek gördüğü fiyatın düşmüş olmasını bir ucuzluk olarak algılayıp hisse üzerinde pozitif bir hava oluşturabiliyor. Teknik anlamda 100 tl sınırı aşamıyor. Bu seviyenin üzerinde 2 gün pozitif kapanış yaptıktan sonra tekrar değerlendirilebilir gibi duruyor.
Pazarlama değil. Sadece analiz.Bir aracı kurum yarın yokmuşçasına hisse satıyorsa tabiki ani düşüşler olabilir.Bu her hisse için geçerli. Bu şirketin çarpanları pahalı değil sadece gün içi oynaklık çok yüksek. Günlük hareketlere değil aylık hareketlere bakın son 1 yıl getirisi malum.Bugün %10 yükseldiğinde fikrim nasıl değişmeyecektiyse %10 düştüğünde de fikrim değişmiyor.Şirket faaliyetleriyle ilgili olumsuz haberler hisse üzerindeki fikrimi etkiler,günlük hareketler değil. Fiyat orta/uzun vadede mutlaka ederine ulaşır merak etmeyin.
@getlov21 Günlük veya haftalık değerlendirmemek lazım. Yılbaşından bugüne getirisi %91. Çok daha yukarıları da gördü. Şirketin bilançosu iyileştikçe fiyatta buralarda kalmayacaktır. Doğru hissede sabır sürdürülebilir kazanç için şart.
#MU
🟢Tüm beklentileri önemli ölçüde aşan bir bilanço.
🟢AI kaynaklı arz dar boğazı Micron lehine çalışmaya bir süre daha devam edecek gibi görünüyor. Brüt kar marjı hedefi %86 gibi inanılmaz bir orana revize edildi.
🟢Üst yönetim yakın zamanda bir Çin tehditi beklemiyor.
🟢Oyun değiştirici olmaya aday 16 yeni 5 yıllık uzun vadeli SCA imzalandı. (SCA = Strategic Customer Agreement)
🟢Bu anlaşmalar iptal edilemez nitelikte olup 22 Milyar $ büyüklüğünde. 18 Milyar $ kısmı nakit olarak ödenecek.
🟢İleriye dönük hem çeyrelik hem yıllık satışların ve marjların artması bekleniyor.
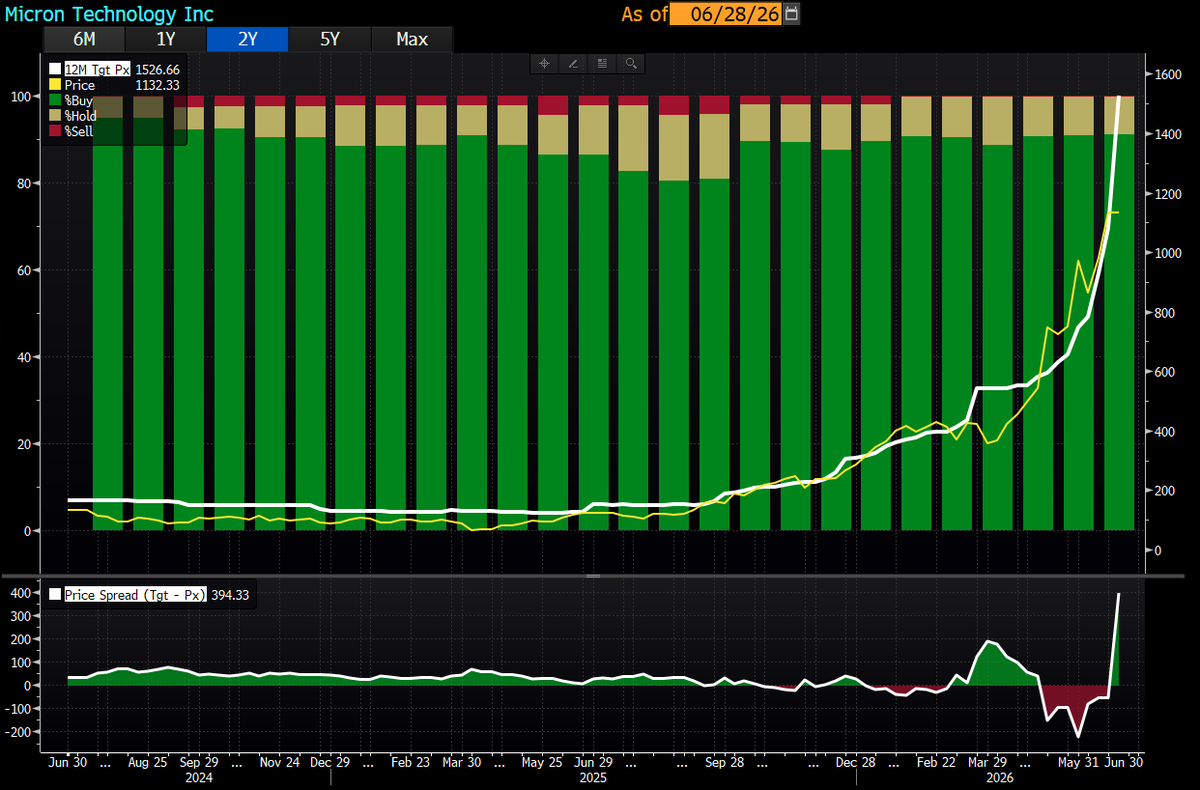
🟢Bloomberg Terminal önümüzdeki 12 ay için ortalama hisse hedefi 1526 $. Bugünkü fiyat seviyesinden yaklaşık %35 getiri sunuyor. Son iki üç günde 1625 $-2000 $ arası analist tahminleri geldiğinide not ediyim.
🟢2027 yıl sonu ileriye dönük Fiyat/Kazanç beklentisinin sadece 7 çarpan olduğunu belirtiyim. ABD piyasaları için çok cüzi bir çarpan olduğunu söyleyebiliriz.
🔴Hissenin son 1 yılda 9 katına çıktığını varsayarak yatırım kararı vermeniz faydalı olacaktır. Orta vadede fiyatlamanın yukarı yönlü olacağı varsayılsa da, borsalardaki düşüşlerde likidite sorunu kaynaklı yüksek karlı pozisyonlarda realizasyon yaşanabiliyor.
Yasal Uyarı: Yatırım tavsiyesi değildir.
#nasdaq $micron