He just did it again
$NVDA
CEO keeps telling you which stocks to buy In 2025 he called: •
$NBIS
at $22 → +1000% •
$INTC
at $23 → +500% •
$SNDK
at $275 → +500% •
$MRVL
at $90 → +200% Now he’s calling: •
$QCOM
at $178.40 •
$CRWV
at $69.65 •
$MSTR
at $151.26 Are you going to ignore him again?
🚨 $NBIS has fallen below $110. I'm still BULLISH.
Two brutal days of selling. The bulls are being tested.
But let's not forget:
✅ Strong Q3 earnings
✅ Rapid revenue growth
✅ Massive demand for AI infrastructure
I'm watching the $100 level closely. If it holds, a strong rebound could be next.
My long-term target remains $300+.
I'm not changing my conviction because of a short-term selloff.
Who's still holding $NBIS?
Follow me for more updates. Let's see where this goes together!
Weeks of red. Still hurts.
Every time I think $IREN has bottomed, it drops again.
47,756 shares.
Down 15.49%.
Still holding.
Not gonna lie, it's been rough. But I'm in this for the long run.
No panic selling. Let's see how this plays out.
Who's still holding $IREN with me?
Follow me. Let's see how this story unfolds together.
Notice:
Investments 10 years ago that are now worth $1M:
$TSLA Tesla: $37,000
$SHOP Shopify: $25,300
$MU Micron: $19,500
$AMD : $12,800
$NVDA Nvidia: $7,800
Investments in 2026 that could be worth $1M in 10 years:
$ASTS — Big day for the U.S. with SpaceX Flight 15 and ULA Vulcan LEO! 🙌
From ULA this morning:
"We have a GO for cryogenic propellant tanking operations, the sequence that will load a million pounds of rocket fuel into the Vulcan and Centaur V stages to perform the mission ahead of them today.
The status board is green with no issues being worked in the countdown and weather conditions are favorable.
Liftoff remains on schedule for 12:54 p.m. EST (1754 UTC) from Space Launch Complex-41 at Cape Canaveral."
$ASTS
AST SPACEMOBILE IS BUILDING SOMETHING MUCH BIGGER THAN A SATELLITE NETWORK.
AST SpaceMobile's November 12 update revealed several developments that investors should not overlook.
Here are 5 major takeaways:
1. COMMERCIAL PROGRESS
ASTS reported major milestones across its services, satellite launches, government contracts, and capital strategy.
2. NATIONWIDE SERVICE TARGET
The company is targeting intermittent nationwide coverage across the U.S. and other key markets before the end of 2026.
3. AT&T & VERIZON INTEGRATION
ASTS has completed initial satellite beam-switching validation between AT&T's terrestrial network and the AST ground network.
This is an important step toward integrating satellite connectivity with existing mobile networks.
4. ITS OWN LAUNCH INFRASTRUCTURE
ASTS plans to develop its own 20-ton-class launch vehicle to deploy its BlueBird satellites into low Earth orbit.
Greater control over launch infrastructure could become a significant long-term advantage.
5. AI & PHASED-ARRAY TECHNOLOGY
ASTS is actively collaborating with major technology companies, including those focused on Physical AI.
Its large-scale phased-array satellite technology could unlock significant performance capabilities.
MY TAKE:
Look at the bigger picture.
ASTS is not simply trying to connect smartphones to satellites.
It's building toward an integrated ecosystem spanning:
• Satellite communications
• Global mobile connectivity
• Launch infrastructure
• Advanced phased-array technology
• Government and commercial partnerships
There are still major execution, financing, and deployment risks.
But the long-term vision is getting bigger.
The question is no longer just how many satellites ASTS can launch. It's how much of the future space-based telecom infrastructure it can build and control.
I'm watching every milestone.
If you find this analysis useful, LIKE, REPOST & FOLLOW.
Let's see where $ASTS takes us. 🚀
Not financial advice.
$IREN — THE REAL TEST IS DELIVERING THESE 5 MILESTONES. 🚀
1️⃣ Microsoft: Commission Horizon 2–4 and deliver the remaining 150MW of AI capacity.
2️⃣ $4B+ ARR: Convert fully contracted AI revenue into operating revenue, targeted for Jan–Feb 2027.
3️⃣ AI Expansion: Execute the 480MW 2026 and 1.2GW 2027 capacity buildout.
4️⃣ Sweetwater: Advance the liquid-cooled data center construction and commissioning.
5️⃣ GPU Deployment: Deliver NVIDIA GB300 infrastructure and scale AI Cloud operations.
IREN already has the power, contracts, and infrastructure pipeline.
Now investors need proof of execution.
DELIVER THE CAPACITY. HIT THE TARGETS. TURN CONTRACTS INTO REVENUE.
$200 won't come from hype. It will come from execution. 🔥
If you agree, LIKE, SHARE & FOLLOW for more
$IREN
updates!
🚨 $CRWV $NBIS $IREN — AI DEMAND IS NOT THE PROBLEM. EXECUTION IS!
The latest Q3 earnings from the three leading neocloud companies sent a clear message:
Demand is booming. Revenue is growing. But the real challenge is turning massive contracts into actual deliveries, revenue, and cash flow.
📊 Here's how the three companies compare:
🔹 $CRWV — CoreWeave
• Revenue: $3.661B, up 168% YoY
• Backlog: $132.5B
• 2027 capacity is nearly sold out.
Strength: Strong pricing power and massive customer demand.
Risk: Heavy debt and rising interest expenses.
🔹 $NBIS — Nebius
• Revenue: $981M, up 571% YoY
• Cash: $7.4B
• Customer prepayments cover more than 100% of related CapEx.
Strength: Rapid growth and relatively strong financing structure.
Risk: Data center delays and pressure on revenue guidance.
🔹 $IREN — IREN
• AI Cloud revenue: $200M, up 182% QoQ
• AI gross margin: approximately 86%
• Contract backlog: $20.3B.
Strength: Power capacity, major customer contracts, and strong AI margins.
Risk: Microsoft project delays and ARR targets pushed into early 2027.
🔥 MY BIGGEST TAKEAWAYS:
1️⃣ AI computing demand remains strong.
2️⃣ Data center delivery is becoming a major competitive advantage.
3️⃣ Customer prepayments are changing how infrastructure gets financed.
4️⃣ Power availability and GPU utilization will determine long-term profitability.
5️⃣ Backlog doesn't equal cash flow. Execution is everything.
I'm watching $IREN, $NBIS, and $CRWV closely over the next few quarters.
AI DEMAND IS REAL. NOW EXECUTION MUST PROVE THE VALUE.
Which company do you think will emerge as the biggest winner?
Like , Repost , Follow for more AI infrastructure insights! 🚀
$ASTS
$ASTS THE BLACKLIFT VISION COULD CHANGE EVERYTHING.
Most investors are focused on AST SpaceMobile's satellites.
But I’m paying attention to something much bigger: BlackLift.
Why?
Because ASTS may be moving toward greater control over its own launch and deployment infrastructure.
Here's why that matters:
• MORE CONTROL: Potentially reduce long-term dependence on third-party launch providers.
• FASTER DEPLOYMENT: Greater flexibility over satellite launch schedules.
• SCALABILITY: Better alignment between launch capacity and constellation expansion.
• LONG-TERM ADVANTAGE: BlackLift could become an important part of ASTS's infrastructure strategy.
Of course, this is not guaranteed.
Development, testing, financing, and execution remain major challenges. The 2028 timeline still needs to be proven.
But think about the bigger picture:
ASTS isn't just trying to build a satellite network. It's exploring how to control more of the infrastructure needed to scale it.
The vision is getting bigger. Now execution needs to catch up.
$ASTS holders: Is BlackLift a potential game-changer or an unnecessary execution risk?
I'm watching every milestone.
If you find this analysis useful, please LIKE, REPOST, and FOLLOW.
Let's see how far $ASTS can go. 🚀
1. Broadcom $AVGO
Custom AI chips (ASICs) and high-speed networking chips. One of the most direct ways to benefit from growing AI data center spending, second only to NVIDIA in the AI chip ecosystem.
2. Taiwan Semiconductor $TSM
The world's leading advanced semiconductor foundry. NVIDIA, AMD, Apple, and many other tech giants rely on TSMC to manufacture their most advanced chips. A critical backbone of the AI supply chain.
3. Rocket Lab $RKLB
Small launch rockets, satellite manufacturing, and space systems. One of the few commercial space companies with real revenue and a substantial order backlog. A potential long-term winner in the growing space economy.
4. Palantir $PLTR
An enterprise AI software platform bringing AI into real-world government and corporate workflows. One of the more commercially advanced players in AI applications.
5. Micron Technology $MU
A key supplier of High Bandwidth Memory (HBM). As demand for AI servers accelerates, advanced memory is becoming an increasingly critical part of the AI hardware ecosystem.
📈 AI, semiconductors, and space technology are three major growth trends I'm watching closely.
If you find this useful, LIKE ❤️, FOLLOW, and SHARE!
The next big opportunity could be right around the corner. 🚀
$5,000 investments that are worth +$1 million:
Bitcoin: 11 yrs ago
Nvidia: 12 yrs ago
Tesla: 16 yrs ago
$5,000 investments that will be worth +$1 million:
As a reference, I've called:
$NBIS at $20 → +1,399%
$RKLB at $16 → +844%
$AMD at $100 → +505%
$ASTS at $20 → +569%
$PLTR at $40 → +419%
I’m always looking for the next big opportunity before the crowd. 📷
Follow now. The next alert could be the one you don’t want to miss
WHAT IF THIS HAPPENS?
What if Tim Cook takes over $NVDA, while Jensen Huang joins $SPCX?
The market could witness one of the biggest AI-driven rallies in history.
I'm watching 5 stocks that could benefit massively from this potential shift.
Here are the 5 stocks I've selected:
$SPCX
🚨 BREAKING: SpaceX is making a major move into the U.S. wireless market.
The FCC has accepted SpaceX's application to acquire nationwide 800 MHz spectrum.
Key details:
• 546 paired spectrum licenses.
• Coverage reaching nearly 100% of the U.S. population.
• Up to 89 MHz of spectrum in certain markets.
• Low-band spectrum capable of improving indoor coverage.
What does this mean?
Elon Musk isn't just trying to connect phones through satellites. He's building the foundation for a nationwide wireless network.
The space communications revolution is accelerating.
Like, repost & follow me.
Not financial advice.
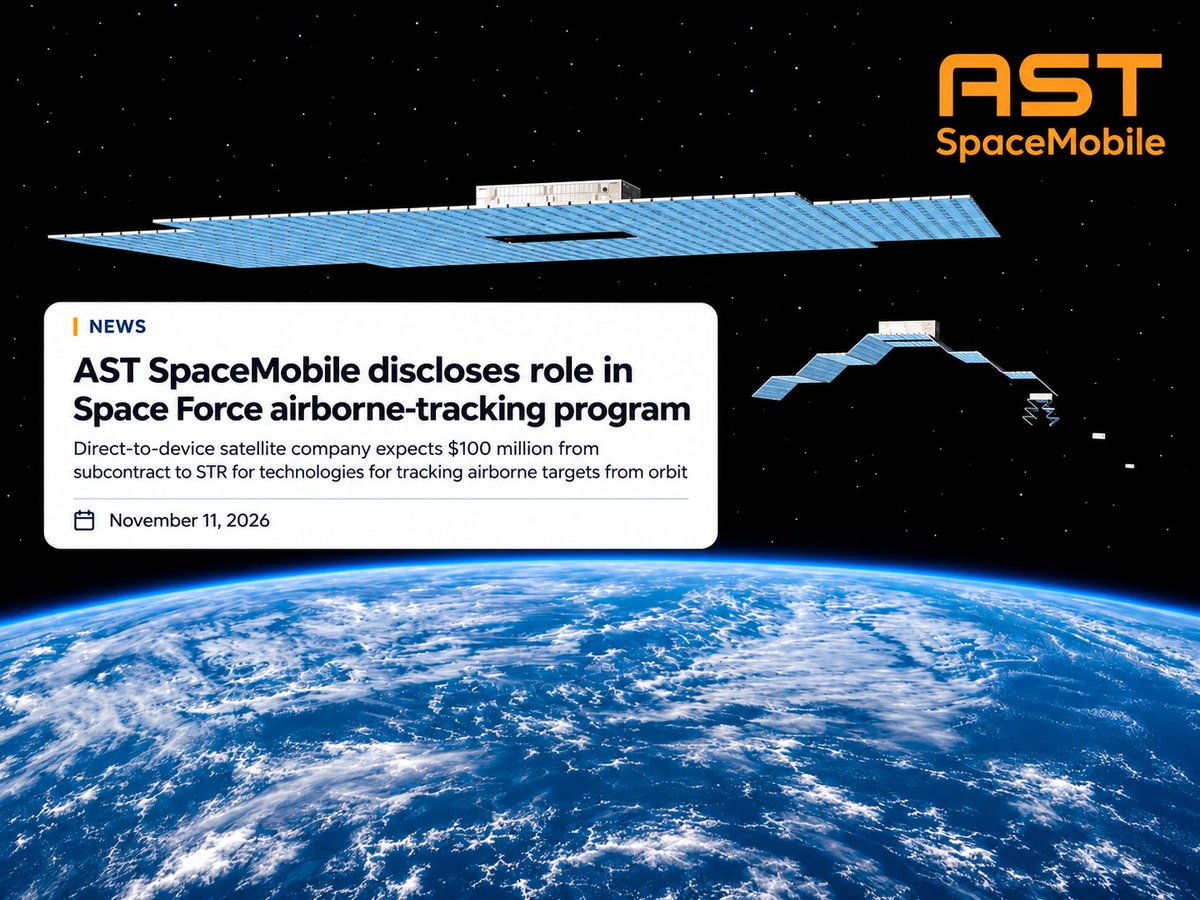
🚨 $ASTS: AST SpaceMobile is entering a much bigger game.
AST SpaceMobile confirmed its role in the U.S. Space Force's SB-AMTI program.
Key highlights:
• Approximately $100M in expected revenue from its Space Force award.
• Technology designed to detect and track aircraft directly from space.
• Participating through prime contractor STR.
• The Pentagon requested approximately $803M for the broader FY2027 program.
Here's what matters:
ASTS is no longer just a direct-to-cell satellite connectivity story.
Its phased-array technology could also have important military and defense applications.
A new potential revenue stream, expanding government opportunities, and technology with applications beyond smartphones.
I believe the defense side of $ASTS deserves much more attention.
The opportunity could be bigger than many investors realize.
Like, repost & follow me. 👇
Not financial advice.
AI compute demand is showing no signs of slowing down. The real problem is that supply simply can't keep up with demand.
If even an industry leader like TSMC says demand is far exceeding its production capacity, the AI infrastructure investment cycle may be far from over.
$NBIS is positioning itself for the next wave of AI.
Nebius just launched an open-source toolkit for training robotic arms, humanoids, and quadrupeds.
The goal? Bring developers into the Nebius ecosystem before their demand for $NVDA GPU computing scales.
Meanwhile, $CRWV revealed that 70% of its new cloud customers in Q3 were already using Forge.
AI infrastructure isn't just about chatbots anymore. Robotics could become the next major driver of compute demand.
I'm bullish on $NBIS and $CRWV.
The AI infrastructure race is far from over.
Like, repost & follow me.
$ASTS investors, I want to hear BOTH sides.
With Democrats taking control of Congress after the 2026 midterms, how should we think about SpaceX potentially delaying AST SpaceMobile launches?
Remember, SpaceX is both a competitor and a launch provider for ASTS.
Could deliberate delays trigger congressional scrutiny over anti-competitive behavior?
Does Elon understand that any attempt to restrict ASTS could potentially backfire?
Or are we reading too much into the political angle?
I want to hear the bull AND bear arguments.
Let's have a serious discussion.
Follow me for more $ASTS analysis.
Not financial advice.
“THE AI COMPUTE SHORTAGE IS GETTING MORE EXPENSIVE. And investors may be missing the bigger picture.”
$CRWV just showed that demand for AI compute is far exceeding available capacity.
GPU rental prices are rising. Older Ampere and Hopper GPUs are becoming more valuable, and contract renewals could unlock nearly $10B in potential annualized revenue through 2028 — without buying additional GPUs for those renewals.
This could be a major tailwind for $NBIS, $IREN and other neocloud providers.
But demand alone isn't enough. Financing costs, debt, CapEx and execution will determine who actually wins.
The opportunity may be real. The winners will be those who turn demand into profits.
Like, repost & follow me for more AI infrastructure insights.
Not financial advice.