Introducing @floatsheets.
The first perpetuals venue built for the stocks nobody lists: micro-caps and penny stocks. Attested pricing, risk controls for halts, gaps and splits, and 24/7 long or short exposure on @Robinhoodapp Chain.
Coming soon..
Market data rights are part of the product architecture.
Reading a price feed is not the same as having permission to aggregate it, use it in an oracle, sign a derived reference, and expose that reference to a protocol.
FloatSheets treats licensing and redistribution terms as launch dependencies because a technically correct oracle still needs a legal right to operate.
Coming soon to @RobinhoodApp
A halt should not turn the protocol into a guessing game.
The FloatSheets design blocks normal openings and closings while the underlying is halted, but retains defined deleveraging rules for risk reduction.
That prevents a stale reference from becoming a new entry price while still giving the system a path to reduce exposure.
Every signed price system has a key management problem.
A price signer must rotate without breaking the feed. Old messages must fail replay checks.
Source disagreement must trigger alarms before it reaches the vault.
The FloatSheets oracle design treats these as core market controls, alongside the midpoint itself.
Price integrity is operational work long before it becomes a smart contract call.
Building next gen infrastructure for @RobinhoodApp
Two equities can trade at the same price and deserve completely different risk settings.
FloatSheets groups markets by liquidity class, then assigns leverage, open interest caps, position limits, base spread, skew sensitivity, and confidence thresholds through that class.
The share price is not the risk model.
The quality and capacity of the reference market are.
A serious market needs an event history, not just a price history.
The FloatSheets data model records prices and bands alongside positions, funding, liquidations, insurance events, corporate actions, and listings.
That makes it possible to trace what happened around a position instead of trying to explain it from a candle after the fact.
Coming soon @RobinhoodApp
Staked FLOAT is not positioned as a decorative governance layer in the FloatSheets model.
It sits inside the loss waterfall.
After the insurance fund, staked FLOAT is designed to absorb gap losses before LP principal is touched in a declared default state.
The economics are simple.
Fee participation comes with a defined place in the risk stack.
A stop loss only works if the protocol has a valid price to act on.
For a thin equity reference, a trigger hit during stale data, a halt, or a wide confidence band cannot be treated like an ordinary fill.
FloatSheets separates the order instruction from the market state that determines whether execution is actually allowed.
That distinction matters most when the chart is moving fast.
Built on @RobinhoodApp Chain
One number worth watching on a microcap market is not the price. It is the open interest cap.
The FloatSheets model ties that cap to underlying average daily volume.
In plain English, the protocol should not carry more synthetic exposure than the reference market can reasonably support.
If the underlying activity shrinks, capacity should shrink with it.
A busy dashboard does not create exit liquidity.
Markets should not graduate because a ticker is trending.
The FloatSheets design starts eligible names in guarded mode.
Lower leverage and tighter capacity come first.
Better terms follow only after the market has shown stable data, reliable uptime, and a track record the vault can price.
Attention can nominate a market. It should not set its risk limits.
Build @RobinhoodApp Rails
Exactly. Freshness is set by liquidity class and session, not one global timer.
The current model uses roughly five seconds for listed names in regular hours and sixty seconds for OTC references, then adds the band gate, halt state, and after hours tier.
A recent price can still be unusable when sources disagree.
A FloatSheets fill has a paper trail.
A price update enters the registry with a signature and attestation reference.
The engine checks market state, freshness, confidence, collateral, leverage, and capacity.
Only then does the vault take the position risk.
The goal is simple: anyone reviewing a fill should be able to see the exact conditions under which the protocol accepted it.
Five seconds can be the difference between a price and a stale memory.
The FloatSheets design gives listed names a much shorter freshness window during regular trading than OTC references. Once a reference ages past its permitted window, ordinary fills stop.
That rule matters because an old price becomes most dangerous when the market is moving fast and traders want to use it the most.
A thin equity protocol should be tested against the moments that break ordinary assumptions.
The FloatSheets acceptance plan includes gap fixtures, stale price rejection, halted market rejection, reverse split scaling, and delisting settlement. It also tests whether liquidation happens before insolvency and whether the loss order holds under stress.
A green dashboard is not the standard.
The standard is whether the system behaves predictably when the tape does not.
Coming to @RobinhoodApp
Execution starts with a price request, not a cached number.
When a trade arrives, the engine can require a fresh signed update within the permitted block window.
The registry verifies the signer and attestation reference before the market checks confidence, state, capacity, and collateral.
That sequence matters because a thin equity can be tradable at 10:02:00 and unquotable seconds later.
Built on @RobinhoodApp
Every pool backed perpetual has a question users should ask before depositing: who absorbs a gap beyond liquidation?
FloatSheets proposes a stated order. Insurance absorbs losses first, then staked FLOAT, then LP capital only in a declared default.
The model still needs public caps, stress tests, and visible capital at every layer.
At 4:00 PM, an equity price stops being a regular session price.
The FloatSheets after hours model begins with the last good reference, then widens the confidence band and lowers the leverage tier.
The market can stay visible outside regular hours without treating a thin after hours print as equal to a deep session quote.
Soon on @RobinhoodApp
A corporate action changes more than the ticker line on a dashboard.
A split changes the unit scale.
A symbol change can break the reference path.
A delisting turns an open market into a settlement process.
FloatSheets is built around explicit market states so those events change contract behavior before they create an accounting problem.
Build on @RobinhoodCrypto
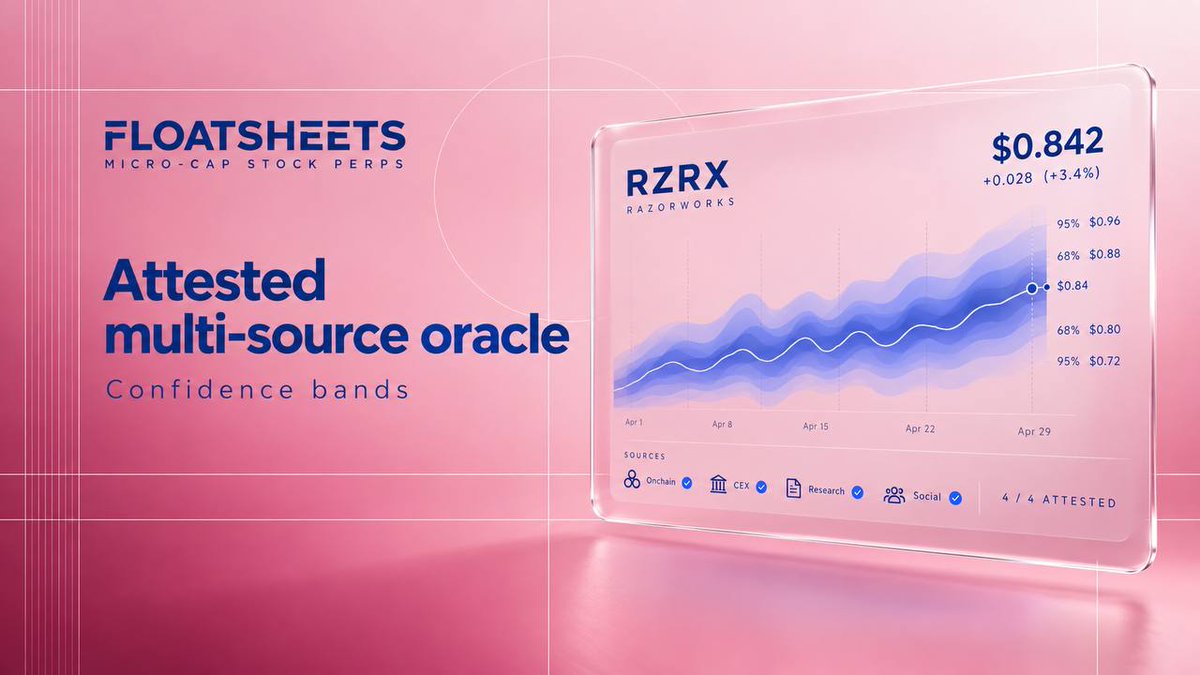
The most useful number on a thin equity screen may be the confidence band, not the headline price.
A midpoint tells you where the sources landed.
The band shows how tightly they landed together.
On FloatSheets, that disagreement is designed to flow into leverage, capacity, and market availability.
The protocol should care when the inputs no longer agree.
A vault has two jobs that are easy to confuse.
It provides the capacity behind positions, and it absorbs the economic result of those positions.
FloatSheets keeps both visible.
Deposit value, available capacity, trader PnL, and loss allocation belong in the same view because liquidity is not passive when the underlying reference is thin.
Coming soon to @RobinhoodApp
Every market on FloatSheets begins with a smaller question than: Will this ticker get attention?
Can the protocol price it, cap it, pause it, and settle it when the underlying stops behaving normally?
That is why listing rules come before volume.
A name needs data coverage and an enforceable market state before it gets a leverage setting.