Join Our Free Telegram For --
✅ News
🔰 Stock Ideas
🔥 F&O Ideas & No Loss Prooven Strategy
💜 Psychology Of Market
💫 Motivational Quotes
https://t.co/PhXrdYpAvu
Or Search In Telegram & Youtube - Market Crushh
Top 20 growth stocks with strong potential to be future market leaders.
$NBIS | AI Cloud Infrastructure
$IREN | AI Cloud / Data Centers
$PENG | AI Factory Infrastructure
$CIFR | AI Data Centers / HPC
$OKLO | Advanced Nuclear
$RKLB | Space Launch / Infrastructure
$VST | AI Energy
$VRT | Data Center Cooling / Power
$AVGO | AI Custom Chips / Networking
$MU | AI Memory / HBM
$CRDO | High Speed Data Center Connectivity
$AXTI | AI Photonics Materials
$AAOI | Al Optical Transceivers
$PLTR | Defense Tech
$AEHR | Photonics / Semiconductor Testing
$SATL | Satellite Intelligence / Earth Observation
$PL | Satellite Imaging / Geospatial Intelligence
$ALAB | Al Rack Scale Connectivity
$KRKNF | Underwater Defense /Robotics
$OUST | Physical AI / Robotics
Bookmark this for later validation!
If you're not following us with notifications turned on, you might probably not see us again.
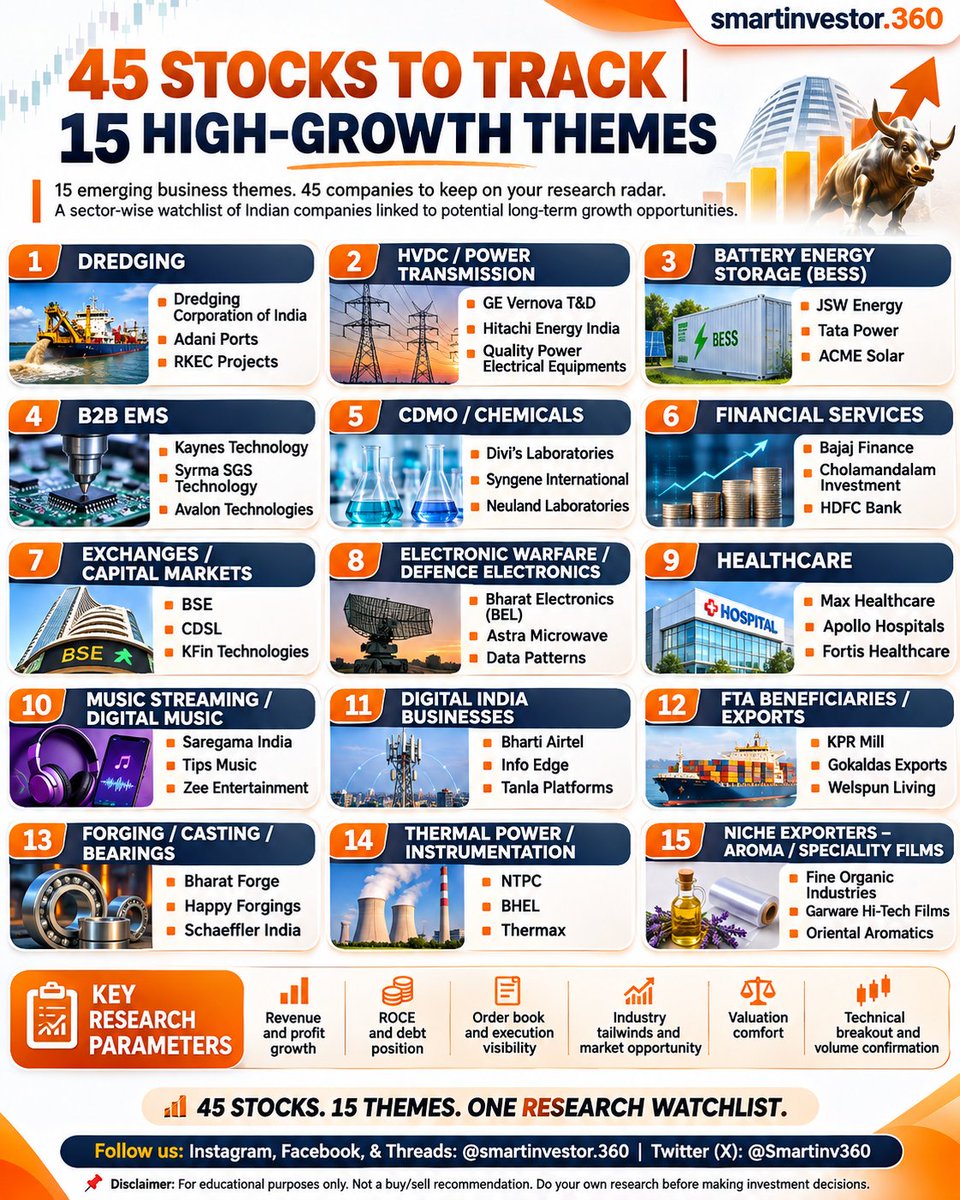
12 listed hospital firms mapped by their core speciality within the healthcare value chain:
#Stockstowatch
🏥 Integrated healthcare giant: Apollo Hospitals
🏥 Premium metro hospitals: Max Healthcare
🏥 Multi speciality chain: Fortis Healthcare
🏥 Cardiac led healthcare: Narayana Hrudayalaya
🏥 South India hospitals: Aster DM Healthcare
🏥 Super speciality hospitals: Medanta
🏥 Oncology focused care: HCG
🏥 Regional hospital chain: KIMS
🏥 Eye care hospitals: Dr Agarwal’s Health
🏥 Mother & child care: Rainbow Children’s
🏥 North India hospitals: Yatharth Hospital
🏥 Western India hospitals: Jupiter Life Line
Multibagger stock screening criteria 🔍
Here are the parameters I'd use to identify potential multibaggers in the Indian small-cap space.
1. Valuation
- Market Cap: ₹1,000–5,000 Cr
- P/E: Below 30
- PEG Ratio: Below 1.5
- Debt-to-equity: Below 0.5
2. Financial Growth
- Sales CAGR (3 years): Above 15%
- Profit CAGR (3 years): Above 20%
- ROCE: Above 20%
- ROE: Above 15%
- Operating margin: Stable or improving
3. Business Quality
- Strong competitive advantage
- Promoter holding: Above 40%
- Promoter pledge: 0%
- Positive operating cash flow
- Improving order book or business visibility
- Presence in a high-growth sector
4. Additional Triggers
- Capacity expansion
- New product launches
- Large order wins
- Import substitution opportunities
- Export growth
- Institutional holding increasing
My strongest filters: High earnings growth + ROCE above 20% + low debt + reasonable valuation.
A low P/E alone doesn't make a multibagger. The key is finding a business where earnings can compound for the next 3–5 years.
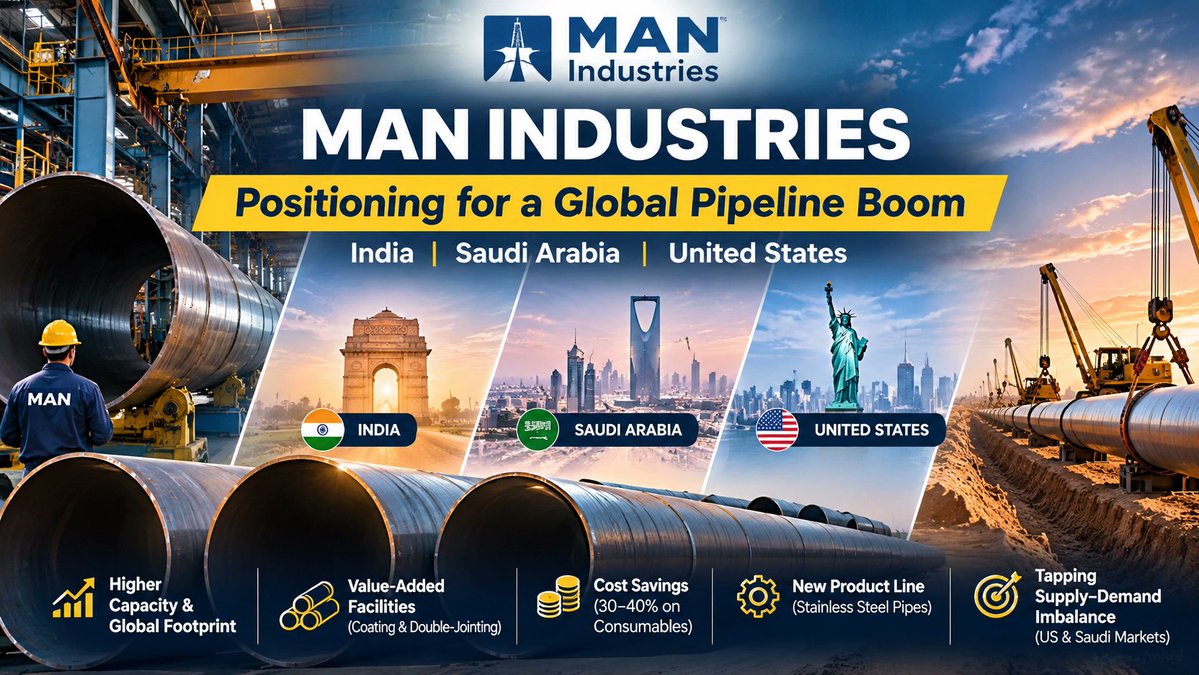
#MANINDUSTRIES: Positioning for a Global Pipeline Infrastructure Boom
Man Industries is transforming itself from an India-focused pipe manufacturer into a global manufacturing platform. Its Q2 FY27 earnings call highlighted an interesting opportunity: pipeline demand is growing faster than available manufacturing capacity in certain markets, particularly the US.
The US is witnessing rising demand for pipeline infrastructure due to three major developments: increasing gas requirements from AI data centres and power generation, replacement of ageing oil and gas pipelines, and expansion of gas transportation networks. Management believes demand will remain strong over the next five years and mentioned that some competitors are already booked until 2030. This creates an opportunity for additional qualified suppliers. To participate in this market, Man has approved a 350,000-tonne annual capacity US plant with an investment of $110 million, targeted for commissioning by December 2027/January 2028. Management estimates the annual US pipeline opportunity at $2–4 billion. The company currently cannot fully access this market through exports from India because of trade barriers. Local manufacturing and API certification will be important before it can start bidding.
Saudi Arabia offers another significant opportunity. Management highlighted nearly 500,000 tonnes of bids, supported by Aramco's gas expansion, Master Gas 4, pipeline loop lines, renewable projects and water infrastructure. It expects a strong bidding environment through 2027–2032/34. The acquisition of National Pipe Company (NPC) gives Man an established manufacturing base inside Saudi Arabia, bringing it closer to customers and projects. Man has also upgraded NPC's plant to manufacture additional pipe sizes required for water pipeline orders, allowing it to participate in a wider range of projects.
NPC is currently operating at around 40–45% capacity utilisation. Management is targeting approximately ₹1,500 crore revenue in FY27 and ₹2,500 crore in FY28. Higher utilisation provides an opportunity to grow revenue using existing manufacturing infrastructure rather than immediately building a completely new plant.
Man is also moving further up the value chain. Its Saudi coating and double-jointing facility is targeted to start operations by April 2027. These activities were earlier outsourced in certain cases. Bringing them in-house will allow Man to offer more integrated pipeline solutions and capture additional value. Management expects margins above 15% from this facility.
In India, the company is entering the higher-value stainless steel pipe segment through its Jammu plant, where production is expected to begin in April 2027. Management is targeting 25–30% utilisation in the first year, with potential peak revenue of ₹1,000–1,200 crore and EBITDA margins of 18–22%. This also creates an opportunity to serve domestic demand through import substitution.
Another important development is the benefit of combining procurement between India and Saudi Arabia. Man has already achieved 30–40% cost savings on certain raw materials and consumables, including fluxes and welding wires. These savings can improve manufacturing profitability without requiring equivalent growth in revenue.
The scale of the opportunity is reflected in Man's consolidated order book of approximately ₹3,500 crore and bid pipeline of ₹18,000–19,500 crore. Management's historical order win rate is around 20–35%.
The bigger picture: Man Industries is positioning itself across three important markets: India, Saudi Arabia and the US. The supply-demand imbalance in the US and strong project pipeline in Saudi Arabia create opportunities to win additional orders. Its strategy combines local manufacturing, higher capacity utilisation, value-added processing and lower procurement costs.
However, demand alone does not guarantee growth. Investors should closely track order conversion, US plant commissioning and API certification, NPC utilisation, project execution, margins and cash flow. The next few quarters will show how effectively Man converts this opportunity into actual business.
#TriveniTurbine: Three New Opportunities as Global Demand for Power Equipment Surges
Triveni Turbine is expanding beyond its traditional steam turbine business into three interesting areas: gas turbine refurbishment, combined-cycle steam turbines and boiler feedwater pump drives.
The opportunities are particularly interesting because global electricity demand is rising, while parts of the power equipment supply chain are struggling to keep pace.
1. Gas Turbine Refurbishment: Benefiting From a Global Supply Shortage
The global gas turbine market is facing a major demand-supply imbalance.
According to Reuters (November 2026), global gas turbine orders have crossed 100 GW, while annual manufacturing capacity is estimated at just 60–70 GW. Delivery timelines for new turbines in the US are averaging around six years.
The shortage is being driven by rising electricity requirements from AI data centres, utilities and industrial facilities. Manufacturing capacity and critical component supply chains cannot expand quickly enough to meet demand.
How does this benefit refurbishment companies?
When power companies cannot get new turbines quickly, maintaining and upgrading their existing machines becomes more important.
Instead of waiting years for replacement equipment, operators may choose to:
- Replace worn-out turbine components.
- Upgrade existing machines.
- Refurbish older turbines.
- Extend the operating life of existing power plants.
This creates an opportunity for specialised refurbishment and aftermarket service providers.
Where does Triveni fit?
Triveni has secured a gas turbine refurbishment opportunity through its South African subsidiary with a large utility in the SADC region.
Management indicated a potential scope of $80–90 million over 4–5 years, involving replacement parts, upgrades, manufacturing and installation. A European partner will provide technology, components and technical expertise.
The bigger opportunity is to use this experience to enter more international gas turbine refurbishment markets.
However, the potential contract value is not guaranteed revenue. Actual work depends on the overhaul requirements identified for the turbines.
2. Combined-Cycle Steam Turbines: Entering the Data Centre Power Ecosystem
Combined-cycle plants generate electricity in two stages.
A gas turbine generates electricity first. Its hot exhaust is then used to produce steam, which drives a second turbine and generates additional electricity.
This improves the overall efficiency of the power plant.
Triveni has secured a US order linked to a data centre involving:
- Two steam turbines of 25 MW each.
- 50 MW total steam turbine capacity.
- Part of a project with 150 MW of gas turbine capacity.
Triveni supplies the steam turbines, not the gas turbines.
As data centres require more reliable electricity, combined-cycle power projects can create new opportunities for steam turbine suppliers.
Management clarified that this segment currently represents less than 5% of Triveni's inquiry book. Repeat orders will be important.
3. Boiler Feedwater Drives: An Opportunity From Thermal Power Expansion
Thermal power plants need to pump water into boilers at very high pressure. This requires powerful boiler feedwater pumps, which can be driven by steam turbines.
Triveni has secured an order to supply the drive turbine for a boiler feedwater pump in a supercritical thermal power plant.
The company is not manufacturing the pump itself; its opportunity is to supply the turbine that drives it.
As India adds thermal power capacity, supporting equipment such as these drives can create additional business opportunities for Triveni.
#Belrise industry
Entry in Electronics manufacturing ☺️
𝗗𝗢 𝗬𝗢𝗨 𝗞𝗡𝗢𝗪 𝗪𝗛𝗔𝗧 𝗖𝗡𝗖 𝗙𝗜𝗫��𝗨𝗥𝗘𝗦 & 𝗙𝗔𝗧𝗣 𝗠𝗘𝗔𝗡 𝗜𝗡 𝗦𝗠𝗔𝗥𝗧𝗣𝗛𝗢𝗡𝗘 𝗠𝗔𝗡𝗨𝗙𝗔𝗖𝗧𝗨𝗥𝗜𝗡𝗚?
🔹 𝗖𝗡𝗖 𝗙𝗜𝗫𝗧𝗨𝗥𝗘𝗦:
Precision-engineered tools that hold components in the exact position during machining.
They ensure accuracy, consistency, faster production and reduced rejection.
🔹 𝗙𝗔𝗧𝗣:
𝗙inal 𝗔ssembly, 𝗧esting & 𝗣ackaging.
The final stage where electronic components are assembled, tested for functionality and prepared for delivery.
𝗪𝗛𝗬 𝗗𝗢 𝗧𝗛𝗘𝗬 𝗠𝗔𝗧𝗧𝗘𝗥?
These are critical elements of the electronics manufacturing ecosystem.
Precision + Automation + Quality Control = Manufacturing Excellence.
𝗧𝗵𝗲 𝗶𝗻𝘁𝗲𝗿𝗲𝘀𝘁𝗶𝗻𝗴 𝗽𝗮𝗿𝘁?
Belrise Industries has entered this space with a maiden LOI for CNC fixtures linked to a major American smartphone player's ecosystem, while discussions continue for additional fixture categories, including FATP.
𝗔 𝗽𝗼𝘁𝗲𝗻𝘁𝗶𝗮𝗹 𝗻𝗲𝘄 𝗴𝗿𝗼𝘄𝘁𝗵 𝗮𝗻𝗴𝗹𝗲 𝗯𝗲𝘆𝗼𝗻𝗱 𝗮𝘂𝘁𝗼𝗺𝗼𝘁𝗶𝘃𝗲 𝗮𝗻𝗰𝗶𝗹𝗹𝗮𝗿𝗶𝗲𝘀.
#ElectronicsManufacturing #PrecisionEngineering #BelriseIndustries #MakeInIndia
🚨 MILLWORKS TECHNOLOGIES IS LESSON🚨
In Vijay Kedia’s SMILE formula says M stands for = Medium in Experience. He literally means 8-10 years of management surviving economic cycles, not some 2022 born startup that hasn’t even seen one full downturn. Millworks was inaugurated in 2022. People are betting on a company that’s barely out of diapers. You want to call that "medium experience"? That’s not experience, that’s a fucking science fair college project.
And look at the real players. Kalyan Jewellers was small cap 4 years ago and it is a large cap now, and promoters are still sitting on 62.85% ,skin in the game bitch! , locked and loaded. They didn’t run for the exits the second the bell rang. That’s conviction. That’s real money saying "I believe in this business."
So here’s the brutal wisdom: In SMEs, where growth is still wide open, you do NOT touch anything below 55% promoter holding. Period. If management won’t back their own bullshit with their own money, I sure as hell won’t back it with mine. No 55-65%+ conviction? Then it’s just loud-mouthed, empty suit BIG TALK…and talk is cheap, worthless, bottom feeding bullshit.
Millworks is the lesson. Don’t ignore it.
I didn’t sink one goddamn rupee into this PIECE OF TRASH for a reason: pathetic 47% promoter holding. promoters were sitting at 65.08% before the IPO, and then poof they magically "diluted" down to 47.18% right after the issue. You think that’s a coincidence? That’s not "dilution," that’s a goddamn exit door.
Not investment advice, just cold, hard, skin-in the game reality.
🚨 MILLWORK TECHNOLOGIES – CONSPIRACY THEORY. 👁️Staring at Rs.100Cr Hole in the Wall
First the background, which everybody chose to ignore because there was a lot of hype driven by massive Rs.160Cr issue
Originally, the promoters founded V3 Technologies in 2015. The business was pretty bad and grew VERY SLOWLY to Rs.9.6Cr in Fy24 and 22Cr in Fy 25. YES Rs.22Crore ONLY in FY25.
In between, in FY 22, Promoters founded MILLWORKS TECHNOLOGIES but continued to carry out the works under V3 Technologies only, “grinding” their way to Rs.22Cr.
V3 Technology’s manufacturing Unit was taken on Lease in Millworks Name, in January 2024 only.
2 More small sheds (Unit 2 & Unit3) with machining equipments in Peenya were taken on lease in March and Nov 2024 .
Then in Jan 2025 it took on lease Unit 4 shed which is somewhat large with aim to expand business using proposed IPO funds. Since there was not much business operation, part of this UNIT 4 has been leased out (even now to a third party) for Rs.65,000 per month. PLEASE NOTE THIS!! 😆
So we can see, the company has small workshops only which generated Rs.22Cr max in Fy25. (The large Unit was not operational because machines are not there and needed funds to buy)
To buy large number of CNC Machines huge funds are needed (IPO was estimated for Rs.160Cr).
With measly Rs.22Cr turnover, it is impossible to raise Rs.160Cr from market
That is the background which all of us IGNORED due to the hype.
Now the CONSPIRACY THEORY! 🚨
With insignificant machining business in old run-down sheds, the people behind, must have come up with idea to cook the books and show HUGE turnover in FY26 with fake orders.
A company with pitiable machining capacity and 22Cr turnover in FY25, SUDDENLY BALLOONED to Rs.148Cr in Fy26. WOW! 😜
Considering the lame duck business growth history of V3 Technologies as well as the promoters, we can assume company, at best, would have got around 40 to 45Cr orders in FY26, with addition of sheds (Unit 2 &3) (ie Against Rs.22Cr reported in Fy25)
Even with Rs.45Cr, it will not be enough to raise 160Cr in IPO. No one will accept that. So another 100Cr must have been COOKED UP. Out of this 100Cr around Rs.70Cr is mentioned as work order from QUICKPAY SERVICES for Drone Parts in the RHP. Rest is not specifically stated. But from Auditor comments around Rs.97.5Cr is fake.
Since MILLWORKS has NO machining capability to make drone parts, it is stated in RHP, that this work is being done by Chennai based BIG BANG BOOM TECHNOLOGIES. (this should have been a RED Flag for Investors. Such a BIG Over HYPED company has no capability??) 🚨
Now, it can be safely presumed, there is absolutely NO NEED for QUICKPAY which has to supply high security, high performance drones to the Defense Forces, to place order on a incapable company like MILLWORKS, only to get it made by BIG BANG! 😜
From the AUDITOR QUALIFICATION it is obvious that there is no substance or back up for this order. 🚨
“We could not obtain sufficient and appropriate evidence about whether the trade receivables and the advances due from this party are recoverable” - Auditor🚨
In simple terms, these are fraud entries. (This is Conspiracy Theory) That is about Rs.97.5Crore.
This means, QUICKPAY went ahead and got works done by BIG BANG BOOM and MILLWORKS is NOWHERE in the picture. 🚨
Whatever money is collectable as per books, is NOT COLLECTABLE at all, since QUICKPAY must have already paid money for the works to BIG BANG and it got the stuff made by them. (this is CONSPIRACY THEORY) 😆
Since Millworks does not have precision machining capability to do such works, anyway it could not have done the job. (If it had capability, it would have done the job by itself)
So, we have an IPO, claiming company has Rs.148Cr turnover in Fy26 but with an almost Rs.100Cr HOLE in that.
May be, like in the case of C2C, @sebi_updates need to have a serious look at this fiasco, to check whether there is any substance in the conspiracy theory, especially since Auditor has raised RED FLAG.
REMEMBER, THIS IS CONSPIRACY THEORY!! DON’T BELIEVE THIS. 👍
One of the biggest mental blocks investors have is buying a stock that has already doubled from its lows. They feel it has run up too much and would rather look for something that is still lying at the bottom.
This is exactly how many investors miss out on huge multibaggers. They focus on how much a stock has already rallied rather than studying where the company could be headed over the next few years.
The real question is not how much a stock has already gone up, but how much potential it still has from here.
If a company has the fundamentals, momentum and structural growth opportunity to double or even multiply several times from current levels, ignoring it simply because it has already doubled makes little sense.
You bet on the horse that is already running well, not the one still sitting in the stable hoping it will eventually start running.
🚨 India's ₹68,816 Cr Ultra-High-Voltage Power Highway! ⚡
India is planning its first 1,150 kV ultra-high-voltage transmission network, marking a major leap beyond the existing 765 kV grid.
The NCT has recommended a massive ₹68,816 Cr project.
Which listed companies could benefit? 🧵👇
#Delaplex
1. Whats new this time ?
Fact that the MDC is not restricted to BSNL partnership. They are deploying it globally. So BSNL partnership is not the only boost here. Example: their ongoing POC for largest beverage company using MDC+IOT.
#e2e#multibagger#nifty#stocks
TD Power Systems | Order Book: Export-led business with diversified applications
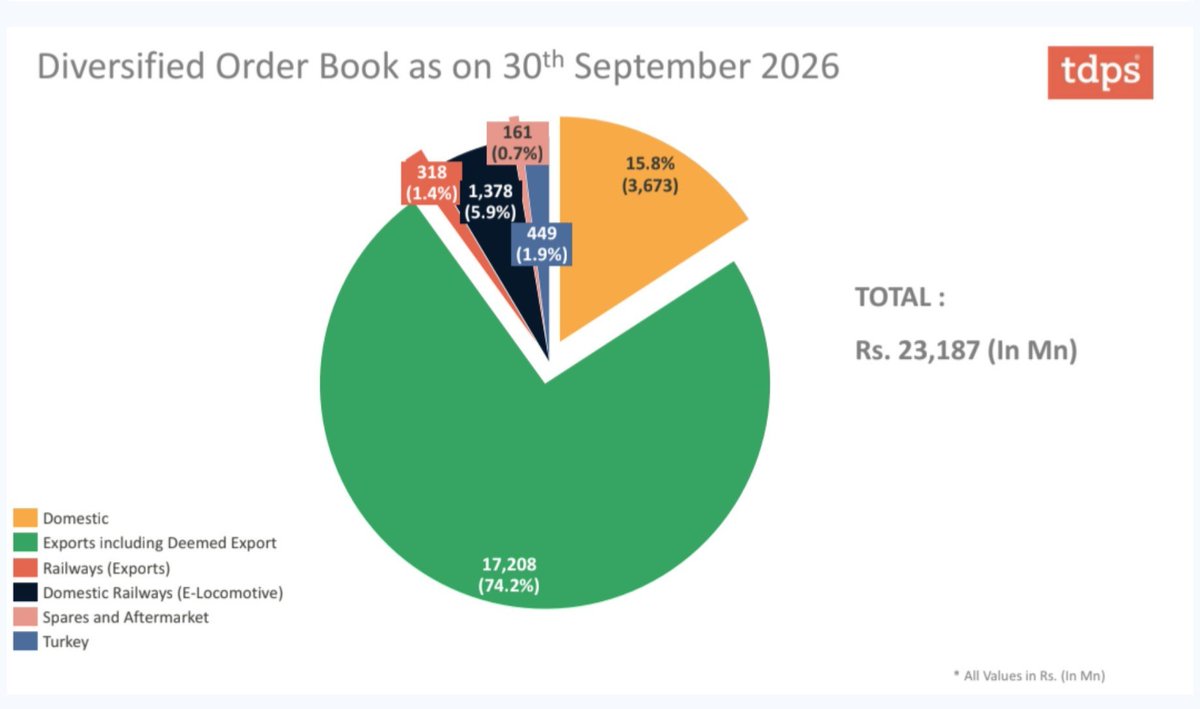
TD Power's order book stood at ₹2,319 crore as of September 30, 2026.
Order book composition:
• Exports (including deemed exports): ₹1,721 Cr (74.2%)
• Domestic: ₹367 Cr (15.8%)
• Domestic Railways (E-Locomotive): ₹138 Cr (5.9%)
• Turkey: ₹45 Cr (1.9%)
• Railways (Exports): ₹32 Cr (1.4%)
• Spares & Aftermarket: ₹16 Cr (0.7%)
What stands out:
International markets account for the largest share of the order book, with exports including deemed exports contributing 74.2%.
Domestic business contributes 15.8%, providing an additional market base.
Railway applications, Turkey and aftermarket add further diversification.
👉TD Power has a predominantly export-oriented order book, reflecting its global customer reach. The key monitorable remains timely execution and conversion of this sizeable order book into revenue.
No Reco.
#TDPS
#TDPOWERSYS
Manorama Industries | R&D: Beyond Manufacturing, Towards Customised Formulations💡
R&D is an important pillar of Manorama's growth strategy.
The company has built its innovation capabilities around four key areas:
1. Research Leadership
Led by Dr. Krishnadath Bhaggan, with a DSIR-certified research centre accredited by the Government of India.
2. Customisation
Developing application-specific solutions for food, confectionery, cosmetics and personal care.
3. Customer Co-creation
Working closely with customers' R&D teams to develop customised formulations.
4. Product Development
Moving from bench-scale experimentation to customer-ready formulations.
Why this matters:
Manorama's R&D platform is focused on developing customised specialty fat solutions rather than competing solely on standard products.
Its ability to innovate, customise and collaborate with global customers will be an important capability as it expands its value-added portfolio.
No Reco
#Manorama
TD Power Systems | Q2 FY27 Concall Updates: Demand visibility extends beyond 2030💡
1/ Guidance 🎯
• FY27 revenue guidance: 2,900–3,000 Cr.
• H2 revenue expected at 1,450–1,500 Cr, broadly equally split between Q3 and Q4.
• FY28 initial guidance: 3,400–3,500 Cr, with mgmt indicating a high likelihood of upward revision as visibility improves.💡
2/ Demand visibility
• Strong production slots and bookings reported beyond 2030.💡
• Monthly coordination with OEM customers on capacity, forecasts and execution.
• Customer forecasts for FY28–FY30 are being closely tracked.
• Most of the existing order book is executable over the next 12 months.
3/ Demand is broader than data centres
Strong demand across:
• India – steel industry, particularly 40–100 MW generators.
• Europe – grid stabilisation and waste-to-energy.
• Global markets – data centres and rising electricity requirements.
• Hydro – Nepal and Vietnam.
Mgmt believes its decade-long efforts in product diversification, global references and customer acceptance are now translating into greater market access.
4/ Siemens Energy partnership
• Orders have commenced for manufacturing two-pole generators on a bill-to-print basis for Siemens Energy's gas turbine business.
• New facility designed for larger generators in the 175–325 MW range.
• Major equipment orders largely placed; construction underway.
• Production ramp-up expected during FY28–FY29.
• Mgmt targets 70–80% utilisation by FY30.
Separately, TD Power is investing in its own design capabilities and manufacturing capacity for two-pole generators up to 100 MW.
5/ Capex:
• Fourth plant targeted to be ready by calendar Q1 2028; June 2028 is the absolute outer limit.
• Existing facilities are seeing better utilisation through automation, technology and efficiency improvements.
• Mgmt is evaluating incremental capacity for generators below 50–60 MW, potentially during 2029, depending on customer forecasts.
6/ Margins
~19% a sustainable near-term margin range.
• Initial costs associated with the new Siemens-related facility may temporarily weigh on margins before revenue ramps up.
• At 50–60% utilisation of the new plant, mgmt sees potential to move beyond 20%.
7/ Pricing and order momentum
• Pricing remains stable.
• Raw-material-linked price variation clauses protect margins against input-cost movements.🎯
• Quarterly order intake increased from approximately 700 Cr to 750 Cr.
• 50 Cr debottlenecking capex is supporting higher production capability.
• Generator production increased from approximately 320 units in Q1 to 400 units in Q2.
8/ Other opportunities💡
• Hydro biz has a strong inquiry pipeline, with additional large orders received in Q3.
• Nepal and Vietnam remain the two major hydro markets.
• Hydro margins are broadly similar to gas-generator margins.
• TD Power is exploring additional turbine models, engines and sizes within its existing OEM relationships.
• Mgmt sees combined-cycle generation as a future opportunity driven by energy-efficiency requirements, though not an immediate one.
9/ Long-term ambition💡
$1 billion topline is possible, without specifying a timeline.
It also discussed potential growth of 20–25%, but has not provided a formal multi-year revenue commitment.
What to monitor:
• Conversion of customer forecasts into firm orders.
• Execution of the Siemens Energy project.
• Capacity ramp-up and utilisation.
• Sustainability of ~19% margins during expansion.
• Growth in hydro and existing generator businesses.
Crux:
The growth opportunity is broadening beyond data centres, with multiple demand drivers across geographies and applications.
The next phase will be about converting customer visibility and capacity investments into actual revenue while maintaining margin discipline.
A business to watch closely for execution.
No Reco
#TDPOWERSYS
#MacpowerCNCMachines
The biggest growth trigger for Macpower will be the expansion of its manufacturing capacity through the new 13 acre land next to its existing plant. The facility is expected to become operational by the second quarter of FY28.
Currently, the biggest constraint is manufacturing capacity, not demand. The existing plant can produce around 2,500 machines annually, and management expects to deliver 2,300 to 2,400 machines this year. Interestingly, the company has to refund orders for 10 to 20 machines every month because it cannot deliver on time. This represents business it is unable to capture.
Demand remains strong. The pending order book stands at 476 crore, up 36 percent year on year, while bids worth 939 crore are in the pipeline. Q2 revenue reached a record 120 crore, growing 40 percent. Management has also raised its FY27 growth guidance from 30 percent to around 35 percent.
The new land is expected to address this capacity constraint and support 25 to 30 percent annual growth over the next three to four years. It will also allow the company to manufacture more components in house. The additional machine capacity will become clearer once management finalises the investment and machinery orders, expected in Q3.
There is also scope for margin improvement. Current EBITDA margin is around 16.6 percent, and management believes it can cross 20 percent as production scales up and in house manufacturing increases. Recent price hikes should also start reflecting in Q3. The company has no debt, around 30 crore in cash and follows an advance payment model before dispatch.
The larger 60 acre land parcel intended for defence related opportunities is a longer term story. Its development depends on the new Gujarat defence policy, which is still awaited. For now, management's priority is to execute the 13 acre expansion.
The key things to monitor are whether the new facility is completed on schedule and how much additional production capacity it creates. Until then, delivery constraints will continue to restrict growth, while higher salaries and other fixed costs associated with expansion could temporarily put pressure on margins.
📊 32 Microcap Stocks.
50%+ Sales Growth. 50%+ Profit Growth. All Trading Below 30 PE.
I screened for SME's with market caps above ₹300 crore, strong earnings growth & reasonable valuations.
Here are all 32 #stocks with their financials. 🧵👇
Worth Bookmarking for future reference.
#StocksToWatch #SMEStocks 🇮🇳