Drew, spare me the AI cosplay and take the time to READ. My questions are not AI-generated, and neither are my rebuttals.
You have "never spoken to McCabe" according to your own continuous admissions.
Brother, not to rain on your parade, but you have ZERO inside/prior/institutional knowledge (unless you are working with the SEC, I am 99% sure you are not), and therefore 0% chance to argue with anyone of us who does, with or without AI.
You are asserting conclusions about NBH’s ledger without access to it. But I hear your frustration.
I do have access to the information. I know exactly what FINRA did, when they did it, what they relied on, and, more importantly, what they did NOT do.
I now know where the gaps are, who made the calls, and why the record is thin.
MMTLP being cancelled doesn’t magically relocate causation.
NBH may be holding unresolved obligations now. That tells you where the mess landed, not who created it.
McCabe didn’t halt trading, nor did MMAT. NBH didn’t control resumption. FINRA did.
What do I know, right? Great progress is taking place, rejoice! With respect.
Why this is damning in the broader narrative
Lets put it all together:
The SEC’s public posture is that it PROTECTS investors, ensures FAIR markets, and applies the rules NEUTRALLY.
This FOIA shows that, without a shadow of a doubt, in a highly sensitive situation involving MMTLP/Next Bridge, the SEC:
1. Gave direct access to an industry lobby group representing broker-dealers.
2. Agreed to a closed-door consultation about a live S-1 filing that could expose unresolved loans and short activity.
3. Was explicitly warned that because of the FINRA halt, there were shares on loan that could not be recovered if the S-1 proceeded as proposed.
4. Followed up by trying to map who at FINRA and which transfer agent were involved, again via the industry group, not via independent investigation or public process.
In other words:
1. They knew the halt + S-1 mechanics had trapped investors and created unrecoverable lending positions.
2. They listened first and primarily to the broker-dealer side about operational and exposure concerns.
3. They did not create any transparent, investor-facing process to address or even acknowledge these conflicts.
@Tiggersdad2@palikaras Don't worry guy! I incinerated nothing at all. I made money with TRCH and kept some shares for the merger with MMAT... By the way, I trust @palikaras a thousand times more than a liar like you 😉
You are getting a little repetitive now (still in denial, I get it!).
This isn’t misdirection my Libertarian friend, it’s market structure 101. So here is my final attempt:
You’re STILL describing the transfer agent’s ledger, which tracks legal shares.
I explained THAT has nothing to do with the economic exposure created in modern markets.
so let’s go point by point:
You: “Transfer agents reconcile the share count each day”
YA WE KNOW! Correct, but irrelevant!
Transfer agents reconcile:
1. issued shares
2. registered holders
3. book-entry movements
They do not reconcile:
•internalized trades
•dark-pool matches
•swap-based exposure
•CFDs
•ex-clearing fails
•CNS netted obligations
•option-market-maker synthetic longs
•rehypothecation chains
NONE of that EVER touches the TA.
Even the SEC and FINRA explicitly state the TA sees ONLY the legal float, not economic activity.
YOU: “There can be no unreconciled imbalances”
This is factually FALSE. What kind of bubble do you live in?
Regulators themselves acknowledge:
•Fails do persist (Reg SHO)!
•Rolling FTDs are allowed!
•Synthetic long/short offsets exist!
•Internalization prevents reconciliation across venues!
•Dark pools do NOT update the lit order book!
•CNS nets positions without share delivery!
If imbalances were impossible, we WOULD NOT have:
•Threshold lists
•Buy-ins
•Special settlements
•400% short interest events (you know the stocks)
•Multi-year FTDs
•Large-scale share recalls
The historical record contradicts your claim.
YOU: “Synthetic shares that don’t touch the primary market can’t affect price”
Here’s the news flash that… my Libertarian friend is Economically impossible!
This shows your misunderstanding of price discovery mechanics.
Off-exchange trading ABSOLUTELY affects price because:
1. internalizers peg fills to NBBO (say what?)
2. dark pools use midpoint pricing (oh snap!)
3. ATS executions contribute to benchmark prices (holly freak!!)
4. derivatives bleed into spot via hedging (oh oh!)
5. arbitrage normalizes prices between venues (no, no, no!)
6. ETF market-making links basket components (yours bids at VIRTU, CITADEL etc)
7. futures and swaps push the underlying (those SoBs!)
You’re quoting the transfer agent handbook.
I’m quoting the SEC.
This isn’t theory, look at the SEC 2022 Market Structure Report (link https://t.co/0Di8kx40NM) :
The market-structure analysis makes one thing crystal clear:
When trading migrates off-exchange, the SEC directly states that off-exchange volume “may affect price discovery and the quality of market prices.”
Their words, not mine.
So let’s be adults:
Transfer agents reconcile legal shares.
Price discovery happens in the market, not in the registrar’s spreadsheet.
If you still think off-exchange activity has “no impact” on price…
take it up with the SEC,
because your argument isn’t with me.
It’s with the regulator you’re pretending to defend.
YOU: “People like you never have tangible data.”
Then YOU my Libertarian friend, simply haven’t looked.
The data is public:
•FINRA ATS volume reports
•Reg SHO FTD data
•Blue sheet data
•TRACE-equity pilot
•OCC delta-hedging impact
•NSCC CNS mechanics
•SEC dark-pool transparency filings
•Academic microstructure studies
•FINRA 2024 dark-pool transparency initiative
•SEC 2022 Market Structure Report
•DTCC SFT rule filings
•OATS / CAT reporting data
These sources OPENLY acknowledge:
•synthetic exposure
•non-delivery risk
•cross-venue fragmentation
•off-exchange price impact
•rehypothecation feedback loops
This is not fringe.
It is documented, regulated, and studied.
A humble suggestion to all, STOP describing legal share issuance.
START understanding and describing market microstructure.
They are not the same system, and that’s exactly the point MMTLP exposed verifiably acknowledging the need for #Bitcoin IMHO.
@CharrierChris56@E2Villiers@FDemocratie Et vous, avez vous compris que c'était de la dissuasion, tout comme le font Poutine et Trump avec leur grande gueule?
Ça ne suffit pas de nous faire humilier comme JD VANCE l'a fait devant une assemblée des "grands" d'Europe?
Update for $MMAT fellow shareholders: Our company is being dismantled before our eyes, potentially affecting other stakeholder matters. We have been kept in the dark for months. This knee-capping, in my opinion, does not benefit anyone and is a breach of fiduciary duties.
If you value your investment and the world-class technology still within the company, please take action.
FACT 1: After the 8-K announcing the 80% workforce reduction, I emailed the Board and proposed offering all my shares back to the treasury to help the company raise new capital and transition under new management.
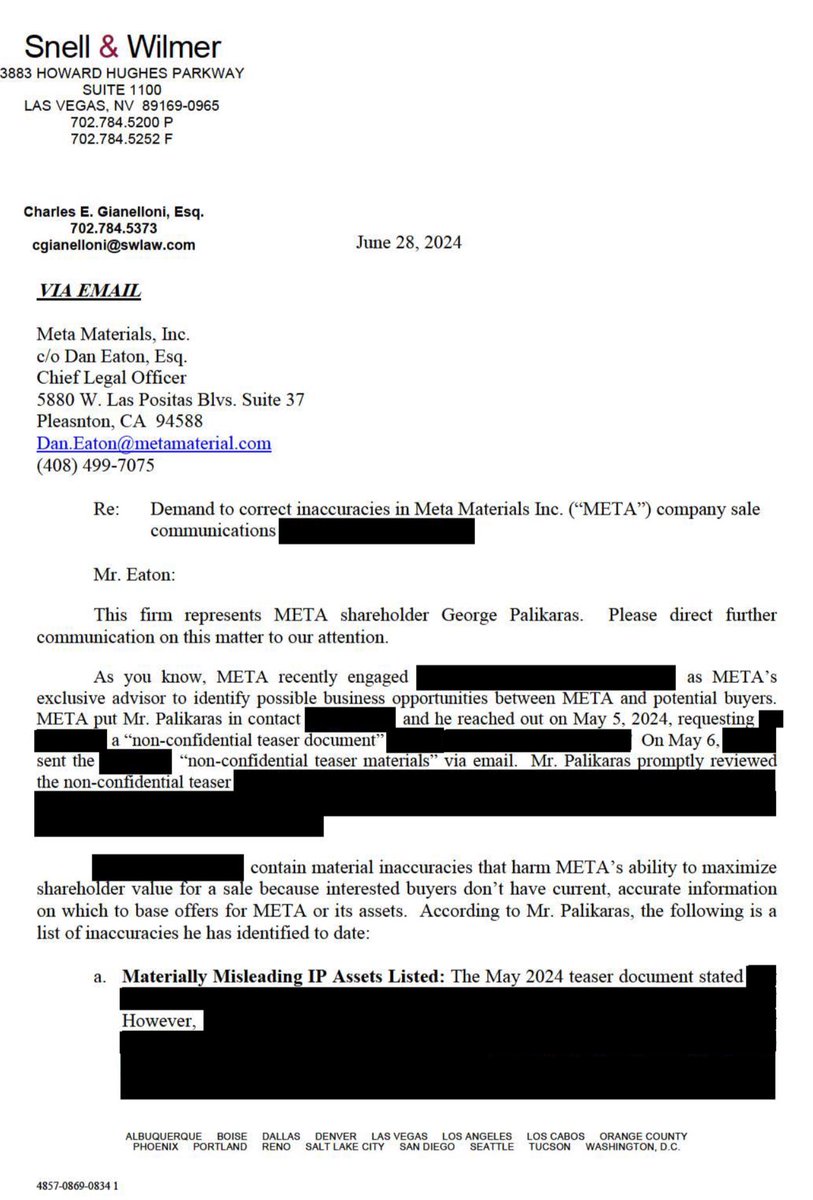
FACT 2: I have issued new demand letters through different law firms due to discrepancies and issues requiring urgent attention. Despite my efforts, there has been no support for resolution. I hereby permit the board and management to publicly share my demand letters and any responses in full.
FACT 3: I still hold the largest stake in the company and remain connected to shareholders, former employees, customers, and suppliers of @Metamaterialtec, many of whom are ready and willing to testify regarding MMAT’s management actions.
Rest assured, I am working every day with all my resources to save our company’s world-changing technologies and hold $MMAT Management accountable. Transparency is crucial. IMHO, the current Board and Management are only looking after themselves, are completely misaligned with our mission, and do not intend to create any shareholder wealth. This is evidenced by recent announcements, lack of transparency, lack of ownership, and many more indicators that will be revealed in time.
I urge @Metamaterialtec to RELEASE the non-confidential teaser document and reveal WHO the financial advisory firm is, reveal WHO the battery (NPORE) new asset owner is, describe WHAT the relationship (if any) with Authentix is, and then to do us a favor and RESIGN. Alternatively they risk becoming the first Board on Nasdaq that will lose three consecutive major shareholder proposals within 12 months. A temporary shareholder committee can be put in charge anytime. If the Nanotech asset deal cannot be reversed, the company will have forever lost its metamaterials foundry and its nanomaterials volume manufacturing platform capabilities worth over $150M in intrinsic/replacement value based on my estimates. Even so, a new, “META 2.0”can still re-emerge. This could be an AI-driven device tech company focused around the ElectroOptics (VLEPSIS) imaging technology (pixel-as-a-service), which, given enough time and scale, can become a Fortune 500 company.
Are you ready to stand with us and fight for the future of our company? My DMs are open to all. FYI, see the page extract below image for a little sample of one of the demand letters... One last FACT… the company’s website is showing a leadership team page where more than half of these people are already gone for weeks, WHY are shareholders mislead with such lies!??? #Accountability #Transparency #CorporateGovernance #knowWhatYouOwn @timaras
New Video 🎥 " $MMTLP: The Red Flags Ignored By The @SECGov". We know the SEC moves slow, but we also know that MMTLP has been on their radar since at least 2021!
Is the SEC taking the investigation seriously? Have they noticed the links between @FINRA, Ari Rubenstein & those that attempt to disparage the MMTLP Community?
One, two, or even three of these links could've been written off as a coincidence, but 1 by 1, after doing some digging they all appear to lead back to Ari Rubenstein & his companies.
Don't believe me? Just watch this short 10 minute video & see for yourself! @FBILosAngeles@FBIWFO@DOJCrimDiv@TheJusticeDept@SecretService@The_DTCC@RepRalphNorman@MikeCrapo@denniskneale@MetaGuyMarduk #MMTLPFiasco
Thank you for your message. It's crucial to understand that during my tenure as CEO and following the $MMTLP halt, my actions and decisions were guided by a commitment to the company's and all stakeholders' best interests. However, the changes on the Board introduced a paradigm shift in communication policies, directly impacting the nature and scope of information that could be disclosed which became extremely conservative in nature. Despite numerous efforts to maintain an open dialogue, these policy changes significantly restricted the ability to share insights as freely as I believed was necessary (this included the infamous NBH presentation promised and never delivered despite having a complete presentation deck ready to go). This was not a matter of personal preference but a directive from the new governance structure, which I was obliged to follow. The perception that I lacked interest in transparency is unfortunate and does not align with my values, intentions or efforts.