

Top Tweets for #TIMEtechnoplast

Drone jo hydrogen par udta hai 🚁
Time Technoplast Limited ka naya product. Kya yeh growth ka naya raasta hai?
4 raste, order book, shareholding aur profit vs cash ka aankdon par analysis.
Sirf educational, buy/sell salah nahi.
Link neeche 👇
#TimeTechnoplast

Time Technoplast Ltd receives order for supply of Composite LPG Cylinders for INR 38.14 Crore
#TimeTechnoplast #INE508G01029 #OrdersWin #CompositeLPGCylinders
https://t.co/MEbYjr5S8K

HPCL doubled the orders for #TimeTechnoplast

Fresh orders from HpCL. #TimeTechno


Time Technoplast 🔥🔥🔥 🚀
Up 7%
Can be 3X stock soon
#TimeTechnoplast

#Timetechnoplast guiding for 15+ volume growth for at least next 3 years resulting in operating leverage at PAT level
Vageria sir is a man on mission. What an execution over last 3-4 years with very high level of discipline and consistency.
The day markets start respecting 15% volume growth (we live in environment of any PE for high growth, no PE for fair growth), it would become a rerating candidate (already undergone some rerating in last price momentum cycle) for the kind of balance sheet and return ratio transformation company is going through. Till then bears will have way to justify why prices should remain down.
Disc: Biased from last 2+ years, itching to add more after a long time


#TimeTechnoplast
CMP :189


Loved the article on #TimeTechnoplast
@FinanceBrewRT has covered the story, including the commodity nature of business, working capital woes, well. Look forward to such balanced deep dives
https://t.co/oLnqCsUgbE
Time Techno Plast Ltd's subsidiary awarded annual contract by Methanol Chemicals COmpany
#TimeTechnoplast #INE508G01029 #Subsidiary #SaudiArabia #OrderWin #MethanolChemicalsCompany
https://t.co/1LSbTK4liT

#TimeTechnoplast
Wholly owned Saudi subsidiary wins Rs.35 crore annual supply contract from CHEMANOL, executable within one year.

#TimeTechnoplast #TIMETECHNO #Packaging #Composites #Q2FY27
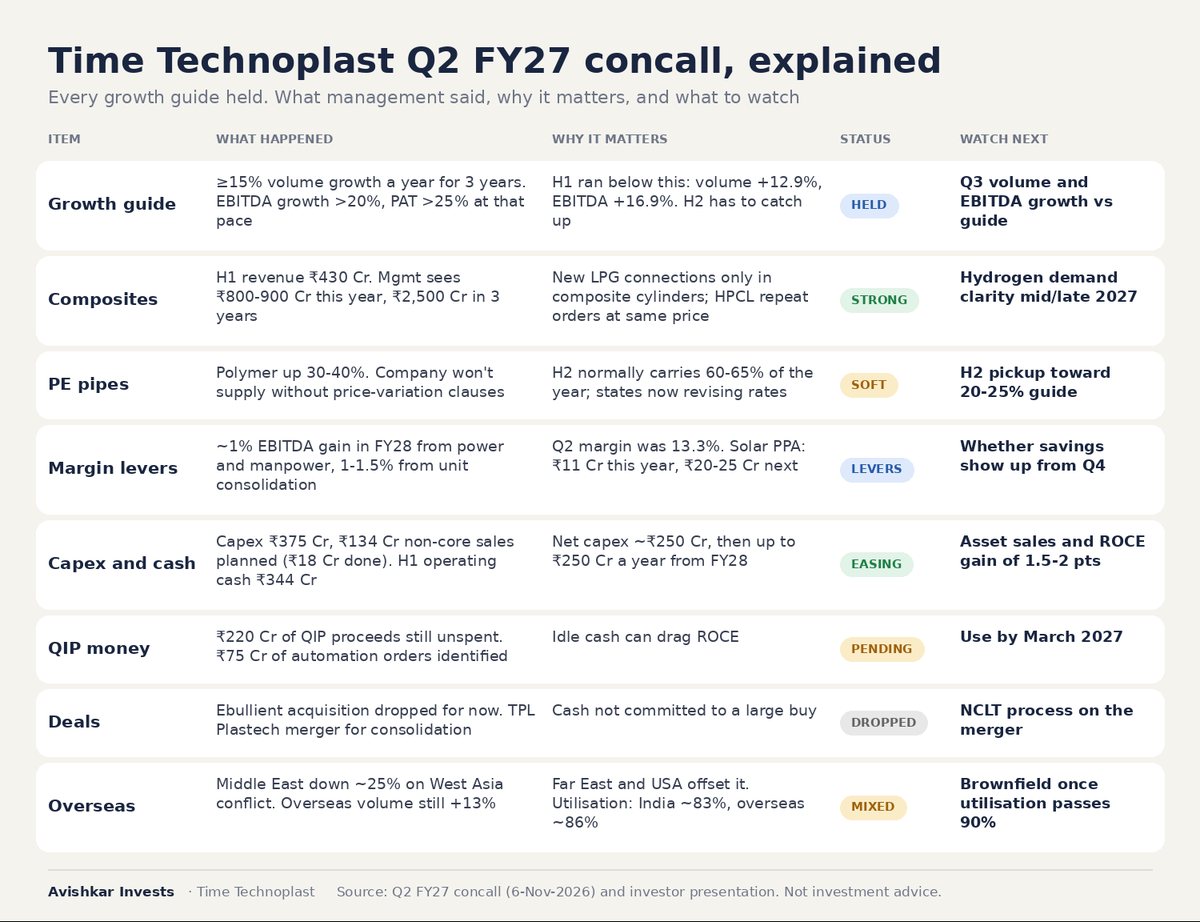
Time Technoplast, Q2 FY27 concall — management is holding every growth guide despite a below-guide H1, and says the margin fix comes from cost levers.
Growth: ≥15% volume growth a year for the next three years, with EBITDA growth above 20% and PAT growth above 25% at that volume. By segment: packaging 11–13%, composites 25–30%, pipes 20–25%, other 10–12%. H1 volume was +12.9% and EBITDA +16.9%, so H2 has to do the catching up.
Margins: management points to ~1% EBITDA margin gain in FY28 from power and manpower savings (solar PPAs worth ~₹11 Cr this year, ₹20–25 Cr next year) and another 1–1.5% from unit consolidation. Q2 margin was 13.3%. Automation capex is expected to add 1.5–2 points to ROCE.
Composites: the largest growth driver. H1 composites revenue ₹430 Cr. Management sees ₹800–900 Cr this year and ₹2,500 Cr in three years. New LPG connections are being offered only in composite cylinders because steel cylinder supply is suspended. HPCL repeat orders came at unchanged prices. Hydrogen cylinders: strong interest, but commercial demand clarity is mid-to-late 2027. The 14.2 kg LPG cylinder is delayed 3–4 months.
Pipes: weak so far. Polymer prices rose 30–40% and the company will not supply without price-variation clauses, which government EPC contracts often lack. Management says H2 normally carries 60–65% of the year and states are now revising rates.
Capital: total capex ₹375 Cr, with ₹134 Cr of non-core assets identified for sale (₹18 Cr done), so net ~₹250 Cr. From FY28, maintenance plus brownfield of up to ₹250 Cr. Capacity utilisation: India ~83%, overseas ~86%. ₹220 Cr of QIP money is still unspent (₹75 Cr of automation orders identified, to be used by March 2027). Net cash from operations ₹344 Cr in H1.
Ebullient Packaging acquisition: not proceeding for now, revisit in 2–3 years. TPL Plastech (75% subsidiary) merger aims at consolidation.
Overseas: Middle East business is down ~25% on the West Asia conflict, offset by Far East and USA, so overseas volume still grew 13%.
Not investment advice. Independent research, not SEBI-registered. DYOR.
#TimeTechnoplast #Packaging #Q2FY27
Time Technoplast, Q2 & H1 FY27 — record revenue, EBITDA and PAT, but growth quality is the thing to read closely.
Q2: income ₹1,996 Cr, +32.0% YoY.
EBITDA ₹265 Cr, +18.4%, margin 13.3% vs 14.8%.
PAT ₹146 Cr, +26.6%.
Volume +13.8%.
H1: income ₹3,690 Cr, +28.8%.
EBITDA ₹490 Cr, +16.9%, margin 13.3% vs 14.6%.
PAT ₹262 Cr, +24.6%.
Volume +12.9%.
Thing to focus on, is Volume growth, not revenue growth
Revenue is growing ~16 points faster than volume. Management says it passes polymer cost through on agreed formulas to hold absolute EBITDA, which lifts revenue but dilutes margin %.
Still, H1 volume (+12.9%) and EBITDA (+16.9%) both sit slightly below what management guided for FY27 (volume ~15%, EBITDA 19–20% growth). H2 can close the gap since guidance is a full-year number, so this is a watch item, not a miss.
Segments (H1, value): IBC ₹489 Cr (+30.7%), CNG cascades ₹274 Cr (+28.7%), LPG cylinders ₹118 Cr (+8%), packaging ex-IBC ₹2,471 Cr (+28.8%), PE pipes ₹173 Cr (+26.6%).
The balance sheet is clearly positive. Borrowings ₹558 Cr vs cash ₹594 Cr, so the company is now net cash (~₹36 Cr) against net debt of ~₹60 Cr in March. Operating cash flow ₹372 Cr in H1 against capex of ₹174 Cr. ROCE 18%.
Orders and corporate actions: → HPCL: 1,40,000 composite LPG cylinders, ~₹38 Cr → PSU Type-IV CNG cascade order, ~₹83 Cr → NTPC hydrogen cascade trial order, ₹2.5 Cr → Order book: CNG cascades ₹210 Cr, PE pipes ₹195 Cr, plus a ₹375 Cr packaging tender confirmed → Ebullient Packaging acquisition dropped; TPL Plastech merger board-approved, effective 1-Apr-2026 subject to NCLT
Question for the concall: is the margin dip pure input-cost pass-through, or is there pricing pressure?
Disclaimer: Not investment advice. Independent research, not SEBI-registered. DYOR.
#TimeTechnoplast #Packaging #Q2FY27
Time Technoplast, Q2 & H1 FY27 — record revenue, EBITDA and PAT, but growth quality is the thing to read closely.
Q2: income ₹1,996 Cr, +32.0% YoY.
EBITDA ₹265 Cr, +18.4%, margin 13.3% vs 14.8%.
PAT ₹146 Cr, +26.6%.
Volume +13.8%.
H1: income ₹3,690 Cr, +28.8%.
EBITDA ₹490 Cr, +16.9%, margin 13.3% vs 14.6%.
PAT ₹262 Cr, +24.6%.
Volume +12.9%.
Thing to focus on, is Volume growth, not revenue growth
Revenue is growing ~16 points faster than volume. Management says it passes polymer cost through on agreed formulas to hold absolute EBITDA, which lifts revenue but dilutes margin %.
Still, H1 volume (+12.9%) and EBITDA (+16.9%) both sit slightly below what management guided for FY27 (volume ~15%, EBITDA 19–20% growth). H2 can close the gap since guidance is a full-year number, so this is a watch item, not a miss.
Segments (H1, value): IBC ₹489 Cr (+30.7%), CNG cascades ₹274 Cr (+28.7%), LPG cylinders ₹118 Cr (+8%), packaging ex-IBC ₹2,471 Cr (+28.8%), PE pipes ₹173 Cr (+26.6%).
The balance sheet is clearly positive. Borrowings ₹558 Cr vs cash ₹594 Cr, so the company is now net cash (~₹36 Cr) against net debt of ~₹60 Cr in March. Operating cash flow ₹372 Cr in H1 against capex of ₹174 Cr. ROCE 18%.
Orders and corporate actions: → HPCL: 1,40,000 composite LPG cylinders, ~₹38 Cr → PSU Type-IV CNG cascade order, ~₹83 Cr → NTPC hydrogen cascade trial order, ₹2.5 Cr → Order book: CNG cascades ₹210 Cr, PE pipes ₹195 Cr, plus a ₹375 Cr packaging tender confirmed → Ebullient Packaging acquisition dropped; TPL Plastech merger board-approved, effective 1-Apr-2026 subject to NCLT
Question for the concall: is the margin dip pure input-cost pass-through, or is there pricing pressure?
Disclaimer: Not investment advice. Independent research, not SEBI-registered. DYOR.
#TimeTechnoplast #TIMETECHNO #CorporateGovernance #Subsidiaries
Part 3: Closing out the series with the corporate structure and governance side — five subsidiaries/corporate actions, plus the guidance track record and ownership table that didn't make the first two posts.
TPL Plastech (74.86%-owned, FY26 revenue ₹422.7 Cr) is being absorbed into the parent — we flagged the swap ratio as unannounced in Part 1, and it's since been confirmed: 403 Time Technoplast shares per 1,000 TPL Plastech shares, ~79.02 lakh new shares, roughly 1.6% dilution, effective 1-Apr-2026.
The Middle East 50% stake sale (~30% of overseas revenue, ~USD 25mn indicative value, JPMorgan/EY advising) is still open with no binding agreement. A new ₹50 Cr investment for 65% of Time Intercontinental Ltd — a promoter-promoted entity for raw-material sourcing — sits below the related-party materiality bar but is worth tracking.
Power Build Batteries (97.04%-owned, the Energy Storage arm covered in Part 2) absorbed NED Energy in 2025. And the proposed Ebullient Packaging acquisition, guided "firm" for March 2026, was dropped in August citing Middle East cost volatility.
On who's actually buying this: Industrial Packaging serves 900+ institutional customers across 11 countries — mostly chemical and process-industry buyers who specifically demand recognised brands, which is a real pricing-power moat since the company competes with only Schutz and Mauser globally in IBCs.
Composite Cylinders sells LPG cylinders to PSU oil marketing companies (IOCL, BPCL, HPCL — 20+ lakh supplied to IOCL alone) and CNG cascades across 22 City Gas Distribution entities.
PE Pipes goes to EPC contractors executing government schemes (Nal Se Jal, Smart City Mission, Swachh Bharat).
MOX Films/Technical Products supplies auto OEMs — Ashok Leyland, Tata Motors, Volvo — plus 450+ dealers for the Techpaulin consumer brand.
Worth flagging: the highest-margin composite segment leans heavily on PSU demand, and the company has previously seen tender delays tied to PSU leadership transitions.
On governance: MD and CFO roles are combined in one person, a structure that's been stable for years; board refresh in August was routine, not a pressure exit; promoter pay sits at 21.1x median employee pay, nothing unusual; auditors gave an unqualified FY26 opinion with no Section 143(12) fraud flag; CRISIL rates the company AA-/Stable and A1+.
The part worth sitting with is the guidance scorecard: of 9 tracked commitments since Q3 FY25, only 2 were met or are on track, 2 were outright missed (the debt-free timeline, and Ebullient), and 5 landed partial or below range. That's a moderate record, not a strong one — worth discounting future guidance by 10-15% until delivery improves. Promoter holding has fallen from 51.62% to 47.56% since the Nov-25 QIP, with DII ownership rising to fill the gap.
Not investment advice. Independent research, not SEBI-registered. DYOR.


👀 TIMETECHNO — Keep on Radar
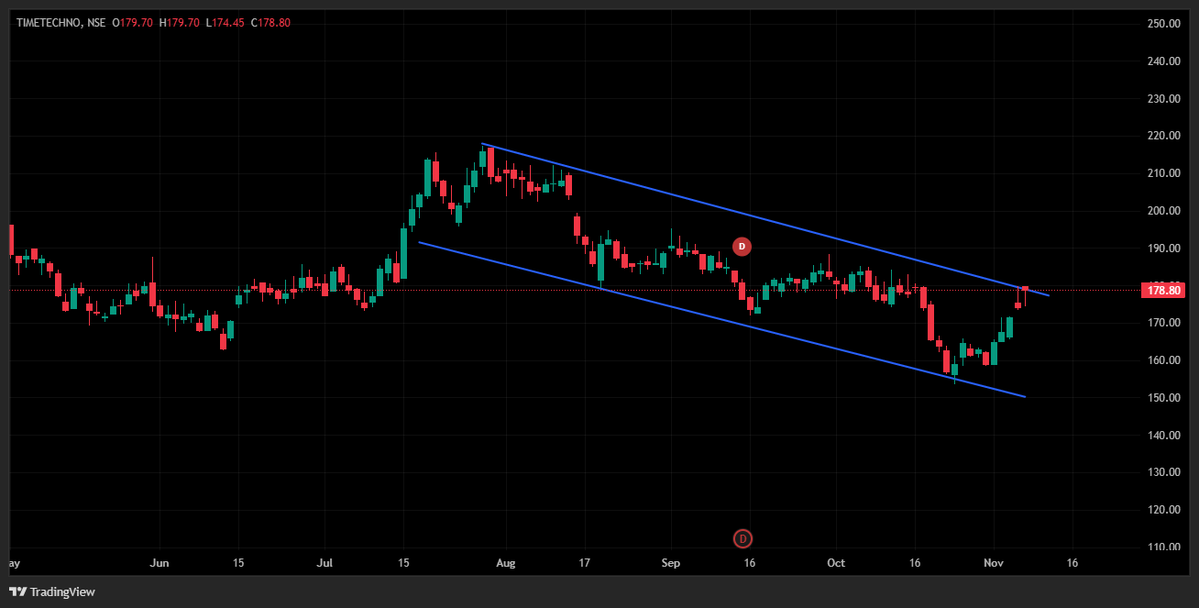
Watching above ₹181 for a potential breakout. Looking for sustained strength above this level. 📈
#TIMETECHNO #NSE #StockMarket #TimeTechnoplast #SupremeIndustries

📈Time Technoplast 📈
Chart - Monthly
Pattern - Flag
Stock to keep in watchlist 🥸
If it crosses 240 , the potential is there to cross 400
#investing #stocktowatch #timetechnoplast
https://t.co/rFJYbJyeMM
#TimeTechnoplast #TIMETECHNO #CorporateGovernance #Subsidiaries
Part 3: Closing out the series with the corporate structure and governance side — five subsidiaries/corporate actions, plus the guidance track record and ownership table that didn't make the first two posts.
TPL Plastech (74.86%-owned, FY26 revenue ₹422.7 Cr) is being absorbed into the parent — we flagged the swap ratio as unannounced in Part 1, and it's since been confirmed: 403 Time Technoplast shares per 1,000 TPL Plastech shares, ~79.02 lakh new shares, roughly 1.6% dilution, effective 1-Apr-2026.
The Middle East 50% stake sale (~30% of overseas revenue, ~USD 25mn indicative value, JPMorgan/EY advising) is still open with no binding agreement. A new ₹50 Cr investment for 65% of Time Intercontinental Ltd — a promoter-promoted entity for raw-material sourcing — sits below the related-party materiality bar but is worth tracking.
Power Build Batteries (97.04%-owned, the Energy Storage arm covered in Part 2) absorbed NED Energy in 2025. And the proposed Ebullient Packaging acquisition, guided "firm" for March 2026, was dropped in August citing Middle East cost volatility.
On who's actually buying this: Industrial Packaging serves 900+ institutional customers across 11 countries — mostly chemical and process-industry buyers who specifically demand recognised brands, which is a real pricing-power moat since the company competes with only Schutz and Mauser globally in IBCs.
Composite Cylinders sells LPG cylinders to PSU oil marketing companies (IOCL, BPCL, HPCL — 20+ lakh supplied to IOCL alone) and CNG cascades across 22 City Gas Distribution entities.
PE Pipes goes to EPC contractors executing government schemes (Nal Se Jal, Smart City Mission, Swachh Bharat).
MOX Films/Technical Products supplies auto OEMs — Ashok Leyland, Tata Motors, Volvo — plus 450+ dealers for the Techpaulin consumer brand.
Worth flagging: the highest-margin composite segment leans heavily on PSU demand, and the company has previously seen tender delays tied to PSU leadership transitions.
On governance: MD and CFO roles are combined in one person, a structure that's been stable for years; board refresh in August was routine, not a pressure exit; promoter pay sits at 21.1x median employee pay, nothing unusual; auditors gave an unqualified FY26 opinion with no Section 143(12) fraud flag; CRISIL rates the company AA-/Stable and A1+.
The part worth sitting with is the guidance scorecard: of 9 tracked commitments since Q3 FY25, only 2 were met or are on track, 2 were outright missed (the debt-free timeline, and Ebullient), and 5 landed partial or below range. That's a moderate record, not a strong one — worth discounting future guidance by 10-15% until delivery improves. Promoter holding has fallen from 51.62% to 47.56% since the Nov-25 QIP, with DII ownership rising to fill the gap.
Not investment advice. Independent research, not SEBI-registered. DYOR.
#TimeTechnoplast #TIMETECHNO #CapEx #ManufacturingIndia
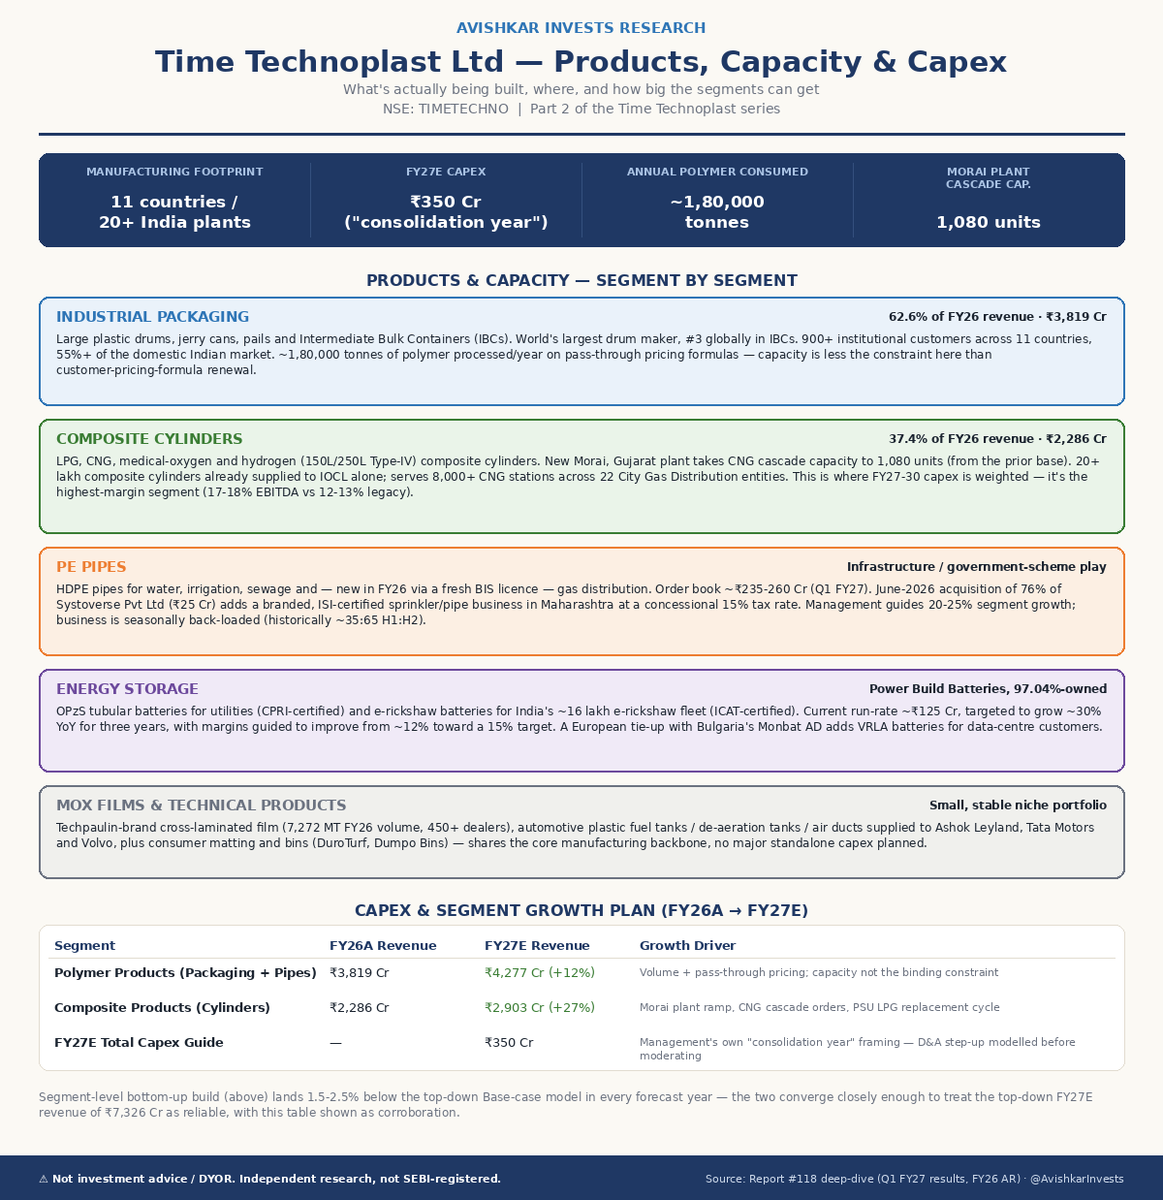
Following up on the funnel post below: here's what's actually being built, where, and how big each segment can get.
1. Industrial Packaging runs on scale, not fresh capacity — 11 countries, 20+ India plants, ~1,80,000 tonnes of polymer processed a year, 55%+ of the domestic market. The constraint here is customer pricing-formula renewal, not physical capacity, and FY27E revenue is guided to grow at a steady 12% (₹3,819 Cr → ₹4,277 Cr).
2. Composite Cylinders is where the capex is actually going. The new Morai, Gujarat plant takes CNG cascade capacity to 1,080 units, and this segment is guided to grow 27% (₹2,286 Cr → ₹2,903 Cr) — more than double the packaging growth rate, and at 17-18% EBITDA margins versus 12-13% for legacy packaging.
3. PE Pipes picked up a bolt-on in June: 76% of Systoverse Pvt Ltd (₹25 Cr) for a branded, ISI-certified sprinkler/pipe business in Maharashtra at a concessional 15% tax rate. Order book sits at ~₹235-260 Cr, management guides 20-25% segment growth, and the business is seasonally back-loaded — historically ~35:65 H1:H2.
4. Energy Storage (97.04%-owned Power Build Batteries) is the smaller, specialised bet — OPzS tubular batteries for utilities and e-rickshaw batteries for India's ~16 lakh e-rickshaw fleet, run-rate ~₹125 Cr, targeted to grow ~30% YoY for three years with margins improving from ~12% toward 15%. MOX Films and technical products round out the portfolio as a small, stable, no-major-capex niche.
5. The headline number for FY27: total capex guided at ₹350 Cr, which management itself frames as a "consolidation year" rather than a fresh expansion cycle — most of that capital is going toward the composite-cylinder ramp.
Not investment advice. Independent research, not SEBI-registered. DYOR.
#TimeTechnoplast #TIMETECHNO #CapEx #ManufacturingIndia
Following up on the funnel post below: here's what's actually being built, where, and how big each segment can get.
1. Industrial Packaging runs on scale, not fresh capacity — 11 countries, 20+ India plants, ~1,80,000 tonnes of polymer processed a year, 55%+ of the domestic market. The constraint here is customer pricing-formula renewal, not physical capacity, and FY27E revenue is guided to grow at a steady 12% (₹3,819 Cr → ₹4,277 Cr).
2. Composite Cylinders is where the capex is actually going. The new Morai, Gujarat plant takes CNG cascade capacity to 1,080 units, and this segment is guided to grow 27% (₹2,286 Cr → ₹2,903 Cr) — more than double the packaging growth rate, and at 17-18% EBITDA margins versus 12-13% for legacy packaging.
3. PE Pipes picked up a bolt-on in June: 76% of Systoverse Pvt Ltd (₹25 Cr) for a branded, ISI-certified sprinkler/pipe business in Maharashtra at a concessional 15% tax rate. Order book sits at ~₹235-260 Cr, management guides 20-25% segment growth, and the business is seasonally back-loaded — historically ~35:65 H1:H2.
4. Energy Storage (97.04%-owned Power Build Batteries) is the smaller, specialised bet — OPzS tubular batteries for utilities and e-rickshaw batteries for India's ~16 lakh e-rickshaw fleet, run-rate ~₹125 Cr, targeted to grow ~30% YoY for three years with margins improving from ~12% toward 15%. MOX Films and technical products round out the portfolio as a small, stable, no-major-capex niche.
5. The headline number for FY27: total capex guided at ₹350 Cr, which management itself frames as a "consolidation year" rather than a fresh expansion cycle — most of that capital is going toward the composite-cylinder ramp.
Not investment advice. Independent research, not SEBI-registered. DYOR.
#TimeTechnoplast #TIMETECHNO #PlasticProducts #IndustrialPackaging
Time Technoplast has spent three decades replacing metal with plastic — and the business model is literally a funnel: each layer funds the one above it.
1. Industrial Packaging is the cash engine — world's largest plastic-drum maker, #3 globally in Intermediate Bulk Containers, 55%+ of the domestic Indian market, ₹3,819 Cr of FY26 revenue (62.6% of the total). That cash funds Composite Cylinders, the growth-and-margin engine: world's #2 maker of Type-IV composite cylinders, ₹2,286 Cr FY26 revenue, running 17-18% EBITDA margins versus 12-13% for legacy packaging. And that, in turn, funds the newer, smaller bets — PE Pipes (order book ~₹235-260 Cr), Energy Storage (~₹125 Cr run-rate) and MOX Films/technical products.
2. The growth catalysts sit mostly in the middle layer: India has ~50 crore LPG cylinders in circulation on a 15-year replacement cycle — roughly 3 crore cylinders a year of addressable demand, with 20+ lakh composite cylinders already supplied to IOCL alone. CNG cascades serve 8,000+ stations, and a new Gujarat greenfield plant lifts cascade capacity to 1,080 units. There's a genuine optionality leg too — Time Technoplast is the first in India with PESO approval for Type-IV hydrogen storage cylinders, an early bet on the hydrogen economy. PE Pipes rides government infra schemes (Nal Se Jal, Smart City Mission) plus a fresh FY26 gas-distribution licence.
3. Worth being honest about the watch items, not just the story: FY26 free cash flow actually turned negative (-₹137 Cr) on inventory hedging and working-capital build, partially reversing in Q1 FY27. The "debt-free" framing nets off ₹342 Cr of unutilised QIP cash sitting in FDs — gross balance-sheet debt is still ~₹639 Cr. Update on the TPL Plastech merger: the swap ratio is now announced (board decision 29-Sep) — 403 Time Technoplast shares for every 1,000 TPL Plastech shares, ~79.02 lakh new shares to be issued, works out to roughly 1.6% dilution on the current share base. That's modest — this one's resolved, and smaller than it looked while open guidance credibility is moderate — only 2 of 9 tracked guidance items were met or beaten, and the Ebullient Packaging acquisition was guided firm, then reversed.
A genuinely interesting, self-funding business model — just one where the growth catalysts and the watch items both deserve equal airtime.
Not investment advice. Independent research, not SEBI-registered. DYOR.

#TimeTechnoplast #TIMETECHNO #PlasticProducts #IndustrialPackaging
Time Technoplast has spent three decades replacing metal with plastic — and the business model is literally a funnel: each layer funds the one above it.
1. Industrial Packaging is the cash engine — world's largest plastic-drum maker, #3 globally in Intermediate Bulk Containers, 55%+ of the domestic Indian market, ₹3,819 Cr of FY26 revenue (62.6% of the total). That cash funds Composite Cylinders, the growth-and-margin engine: world's #2 maker of Type-IV composite cylinders, ₹2,286 Cr FY26 revenue, running 17-18% EBITDA margins versus 12-13% for legacy packaging. And that, in turn, funds the newer, smaller bets — PE Pipes (order book ~₹235-260 Cr), Energy Storage (~₹125 Cr run-rate) and MOX Films/technical products.
2. The growth catalysts sit mostly in the middle layer: India has ~50 crore LPG cylinders in circulation on a 15-year replacement cycle — roughly 3 crore cylinders a year of addressable demand, with 20+ lakh composite cylinders already supplied to IOCL alone. CNG cascades serve 8,000+ stations, and a new Gujarat greenfield plant lifts cascade capacity to 1,080 units. There's a genuine optionality leg too — Time Technoplast is the first in India with PESO approval for Type-IV hydrogen storage cylinders, an early bet on the hydrogen economy. PE Pipes rides government infra schemes (Nal Se Jal, Smart City Mission) plus a fresh FY26 gas-distribution licence.
3. Worth being honest about the watch items, not just the story: FY26 free cash flow actually turned negative (-₹137 Cr) on inventory hedging and working-capital build, partially reversing in Q1 FY27. The "debt-free" framing nets off ₹342 Cr of unutilised QIP cash sitting in FDs — gross balance-sheet debt is still ~₹639 Cr. Update on the TPL Plastech merger: the swap ratio is now announced (board decision 29-Sep) — 403 Time Technoplast shares for every 1,000 TPL Plastech shares, ~79.02 lakh new shares to be issued, works out to roughly 1.6% dilution on the current share base. That's modest — this one's resolved, and smaller than it looked while open guidance credibility is moderate — only 2 of 9 tracked guidance items were met or beaten, and the Ebullient Packaging acquisition was guided firm, then reversed.
A genuinely interesting, self-funding business model — just one where the growth catalysts and the watch items both deserve equal airtime.
Not investment advice. Independent research, not SEBI-registered. DYOR.

#TIMETECHNOPLAST 1M. Timeframe.
#TimeTechno is currently in wave 4 of wave 3 and is forming a triangle pattern in wave 3.4
Entry - 155 to 180
Target - 290/340/370
SL - 150 (Weekly/Monthly Close basis)
#Nifty50 #Stockmarket #Nifty #StockmarketCrash #SmallCap #MidCap #ChartPattern #ElliotWave #Crash #MarketCrash


Briefs: Asian Paints, Time Technoplast and Grasim Industries
https://t.co/IrLFE95MHc
#AsianPaints #TimeTechnoplast #GrasimIndustries
@asianpaints @Timetechnoplast @GrasimInd

#TimeTechnoplast commissions 6,000-tonne greenfield packaging plant in #Bhilad, #Gujarat
@jpullokaran
https://t.co/xVFa1LXbnN


#Orders Snapshot – Aug 31, 2026
✅ #E2ENetworks – ₹1,000 Cr
NVIDIA Blackwell cloud GPUs & allied services for an Indian sovereign AI company
🕒 Valid until June 2029
✅ #NCC – ₹430.19 Cr
3 orders for the Buildings Division
✅ #TimeTechnoplast – ₹87.53 Cr
Type IV Composite CNG Mobile Storage Cascades for CNG/CGD network
🕒 Duration: 1 year
✅ #IndoTech – ₹54 Cr + taxes
Manufacture & supply of 5 power transformers to Waaree Renewable Technologies
🕒 Execution: Jan–Apr 2027
✅ #RaajMedisafe – ₹17.02 Cr
Supply of 29.88 lakh baby diapers to MP government hospitals
🕒 Duration: 18 months
🔔 Real-time Order alerts on WhatsApp → https://t.co/EfLItBaWTb
Most Popular Users

Elon Musk 
@elonmusk
240.5M followers

Barack Obama
@barackobama
118.7M followers

Cristiano Ronaldo
@cristiano
114.4M followers

Donald J. Trump
@realdonaldtrump
111.8M followers

Narendra Modi
@narendramodi
107M followers

Rihanna
@rihanna
98.7M followers

NASA
@nasa
92.2M followers

Justin Bieber
@justinbieber
91.8M followers

KATY PERRY
@katyperry
90M followers

Taylor Swift
@taylorswift13
84M followers

Lady Gaga
@ladygaga
75.5M followers

Virat Kohli
@imvkohli
73.4M followers

Kim Kardashian
@kimkardashian
70.8M followers

YouTube
@youtube
68.7M followers

Neymar Jr
@neymarjr
66.3M followers

Bill Gates
@billgates
65.2M followers

Selena Gomez
@selenagomez
63M followers

The Ellen Show
@theellenshow
62.1M followers

CNN
@cnn
61.7M followers

X
@x
60.6M followers