Agents pay software by the call and trust it on faith. Don't trust software. Make it post bond.
$IBOND is live on Robinhood Chain: backing capital for 25 services probed every minute, paid in premium, burned on a breach.
CA:
0x7232e31dd05eed7b945d1a6bc52a3077aba4becb
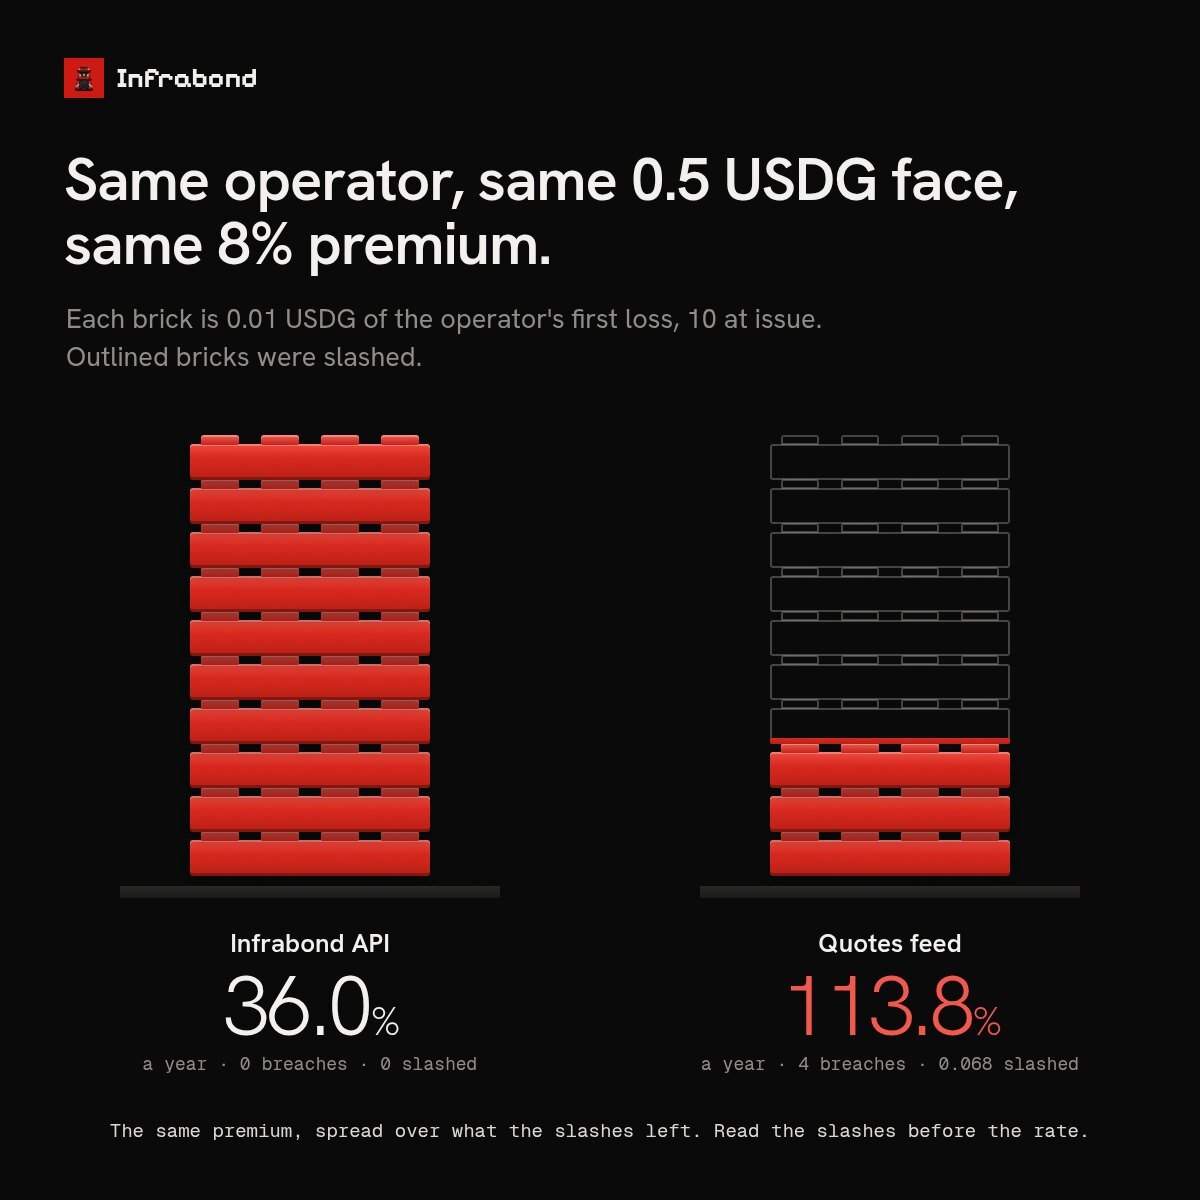
Same operator, same 0.5 USDG face, same 8% premium.
The Infrabond API leg reads 36.0% a year with 0 breaches. The quotes feed reads 113.8%, because 4 breaches slashed 0.068 USDG and the same premium now sits on a third of the first loss. Read the slashes before the rate.
No adjuster. Canary, Oct 6, UTC: first failed probe 18:11, onchain 18:20:09, epoch closed 19:00, then the contract's 2 h wait.
Settled 21:00:27, payout list 21:00:36, 0.015 USDG at the customer 21:00:38: 11 seconds from settlement to cash. $IBOND slashes keep the same clock.
The canary is the house service built to break. 98 measured hours, 5,826 probes, 31 failed: 30 in the half hour we switched it off on Oct 6 (3% slashed), 1 on its own on Oct 9 (10 bps, 0.000285 USDG).
Both settled onchain by the same formula $IBOND legs answer to.
The quotes feed over the last 22 hours, one brick a minute: 1,329 probes, 1 failed (15:51 UTC, an RPC error). It promises 99.5% a day, so it can miss 7 of 1,440 before a cent of its bond moves.
Every $IBOND leg sits on a wall like this one.
Two ways for an agent to read SEC filings. EDGAR direct: 100% up in the last 24 h, nothing behind it. The filings feed, same source: 99.5% promised in writing, 0.5 USDG face, and its 3 breaches cost its operator 0.044 USDG. $IBOND backs the second kind.
When AWS EC2 misses its SLA, you get 10%, 30% or 100% of that month's bill as credit on future bills, and you file the claim with your logs.
When a bonded service breaks its promise, its payers get USDG, up to 3x what they paid, by formula.
IBOND backs that bond.
Every parameter change waits 48 hours, and none of them can move capital.
New probers and every setting wait in a public queue, each inside bounds written in the contract, and none of it can touch bond capital, premium balances or what customers are owed.
The IBOND address is bound once.
A promise here is a number: availability at or above a target, p95 latency under a ceiling, freshness against a public reference. Each failed probe past the allowance costs 10 bps, each hour over the latency target 50 bps.
$IBOND behind it burns by the same formula.
Every service on the board is probed once a minute. Results go onchain every 10 minutes, 144 times a day, each tied to a block seen just before the probe.
If 50% of services fail in the same window it is voided, so the prober's own outage can't slash an $IBOND leg.
Whoever paid a service during a breached epoch is compensated in USDG, up to 3 times what they paid, from the slash. Payers are read from public USDG transfers, the claim comes with a proof anyone can recompute, and the leftover goes to the reserve. $IBOND
Measured in public, paid in private. Name a one-time payout address with a payment and compensation lands there, unlinkable in the records to the wallet that paid. A sealed service shows only a commitment, never its URL. Accounts are passkeys: no email, no KYC. $IBOND
A real breach, on the record. Epoch 0 on the canary: 30 of 60 probes failed against a 99% promise, 3% of its bond was slashed, and the customer who had paid 0.009 USDG that hour claimed 0.015 USDG onchain. That is the path $IBOND backers and operators sign up for.
What an $IBOND backer earns and what they risk. The operator posts at least 20% of every leg as first loss, before any backer joins, and loses it first. A slash is capped at 30% of a leg per epoch. Exits wait for the next settlement, so nobody leaves ahead of a breach.
A breach burns $IBOND.
Each failed probe beyond the allowance slashes 10 bps of the bond, up to 30% of a leg per epoch. The slice on the $IBOND leg goes to the dead address, the operator's first-loss $IBOND first, then the backers' pro-rata. The contract does it at settlement, and nobody approves it.
The $IBOND loop.
Agents pay a bonded service in USDG. Its operator streams premium to the backers. Every Pons trade's creator fee goes to the bond book and is paid in ETH to $IBOND backers, pro-rata. A breach pays the customers and burns $IBOND, so backing a flaky service costs its backers.
What $IBOND does: you put it in the $IBOND leg of a service you believe in and earn that leg's share of the service's premium, in USDG, by the second.
90% of every premium goes to the legs, 10% to the reserve. The canary's backers earn 31.61% a year.
Paid in private, on the live docs page.
The browser makes a one-time payout address and the payment's own signature binds it. Paste a URL and it seals: the chain only ever sees the commitment. Compensation lands at the new address, and the relayer pays its gas. $IBOND
The board, live.
25 services probed every minute, 4 with money behind them. Each row is the promise, the capital, what backers earn and what was slashed in 30 days, and each amber cell is a probe that passed. $IBOND backs a service the same way USDG does.
Here is Infrabond the way a backer uses it.
Open the board, pick the canary, read its record: a probe every minute, 31.61% a year to its backers, the operator's own 0.0847 USDG first in line. When it broke, 3% was slashed and the customer was paid. On the $IBOND leg, that slash burns.