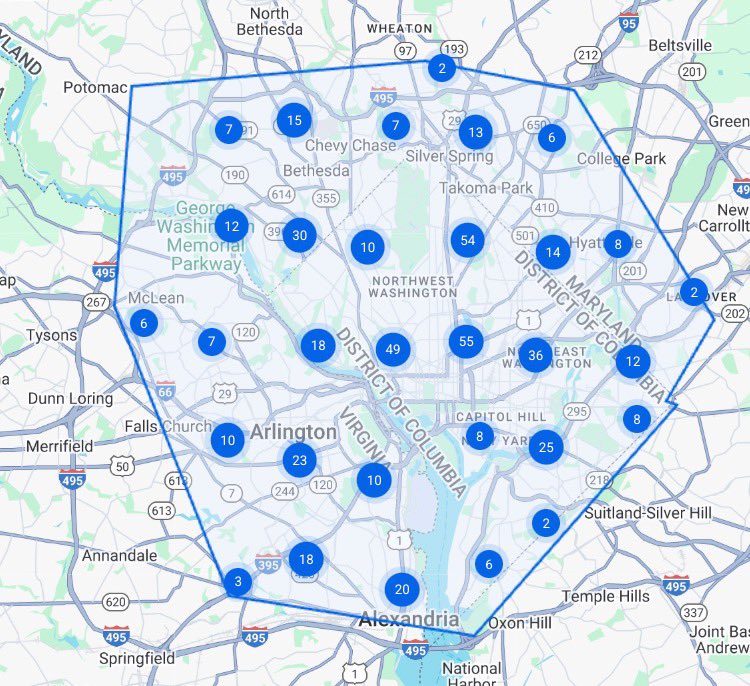
@ekaneomics@mikebolen I pulled it through Compass which is the brokerage we are at. It pulls directly through bright mls.
Shoot me an email and we can discuss other data you want to see and I can get it for you.
[email protected]
@JimHansonDC New active listings are Down.
If you compare 7 days YOY:
389 listings went active 2/10-2/16 2025
433 listings went active 2/10-2/16 2024
If you compare last 30 days:
1,670 listings went active 1/16-2/16 2025
1,829 listings went active 1/16-2/16 2024
Subject area used
@Ravious101 New active listings are actually Down.
If you compare 7 days YOY:
389 listings went active 2/10-2/16 2025
433 listings went active 2/10-2/16 2024
If you compare last 30 days:
1,670 listings went active 1/16-2/16 2025
1,829 listings went active 1/16-2/16 2024
Subject area used
@VladTheInflator New active listings are actually Down.
If you compare 7 days YOY:
389 listings went active 2/10-2/16 2025
433 listings went active 2/10-2/16 2024
If you compare last 30 days:
1,670 listings went active 1/16-2/16 2025
1,829 listings went active 1/16-2/16 2024
Subject area used
@merissahansen17 New active listings are actually Down.
If you compare this week year over year:
389 listings went active 2/10-2/16 2025
433 listings went active 2/10-2/16 2024
If you compare last 30 days:
1,670 listings went active 1/16-2/16 2025
1,829 listings went active 1/16-2/16 2024
@americananarcho@TomEllsworth If you compare this data Year over Year there were Less new listings that came on the market in the dc area compared to last year. That does not support a massive sell off of properties. Could that change? Yes. But as of now the numbers do not support a massive sell off from DOGE
@TomEllsworth If you compare this week year over year.
389 listings went active 2/10-2/16 2025
433 listings went active 2/10-2/16 2024
If you compare last 30 days
1,670 listings went active 1/16-2/16 2025
1,829 listings went active 1/16-2/16 2024
@elonmusk Well the entire “state” is more like a city. If you compare metropolitan areas by GDP the dc area is #6 behind NY, LA, Chicago, San Francisco, Dallas.
A suggestion would be 3% agent credit + 1% closing cost credit to buyer for ratified contract before ____.
Most agents want to get their client a good deal. It also gives them a good reason to ping their client about the property as a closing cost credit can really help buyers in a high interest rate environment.
This is to get the attention of the agent and make them really ponder if they have a client that could be a fit.
In theory it could drive more eyeballs to the property, and will stand out as many new developments offer 0-1.5% leaving signed buyer clients sometimes footing the bill to make up the difference.
Buyers agents will need to discuss up front more clearly their minimum fee (2.5%+ or whatever they make as a business decision). Then if sellers on a particular transaction are paying less than that, I would work into the buyer’s offer a closing cost credit to cover the difference, or language stating (seller to pay agent an additional $____ at settlement out of their net proceeds.
Why will this happen? Many buyers, especially first time buyers don’t have the cash to cover proper representation, and many sellers have the equity to pay it out of their proceeds.