Food plus labor is your prime cost, and it's the number that decides whether a busy night paid. Free Restaurant Prime Cost calculator, and a free profile saves your numbers:
https://t.co/6Oca6Cxh6Z
Restaurant owner, Saturday 11 PM:
"We were slammed. Great night."
Same owner, Monday, looking at the food and labor bills:
"...wait, how much of that was actually ours?"
Busy is a good sign. It's not the same as a good week.
Booked solid and still coming up short? Hypothetical lawn crew: $9,000 a month in fixed costs, $55 a mow, $19 in gas, labor and blades. That's 250 mows a month just to break even. Find yours free: https://t.co/CgrNC1zp5i
Every chair booked Saturday doesn't mean profit. Hypothetical salon: $12,000 a month fixed, $45 gel manicure, $21 to commission and supplies. That's 500 services a month just to break even. Find yours free at https://t.co/RvFWVBst0z (Break-Even calculator).
Before: "My truck costs $1.35 a mile. A $2.00 load is good money."
Month ends. $2,500 left for him.
After: he counts the 2,000 empty miles and his own $6,000 paycheck.
Real number: $2.44 per loaded mile.
Same truck. Different math.
(Hypothetical owner-operator)
3 things to check before December:
1. Bills that land in Dec and Jan. Insurance renewals, annual licenses, holiday payroll, the January tax payment.
2. Your slow months. Circle them now.
3. Who still owes you. Chase it before everybody checks out for the holidays.
What's ROI, in plain English?
Did the thing you bought pay you back?
Hypothetical plumber buys a $6,000 drain camera. First year, it brings in $9,000 of profit after labor and materials.
$9,000 ÷ $6,000 = 150% ROI. Paid for itself in 8 months.
Myth: "There's money in the bank, so we're making money."
That balance could be a deposit for a job you haven't done yet. Sales tax you owe in January. A bill you haven't paid.
Cash tells you what you have today. Profit tells you if the work is worth doing.
Run your own loan before you sign: amount, rate, term, SBA fee. Create a free profile and every calculator remembers your numbers.
https://t.co/uu3Fpcvj9m
$150K sounds like a lot of money.
It's a monthly payment you owe for 10 years.
Hypothetical $150K SBA 7(a) loan, 10.5% example rate:
10 years: $2,070/mo, $101,460 total interest
25 years: $1,476/mo, $295,678 total interest
A lower payment means almost triple the interest.
Things owners say:
"I'll pay myself when things slow down."
"I'll pay myself after the new truck."
"I'll pay myself next year."
Things never slow down.
Before you apply for a loan, know your DSCR.
Net operating income ÷ yearly loan payments.
Hypothetical plumbing shop:
$100,000 ÷ $80,000 = 1.25
Add a new $12,000-a-year payment:
$100,000 ÷ $92,000 = 1.09
Same shop. Weaker ask. Your lender sets the target, so ask what it is.
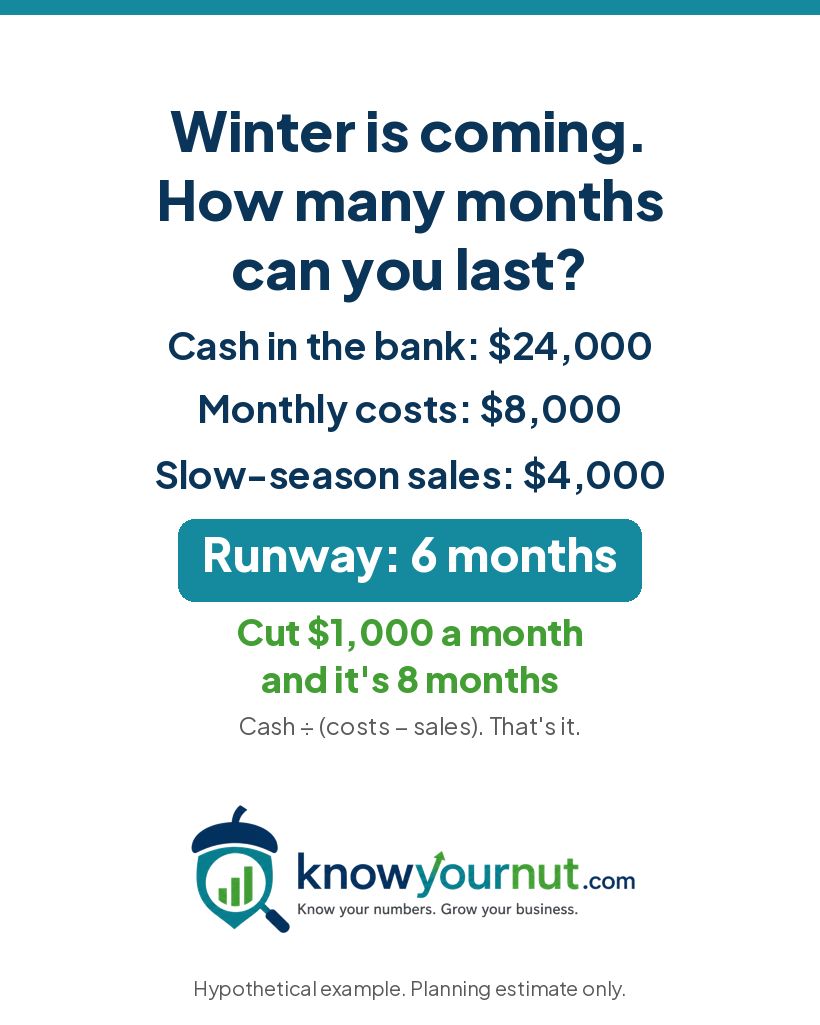
Slow season math, hypothetical crew:
$24,000 in the bank
$8,000 a month in costs
$4,000 a month coming in
That's $4,000 a month going out. 6 months of runway.
Cut $1,000 a month and it's 8.
Know the number before January, not in it.