📊 WELSPUN CORP - STOCK ANALYSIS REPORT
💡 Valuation Stance: Fairly Valued
📝 Executive Summary: Welspun Corp has transitioned from a cyclical pipe manufacturer to a diversified infrastructure major with a record order book of ₹42,100 crore and a high-margin B2C pivot via Sintex.
-------------------------------------
📈 KEY FINANCIAL METRICS
-------------------------------------
• ROCE / ROE: ROCE 29.4%, ROE 19.7% (FY25)
• Debt Level: Debt/Equity 0.24 (Net Cash Position of ₹2,336 Cr in Q1FY27)
• PE vs Sector: PE 30.6x vs Industry Avg 27.4x
• Revenue & Profit CAGR: Revenue CAGR 23%, Profit CAGR 28% (5-Yr)
-------------------------------------
✅ INVESTMENT CHECKLIST
-------------------------------------
• Growth Triggers: [YES] - A massive $1.8 billion US energy order and a 5-7 year demand runway in India's water infrastructure (DI pipes) provide multi-year revenue visibility.
• Management & Concalls: [YES] - Management has consistently met or exceeded guidance, successfully turned Sintex profitable within one year, and maintains a strict Net Debt/EBITDA target < 1.0x.
• Financial Valuation: [YES] - EBITDA margins expanded to 18.5% in Q1FY27; valuation is justified by a 25% revenue growth guidance for FY26 and a record-high order backlog.
• Technical Chart: [YES] - The stock is in a strong uptrend, trading well above its 50-EMA (₹2,066) and 200-EMA (₹1,383) with high delivery volumes following major order wins.
• Institutional Interest: [YES] - High institutional engagement with recent meets involving ADIA, UBS, and Jefferies, alongside a stable promoter holding of ~49.7%.
• Competitive Moat: [YES] - Global top 3 player in large-diameter pipes with the only US facility capable of 6-56 inch line pipe manufacturing, creating high entry barriers.
🚀 BULL CASE (CATALYSTS):
+ Record global order book of ₹42,100 crore ($4.4 billion) providing visibility through FY29.
+ Sintex turnaround contributing to higher-margin B2C revenue and brand premiumization.
+ Strong tailwinds from Jal Jeevan Mission and US LNG export expansion.
🔻 BEAR CASE (RISKS):
- Exposure to cyclicality in global Oil & Gas capex.
- Raw material price volatility affecting fixed-price DI pipe contracts.
#investing #stockmarket #IndianStocks
Priority Jewels - Stock Analysis Report
✅ INVESTMENT CHECKLIST:
• Business Model: Priority Jewels is a high-growth B2B jewelry manufacturer benefiting from the 'lightweight' jewelry trend and strong institutional partnerships. Unlike traditional retailers, the company focuses on the design-to-delivery pipeline for organized retail giants. Its core revenue comes from supplying to CaratLane, Kalyan Jewellers, Reliance Retail, and Senco Gold. Post-IPO debt reduction is a significant re-rating catalyst.
• Growth Triggers: [YES] - Expansion into lab-grown diamonds and increased wallet share with major retail chains like CaratLane and Reliance Retail.
• Management & Concalls: [YES] - Promoters Shailesh Sangani and Tushar Mehta bring over 30 years of industry experience with a clean execution track record.
• Financial Valuation: [PARTIAL] - Operating margins are thin at 6.3%, typical for B2B, but valuation is attractive compared to high-flying retail peers.
• Technical Chart: [YES] - Strong listing momentum with the stock trading above its IPO price of ₹200, showing healthy volume build-up post-listing.
• Institutional Interest: [YES] - IPO oversubscribed 99x, indicating robust interest from QIBs and HNIs.
• Competitive Moat: [PARTIAL] - Moat lies in a massive design library of 8,000+ SKUs and deep integration with India's largest organized jewelry retailers.
🚀 BULL CASE (CATALYSTS):
+ Utilization of ₹75 Cr IPO proceeds for debt reduction will significantly boost PAT margins.
+ Strategic supplier to CaratLane (Titan subsidiary) and Reliance Retail, capturing organized retail growth.
+ Focus on lightweight, daily-wear jewelry which is the fastest-growing segment in the Indian market.
🔻 BEAR CASE (RISKS):
- B2B model results in lower pricing power compared to B2C brands like Titan or Kalyan.
- High sensitivity to gold price volatility, though partially mitigated by gold metal loans.
#stockmarket #India #Jwelery #investing #business #ipo
With bond yields surging globally, high debt companies will face severe margin pressure, while cash-rich, low-leverage businesses will trade at a premium.
#bondyield#USD#inr
@_KiranRajput The foreign influence from Indian firms is reducing, we can also see it from that perspective where any external entity will not be able to push any harmful narrative through indian companies in any form.
@shiladitya4u I am indicating price movements after listing. Both businesses are different though.
Kanohar may also do well as per their order book size and one of the only five Indian companies with 400kV short-circuit certification and RDSO approval for railways.
FIIs pulled out over ₹44,000 crore from Indian stocks in September.
Although DIIs are providing support through steady SIP inflows, but this alone will not trigger a broader market rally. Expecting a range bound market until liquidity returns.
Priority Jewels - Stock Analysis Report
✅ INVESTMENT CHECKLIST:
• Business Model: Priority Jewels is a high-growth B2B jewelry manufacturer benefiting from the 'lightweight' jewelry trend and strong institutional partnerships. Unlike traditional retailers, the company focuses on the design-to-delivery pipeline for organized retail giants. Its core revenue comes from supplying to CaratLane, Kalyan Jewellers, Reliance Retail, and Senco Gold. Post-IPO debt reduction is a significant re-rating catalyst.
• Growth Triggers: [YES] - Expansion into lab-grown diamonds and increased wallet share with major retail chains like CaratLane and Reliance Retail.
• Management & Concalls: [YES] - Promoters Shailesh Sangani and Tushar Mehta bring over 30 years of industry experience with a clean execution track record.
• Financial Valuation: [PARTIAL] - Operating margins are thin at 6.3%, typical for B2B, but valuation is attractive compared to high-flying retail peers.
• Technical Chart: [YES] - Strong listing momentum with the stock trading above its IPO price of ₹200, showing healthy volume build-up post-listing.
• Institutional Interest: [YES] - IPO oversubscribed 99x, indicating robust interest from QIBs and HNIs.
• Competitive Moat: [PARTIAL] - Moat lies in a massive design library of 8,000+ SKUs and deep integration with India's largest organized jewelry retailers.
🚀 BULL CASE (CATALYSTS):
+ Utilization of ₹75 Cr IPO proceeds for debt reduction will significantly boost PAT margins.
+ Strategic supplier to CaratLane (Titan subsidiary) and Reliance Retail, capturing organized retail growth.
+ Focus on lightweight, daily-wear jewelry which is the fastest-growing segment in the Indian market.
🔻 BEAR CASE (RISKS):
- B2B model results in lower pricing power compared to B2C brands like Titan or Kalyan.
- High sensitivity to gold price volatility, though partially mitigated by gold metal loans.
#stockmarket #India #Jwelery #investing #business #ipo
True that, and moreover Indians could have been targeted across the world!
Such attacks are usually well planned after analysing probable outcome, the planners already know who the co-pilot and passengers would be. Now the concern is if one tactic has failed they may plan another tactics to achieve the similar outcome.
#captainsmitmachchhar #hero #flydubai #terroristattack
If the FlyDubai plane had crashed, foreign racists, Pak infowar armies, paid influencers & India’s pseudo-activist ecosystem would have ensured the Indian pilot was blamed. 🙏🏽
Some good quality stocks showing strength in weak market today -
Kanohar electricals
Macpower CNC
Skipper ltd
Kingfa science
Wheels india
Analysis of all these stocks already shared in detail recently.
#investing#stockmarket#nifty#smallcap
Some high growth business which would be huge benificiary from Green Energy Corridor phase - 3
1. Quality Power Electrical Equipments - QPOWER has growth triggers from HVDC/FACTS, data-center orders and renewable grid connectivity, with a group order book over ₹1,400 crore and a strong pipeline.
2. Skipper Ltd - India’s largest PGCIL tower supplier with a record ₹8,500 crore order book, capacity rising to 4.5 lakh tonnes and export expansion.
3. Hitachi Energy India Ltd - The largest beneficiary of physical line expansion. Demand for premium High-Temperature Low-Sag (HTLS) and AL59 conductors is surging as utilities upgrade transmission line capacity without expanding right-of-way (RoW). Management guidance consistently targets 15–20% volume growth in high-value conductors and premium cables, with export market expansion.
4. Transformers & Rectifiers India - TARIL has a record ₹6,630 crore order book, mega PGCIL inflows and capacity expansion; management guides healthy visibility.
5. Shilchar Technologies - Offers high-margin (~29%) export-heavy renewable transformers, debt-free with FY27 revenue guidance of ₹800 crore.
5. Genus Power - Leads smart-metering (core digital-grid data layer) with a ₹24,000–25,000 crore 8–9 year AMISP order book and FY27 revenue guidance of ₹6,000–6,500 crore. FII holding ~19%, DII rising; notable HNI buying.
6. Yash Highvoltage - A pure-play transformer bushing specialist used in every high-voltage transformer across grid evacuation, substations and BESS-linked projects. FY26 revenue grew 57% with 25.7% EBITDA margins and a ₹400 Cr+ order book; capacity is fully booked into FY27 with a greenfield plant and US subsidiary.
7. Techno Electric - Preferred EPC contractor for complex power sub-stations, smart grid infrastructure, and data center EPCs. Strong balance sheet with net-cash balance (~₹1,500+ Cr in liquid reserves), zero net debt, and ROCE maintained above 20%. Concall guidance targets an order book execution pipeline exceeding ₹10,000 Crore over 2–3 years.
These names sit in the GEC-III beneficiary chain with visible 1–3 year order-book and capex triggers. Valuations are elevated across the theme; treat as research ideas only and verify latest filings before any decision.
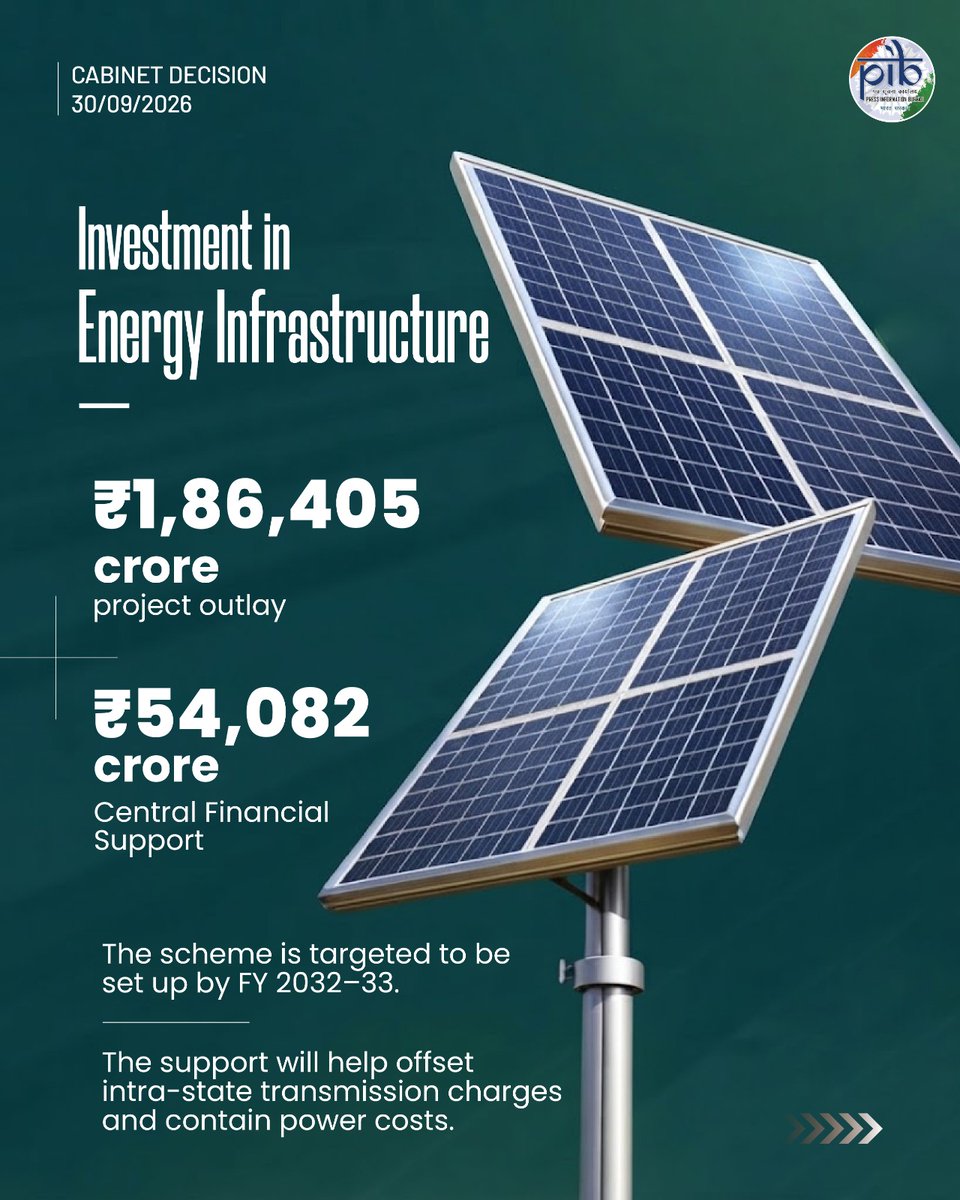
PM @narendramodi's Cabinet just approved a massive ₹1.86 Lakh Crore package for the GEC-lll.
If you want to play the energy transition right, stop chasing basic solar panel stocks and check these real proxy vectors which will get huge benifits across all divisions:
1. Grid Modernization & Evacuation
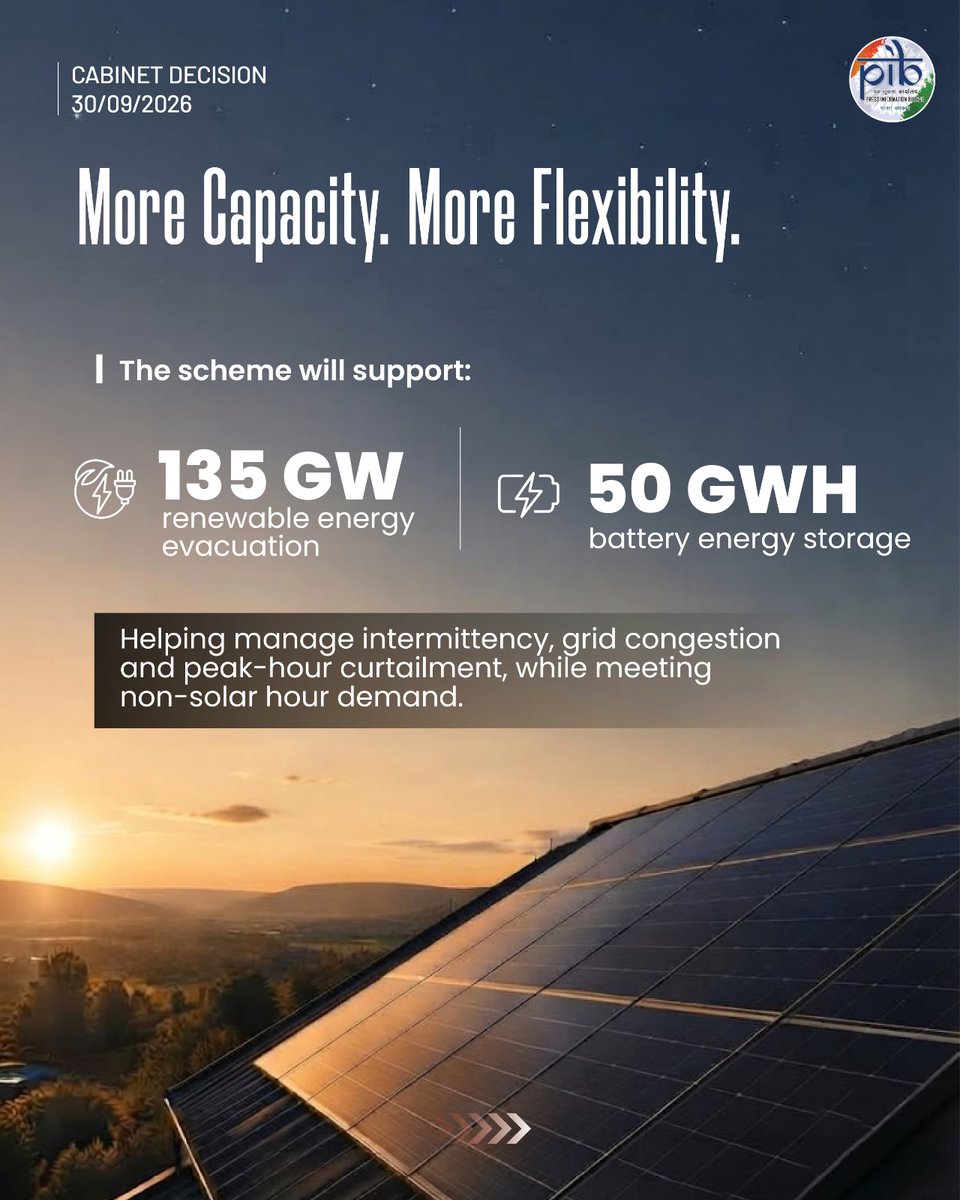
Relieving state network congestion to smoothly evacuate 135 GW of clean power.
👉 The Beneficiaries: High-voltage switchgears, gas-insulated substations (GIS), and heavy EPC infrastructure players.
2. Utility BESS Explosion
A whopping ₹50,000 Cr targeting 50 GWh of battery storage to eliminate renewable power intermittency.
👉 The Beneficiaries: Bi-directional inverters, battery pack assemblers, and specialized thermal/liquid cooling hardware.
3. Transmission Hardware
Massive volume expansions needed for the physical line buildouts.
👉 The Beneficiaries: Specialized ceramic/glass insulators, power transmission towers, and high-capacity conductors.
4. The Transformer Squeeze
Handling huge load fluctuations from 135 GW of volatile wind/solar requires high-tech step-up transformers.
👉 The Beneficiaries: Transformer manufacturers and smart-grid automation suppliers.
5. Grid Intelligence Software
You can't run a smart grid without high-margin automation software to balance the network.
👉 The Beneficiaries: Energy Management Systems (EMS), SCADA networks, and digital sub-station control software.
6. Advanced Materials & Commodities
The ultimate raw material bottleneck for the clean energy transition.
👉 The Beneficiaries: High-grade copper, advanced battery chemicals, and electrical steel (CRGO) used in transformers.
The Financial Reality Check:
Backed by a structural ₹54,082 Cr government subsidy, executing companies under the TBCB competitive bidding model get massive margin cushion and revenue visibility stretching all the way to FY 2032–33.
#StockMarketIndia #EnergyTransition #WealthCreation #Nifty #Investing
The rapid expansion of AI data centers, electric vehicles, and renewable energy is creating a major bottleneck - not in power generation, but in grid capacity and electricity delivery infrastructure. Modernizing aging power grids has now become a critical global priority.
This isn't just another green headline. It is a massive, multi-year capex wave designed to solve the biggest issue in Indian power: grid congestion. The government is injecting ₹54,082 Cr in central subsidies to fast-track this, giving executing companies massive revenue visibility all the way to FY 2032–33.
If you want to find the true alpha, look past the obvious power generators and track where this 1.86 Lakh Crore will actually be spent.
#EnergyTransition #Nifty #Investing #Capex #GEC #BESS
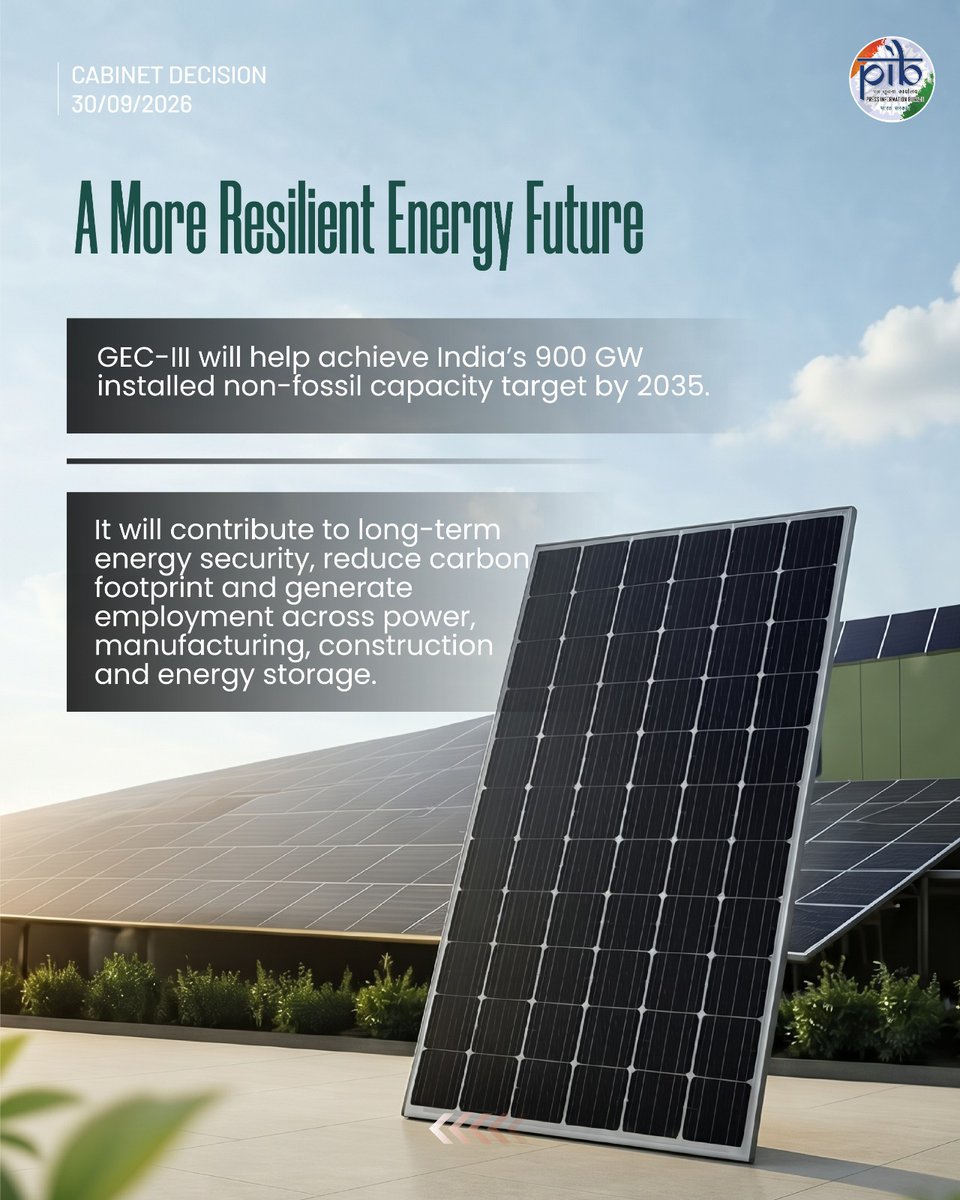
🌀Cabinet approves Green Energy Corridor Phase-III scheme for Development of Intra-State Transmission System with Battery Energy Storage Systems
▪️The Union Cabinet chaired by the Prime Minister @narendramodi has approved the Green Energy Corridor Phase-III (#GECIII) scheme
▪️This historic initiative will strengthen India’s Intra-State Transmission System (InSTS) to enable evacuation of up to 135 Gigawatt (GW) of renewable energy across States/ Union Territories
▪️The scheme also provides for deployment of 50 GWh of Battery Energy Storage Systems (BESS) at the Renewable Energy (RE) developer/generator end or any other location of importance for grid flexibility to address intermittency, congestion, peak-hour curtailment and meet non-solar hour demand
▪️The scheme will facilitate grid integration and power evacuation with in the States/UTs of India.
▪️The scheme is targeted to be set up by FY 2032-33 with total project outlay of Rs.1,86,405 crore
Don't miss the full details—read here: https://t.co/PKrIaBrpH4
@mnreindia #CabinetDecisions #GreenEnergyCorridor