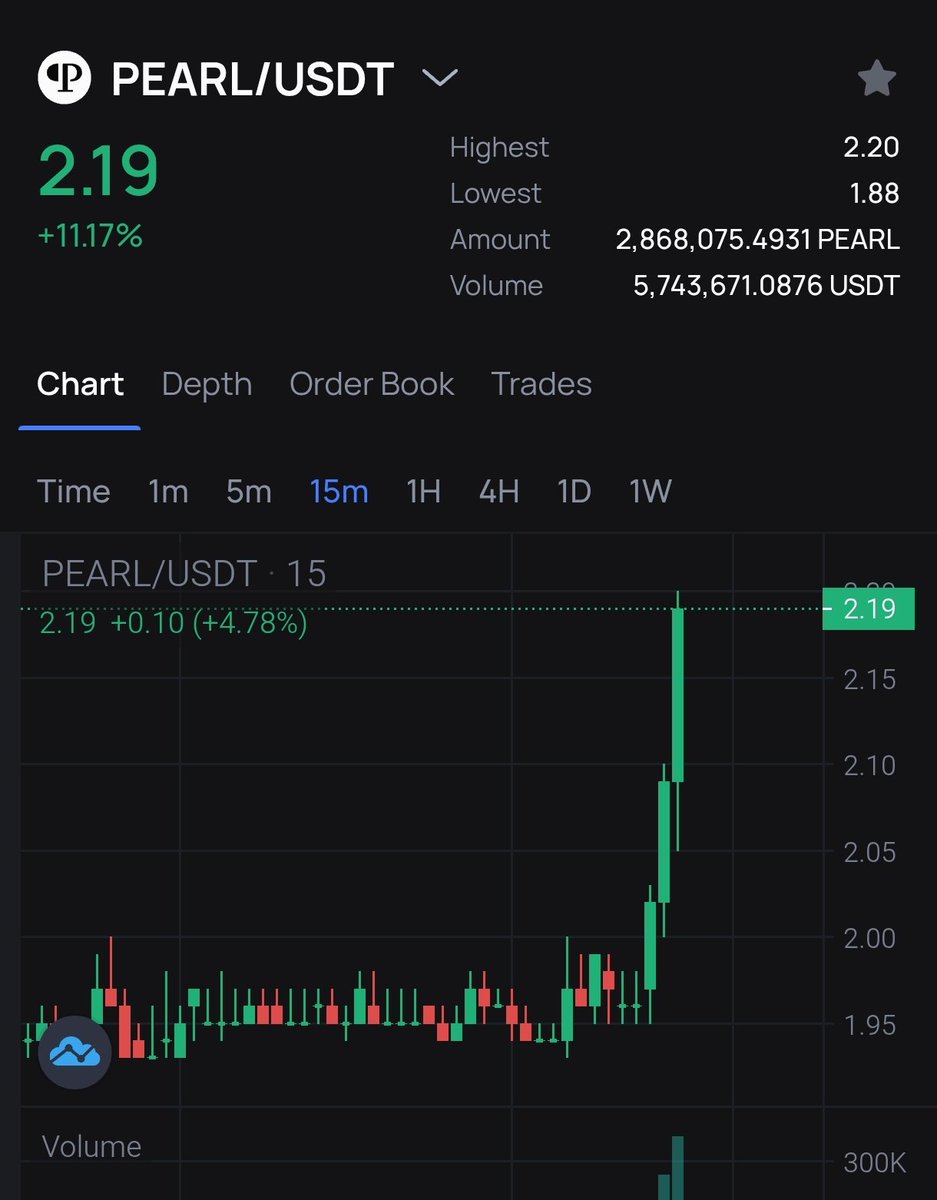
Thanks Jake for the discussion. There are risks to every investment, and Pearl's path to success isn't pre-ordained, but for me it is still the most asymmetric opportunity of the cycle.
Pushing back on some of the points he makes below:
1. Inflation - Jake says the Pearl market needs to find a full market cap of new buying just to hold price.
This is a poor assumption imo. It should be obvious that 100% of emissions are not sell pressure (0% of emissions is also not correct). The truth is somewhere in the middle. My belief is that the % of emissions set to hit as sell pressure is far below what the market is currently pricing in. There is historical precedence to this behavior (look at BTC miners in 2020/21 or Cypherpunk today, who specifically mined as an accumulation strategy)
2. Pearl has no moat.
Hard disagree here. The moat is the overhead. Just like Bitcoin, Pearl is open source. But they cannot recreate the network effects and they likely do not have the team capable of continuing to iterate on Pearl’s 2:1 kernel, which is the entire gateway to adoption (far more important than % of useful work imo).
3. More hashrate != more security
There is nuance here, my perspective is if Pearl has more hashrate (ie power draw and electrical footprint) than bitcoin, it absolutely becomes harder money and a more secure network. Bitcoin might have dedicated hardware securing the network, but this is exactly what is leading to hashrate loss and security budget issues. Even though Pearl is mined with fungible hardware (GPUs), its security budget can actually be far greater than Bitcoin’s because the system as a whole (combining inference + mining markets) creates strong economic incentives not to attack the network. Rafael Pass talks about this extensively in his “Economics of Useful Work” talk, which you can watch on Pearl Research’s YouTube channel if you are interested in learning more
4. ZEC needed to go through cycles long miner distribution before it became a good investment.
Folks think ZEC underperformance past cycles was due to its initial inflation / having to get past miner distributions, but I could not disagree more. There was no reason for alternative PoW SoVs to attract flows in prior cycles, but given modern risks to bitcoin (quantum, security budget, hashrate loss to ai), now there is. This is the “why now” of the investment. Zcash is already proving there is real demand for alternative SOVs that occupy a niche bitcoin can’t compete in, and the Overton window is opened. This is why Pearl can outperform now, despite it being earlier in its emissions curve.