Meraki, a well-established freight forwarder which has an incredibly strong network of contacts and experience in the logistics. Mail: [email protected]
At Meraki Carriers, we’ve spent the last six years securing every voyage and protecting every cargo with passion and precision.
Here’s to the journeys we’ve safeguarded, the partnerships we’ve built, and the trust you’ve placed in us.
#MerakiCarriers#6YearsOfMeraki
At Meraki Carriers, we’ve spent six years delivering excellence, navigating challenges, and ensuring seamless freight solutions for businesses worldwide. Our strength lies in our dedication, innovation, and unwavering commitment
#MerakiCarriers#FreightForwarding#6YearsOfMeraki
This World Forestry Day, we at Meraki reaffirm our dedication to sustainable logistics, ensuring a greener tomorrow while delivering excellence today. 🌍♻️
Let's transport responsibly, leaving a positive impact on both business and nature! 🌱✨
#MerakiCarriers#WorldForestryDay
Welcome back, Sunita Williams! Your journey beyond the skies continues to inspire us to push boundaries, stay determined, and aim for excellence—just like in logistics, where precision and reliability matter the most.
#MerakiCarriers#6YearsOfMeraki#SunitaWilliams
On this World Sparrow Day, we celebrate the power of connections, both in nature and in logistics. Just as sparrows contribute to the ecosystem, every small link in the supply chain ensures seamless global trade.
#WorldSparrowDay#SmallButMighty#MerakiCarriers#6YearsOfMeraki
New Zealand Customs delegation led by Ms. Christine Stevenson, Comptroller visited Air Cargo, Delhi Customs. Air cargo clearance process was discussed. Notes on best practices & importance of information exchange for interdicting suspect consignments were shared. @cbic_india
The 45th extended session for the UNESCO World Heritage Committee draws to a thoughtful close, leaving an indelible mark as another fascinating chapter in the grand narrative of global culture and heritage.
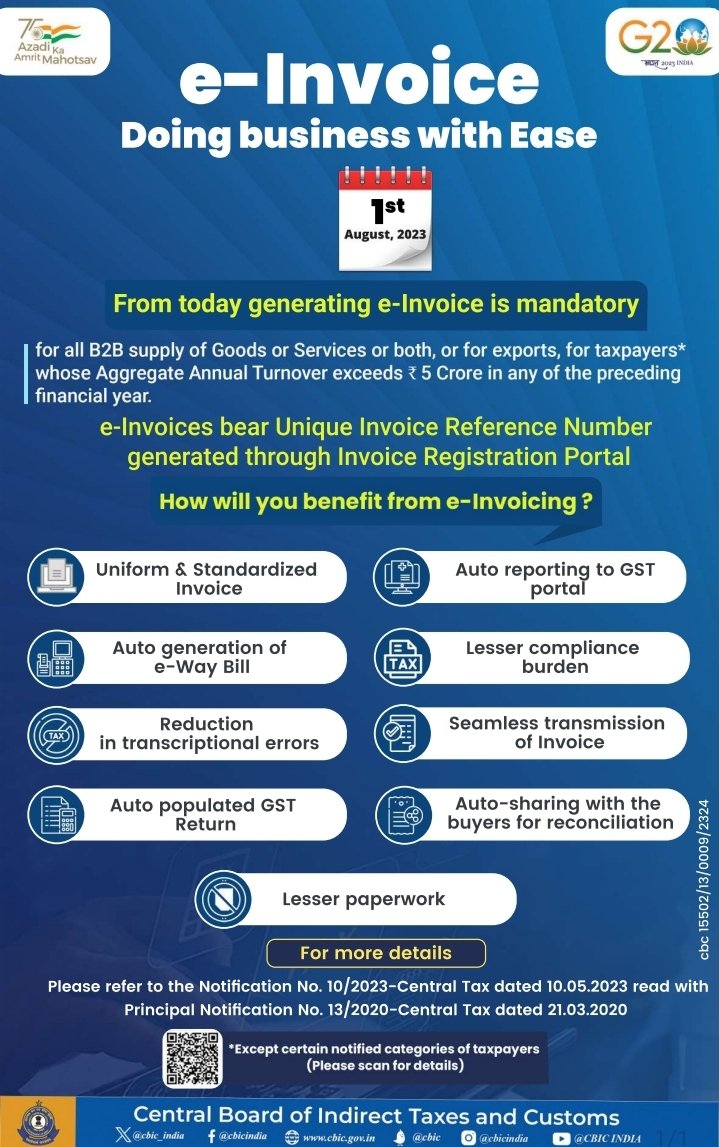
E-invoice mandatory for business!
From today, generating e-invoice is mandatory for taxpayers whose Aggregate annual turnover exceeds Rs. 5 crores in any of the preceding FY.
More information in the advt. below 👇
@cbic_india#easeofdoingbusiness#einvoice
📄Types of ITR Forms under Income Tax Act 1961
Confused about which ITR form to file?
Let's understand all types of ITR forms in detail.
*⃣ ITR-1 (Sahaj)
This form is for a resident individual whose total income is <= Rs. 50 Lakhs from the below sources:
- Income from salary/pension.
- Income gains from one house property (this excludes cases where loss is b/f from the previous FY)
- Income from other sources (gains from winning the lottery and horse race is excluded)
- Income from agriculture activities <= Rs.5,000.
*⃣ ITR 2
ITR 2 form is for individuals or HUF whose total income in a FY from the following sources > Rs.50 lakhs.
- Income from salary/pension.
- Income from one or more house property.
- Income from other sources(gains from winning lottery and horse race is included).
- If the individual have income from capital gains.
- If the individual has agriculture income >5,000.
- If the individual is Director in a company.
- If the individual has invested in unlisted equity shares in a FY.
- If the individual is a RNOR or NRI.
- If the individual holds a foreign asset or receives foreign income.
*⃣ ITR 3
This form is to be used by an individual or a HUF who are carrying on Business or Profession, This form is applicable to both Non-resident or Resident(ROR/RNOR).
ITR 3 can be used if you have following incomes:
Who is having income under the head PGBP and who is not eligible to file Form ITR-1 (Sahaj), ITR-2 or ITR-4 (Sugam).
- Income from salary/Pension.
- Income from House Property(one or more)
- Income of a person who is a partner in a firm.
- All Income from other sources.
- Income earned from capital gains or foreign assets/foreign income.
- If a person is the director of the company.
- Persons who had investments in unlisted equity shares at any time during the entire financial year.
- Total income can exceed 50 lakhs in this case.
- In short, individuals or HUFs who are not eligible to file ITR-1, ITR-2, and ITR-4, should file ITR-3.
*⃣ ITR-4 (Sugam)
ITR 4 is to be filed by the individuals/HUF/ Partnership firm whose total income includes as below:
- Business income u/s 44AD or 44AE.
- Income from profession u/s 44ADA.
- Salary/pension having income up to Rs 50 lakh.
- Income from One House Property having income up to Rs 50 lakh (excluding the brought forward loss or loss to be carried forward cases under this head).
- -Income from Other Sources having income up to Rs 50 lakh (Excluding winning from lottery and income from horse races).
*⃣ ITR 5
ITR 5 can be used by the following taxpayers:
- Firms
- Limited Liability Partnership (LLPs)
- Association of Persons (AOPs)
- Body of Individuals (BOIs)
- Artificial Juridical Person (AJP)
*⃣ ITR 6
ITR 6 applies to companies other than those claiming tax exemption under Section 11.
*⃣ ITR 7
ITR 7 caters to individuals and companies that are required to file tax returns under the following sections:
- Section 139(4A): Income of Charitable and Religious Trusts
- Section 139 (4B): Political Parties
- Section 139 (4C): Scientific research institutions
- Section 139 4(D): University, college or other institution
- Section 139 (4E): Business Trust.
- Section 139 (4F): Every investment fund mentioned in section 115UB.
Article has been contributed by Divyanshu Sharma