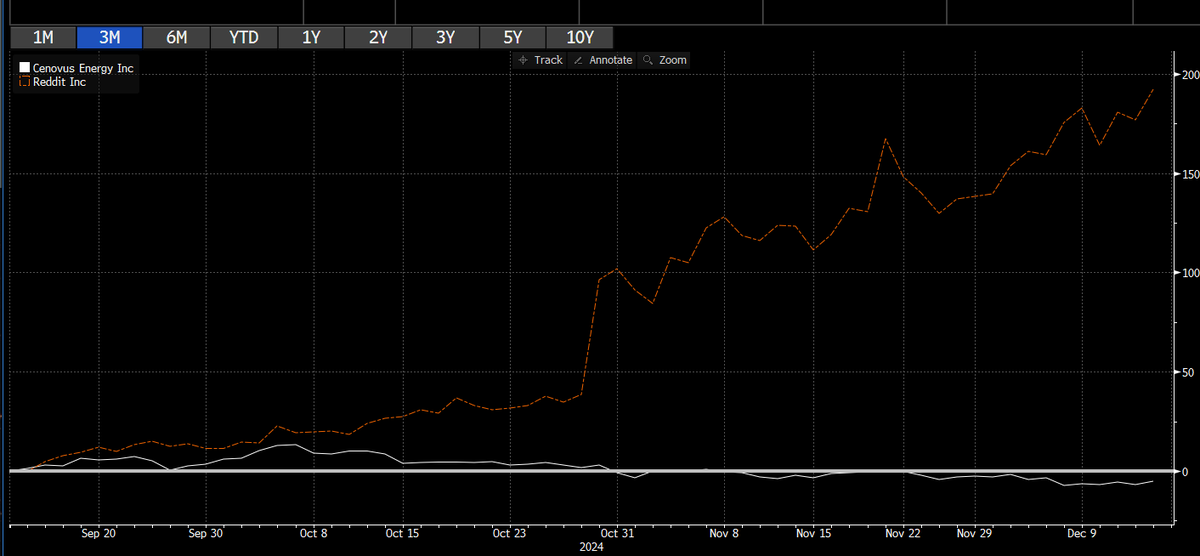
LKS has to sell pro rata as $CVE buys back stock to keep their ownership level constant.
“Following repurchases and cancellation of common shares by the Issuer since January 1, 2024, the ownership interest of Hutchison Whampoa Europe Investments S.a r.l. ('HWEI'), a wholly owned subsidiary of CK Hutchison Holdings Limited, has increased by 0.45 percent. HWEI proposes to dispose of common shares equal to 0.45 percent so that its ownership interest remains at 16.93 percent, which is the level before the repurchases and cancellation. HWEI does not sell shares under the Issuer's normal course issuer bid buy back programs for technical reasons of efficiency.”
Appreciate the response. I’m factoring in the $588M CVE released in w/c in Q3 in my FCF number. This release did build cash and facilitated the $1.1B in shareholder returns (with a coincident modest decrease in net debt). You could alternatively look at YTD FCF prior to w/c changes, as you prefer. CVE did $2.9B first 9 months in FCF, yielding 7.1% on their market cap (not annualized). CNQ free cash generation first 9 months was 6.1% of market cap. (I didn’t deduct SBC from either FCF calculation, which I really should.) So that’s a comparable yield, with CVE a bit higher. The question is what does this look like in 25, 26 and 27? Production growth and FCF inflection for CVE, as growth capex tapers, looks more attractive to me… well, at least on a spreadsheet. I am trying to pick the better stock over my investment horizon, not the better business. I know many investors that prefer focusing on asset and mgmt quality instead and do quite well, so I’m not knocking that philosophy. If you believe CVE’s upstream growth guides are questionable, I would love to understand your thinking.
@_sem_yyc I noticed. Maybe he’s quoting the CAD revenue for 2022 ($66.9B) and the USD revenue for 2023 ($38.7B). At this point we’ve put in more thought into dissecting his numbers than he did while making them up. Impossibly to fight demagoguery with facts and analysis.
@_sem_yyc I’m sure Jagmeet knows the difference between revenue and profit. He’s counting on his constituents not bothering to verify the accuracy of his claims. When there are no consequences for telling lies, why bother with the truth.
The actual interview (in French) is linked below. The relevant dialog starts at 59:40. You can translate the transcript using Google or GPT (my choice). Come to your own conclusion. The whole interview is worth listening to (turn on subtitles, 2x speed) to get a handle on Burkina.
“Q: He asks if the Poura gold mine is on your agenda. Thank you.
A: We must say that all gold mines are currently on our agenda because, for gold, when we know how to exploit it ourselves, and that’s what I was saying, I don’t understand why we allow the gold to be exploited and then let multinational companies come and exploit our gold. So it’s in this sense that I’m saying that there are permits that we are in the process of withdrawing and that we are going to do it ourselves. So the gold mine is part of that and will, pardon me, be part of these mines that we plan to exploit. The APEC, if you see, the APEC has started with its first mine in the southwest zone, and we will continue as much as they are going to ramp up by granting permits for them to exploit it themselves. And the other company, um, Samib, which is currently operational through SOPAMIB, for which we have paid for both Bongou and others. Let’s look at others. Mines will therefore be part of SOPAMIB’s assets, allowing it to exploit these industrial sectors as well.”
https://t.co/SDFwRm1Rr6
@YellowLabLife I appreciate your insights on X. I am genuinely at a loss to understand why the deal does not have USW's support (versus the inferior bid from CLF, which did).
@tradeoilstocks Yet they reported very similar free funds flow (C$1.35 vs C$1.2 billion). CVE free cash yield materially higher. Further, CVE FCF should rise, ceteris paribus, through 2026. And CVE doesn’t have that long term tailings issue.
But, yeah, I share your sentiment.
@tradeoilstocks Feedback from large broker was this was probably a "sell the news" event given how well telegraphed the debt target has been. Catalyst focused HFs seldom hold a stock for divvy and buyback driven re-rating. Of course, the stock didn't rally into the news, so beats me...
@DavidFi_ Incorrect. Traore’s comments are from a July 11 speech and appear to be directed toward nations obstructing military sales to Burkina. Details and video in tweet below.
IBRAHIM TRAORÉ: NO MORE MINING FOR THE WEST
Imperialists beware! Burkina Faso President Ibrahim Traoré made clear during his 11 July address to the nation that foreign powers will no longer be allowed to dictate which weapons the military receives, block the reception of specific military equipment and continue to exploit the landlocked African country’s natural resources.
Traoré said Burkina Faso will revoke mining licences for states that continue to do so and that it is ready to mine its own resources.
Before the revolutionary coup in Africa’s arid Sahel region south of the Sahara Desert, Burkina Faso’s neighbours in Mali had accused France of using threats and manipulation to block equipment sales between Mali and Russia, a scandal reported in local Burkinabé news sources, such as https://t.co/Djqr8XjF7y. Word quickly spread that France had similarly blocked Burkina Faso’s access to Russian weapons, which, before Traoré’s government, Burkinabé ministers vigorously denied.
Now, Traoré has confirmed such speculations. And Burkina Faso has made one thing clear: If you are going to use its mines, it has to be in exchange for something of value, such as access to weapons needed to end terrorism. Counter-terrorism efforts kicked off after weapons flooded the Sahara Desert following the 2011 NATO-backed overthrow of Libyan leader Muammar Gaddafi, destabilising the most prosperous African state at the time.
Video credit: Faso7 TV (@faso7tv on YT, @faso7_bf on X and IG, @faso7bf on TikTok)
@YellowLabLife If Trump wins and, thereafter, if he succeeds in bringing the war in Ukraine to an end, a lot of steel will be needed for Ukraine's Marshall Plan. One company is particularly well poised to supply this steel.
@YellowLabLife Agree. Also, buyside apathy for gold miners, and the general level of depression among gold miner managment, is as great as I’ve ever seen.