Here's 10 stocks that I've added to my watchlist in the last 2 months👇🧵
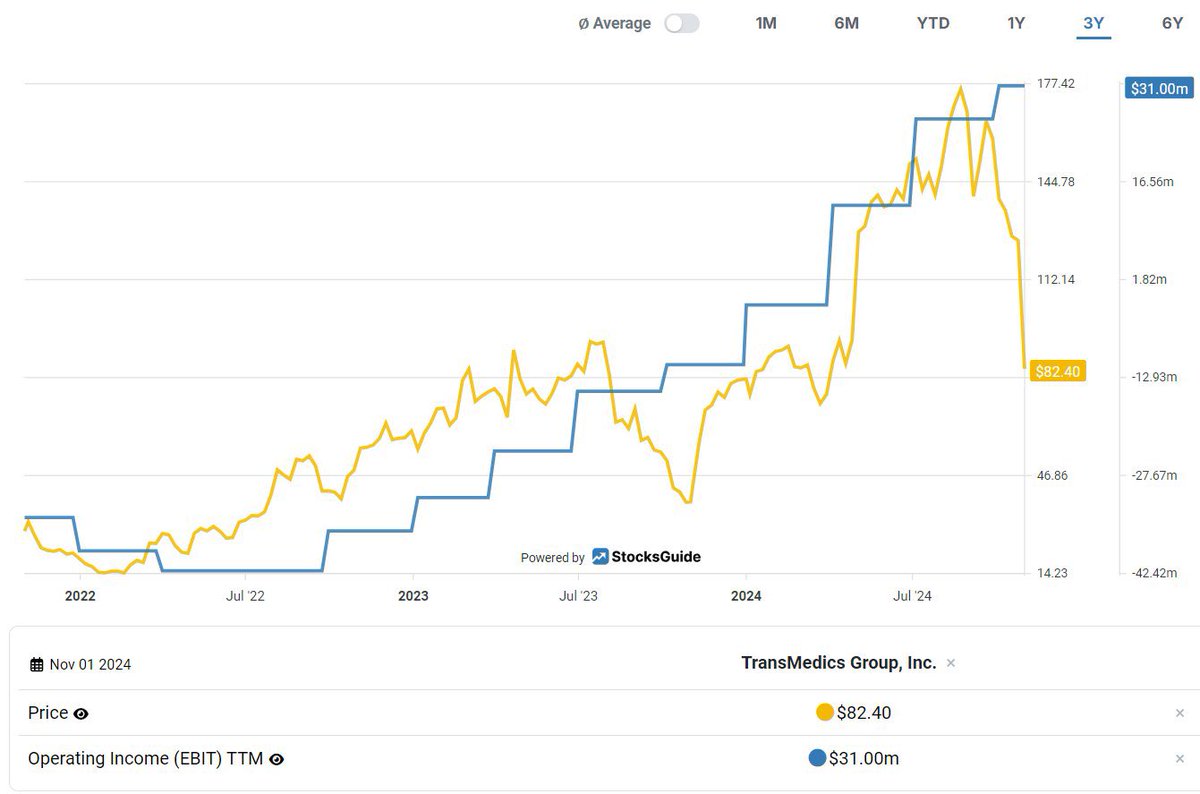
1. TransMedics | $TMDX
I initiated a position in $TMDX post earnings drop and I'll be DCA'ing with any further moves down.
Instead of worrying about what Warren Buffett is doing, focus on finding undervalued companies.
I have my eyes on these (some I have started to DCA into) 👇
- $ASML
- $ASPN
- $SBUX
- $TMDX
- $CELH
- $OXY
- $LULU
10. Occidental Petroleum | $OXY
Forget the fact that $OXY is currently trading below Buffett's average price, oil is a very cyclical market.
Currently, $OXY has an EV/Sales of 2.61x compared to a 6 year average of 3.17x. I think DCA'ing in the $40s and low $50s is smart.
Nobody is talking about $BABA now👇
2014 Revenue of $12.3 Billion and a share price of $90
2024 Revenue is now $126 Billion and has a share price of $97
A 10x increase in share price has led to a 7.7% increase in the share price over 10 years.
China macro issues won’t last forever.
Do the numbers ( $AMZN + $HIMS edition)
$AMZN AWS will have 25% market share in a $2.3T market by 2032.
This could lead to revenue above $550 billion.
4x EV/Sales = $2.2T
Current $AMZN market cap is $1.9T. The AWS segment alone should be valued more than the ENTIRE $AMZN business today.
----------
$HIMS members will hit 10 million * $92 subscription fee = $11B in revenue.
$11B * 4.1x EV/Sales = $45.1B EV or 10.2x from today.
Give me some more obvious buys👇
These are the 4 best chip companies to invest in today👇
$INTC - Recently announced investment of $28 billion into 2 new chip factories in Ohio, $INTC is planning a comeback. Remember, they only trade at 2.3x EV/Sales.
$TSM - Sole provider for $NVDA, $QCOM, and $AAPL and directly benefitting from the surging demand. They also announced that their new Arizona facility has yields 4% higher than Taiwan facilities.
$NVDA - Demand is sky high and will remain sky high for the most valuable company in the world. Just this week $TSLA said they want to reach 50k H100 capacity.
$ASML - They hold a monopoly in lithography machines, yet trade at just 9.9x EV/Sales after the recent drop.
$TMDX at $150: "This company is incredible"
$TMDX at $80: "Why would you buy this company"
$SOFI at $6: "It's just a bank"
$SOFI at $11: "It's the best fintech in the world"
$PYPL at $60: "It's a dying company"
$PYPL at $80: "This company is coming back"
$HIMS at $23: "This is disrupting a huge industry"
$HIMS at $17: "I wouldn't touch this. Too many risks"
$ASML at $1,000: "It has a huge monopoly"
$ASML at $670: "Demand is slowing and I don't like it"
$CELH at $90: "They're taking over the entire market"
$CELH at $30: "Why would you buy this trash?"
Do I need to keep going? Or have you learnt a lesson yet?
$PYPL Q3 Review
The quarter was very solid to be honest. The drop to $80 could be a nice opportunity if you're looking to buy some.
Here's my thoughts👇
1. Q4 Guidance Raise was the most exciting part of this quarter for me. Management are careful with their guidance but they know they've got a ton of exciting ventures ready to start ramping up.
- Venmo (30% growth in monthly active debit cards✅)
- Fastlane (over 1,000 merchants now using Fastlane. This will ramp up a lot more into 2025).
- Advertising platform
- Braintree now meaningfully contributing to transaction margin as a much more profitable business now. Less focused on top line revenue.
2. Bought back $5.3 billion (around 7%)
3. Yes they missed revenue estimate but all the exciting new products and ventures have yet to really contribute to any data yet. Patience here.
4. The take rate is an obvious concern that I think a lot of investors are focused on. A big reason for this is the unbranded Braintree has massively improving margins and therefore is becoming a much more influential part of the tx rate.
5. Total Payment Volume up 9% and transactions per active account up 9% is all very promising.
6. Free cash flow growth of 31% YoY, buying back a boat load of shares, and a valuation similar to 2017 is all you need to know about $PYPL still being undervalued.
Full $SOFI and $PYPL reviews coming to X this evening.
Much more detailed reviews of $SOFI and $PYPL on my newsletter this Friday.
Follow me here @MMMTwealth and sign up here for the newsletter 👇
https://t.co/j9mjki9PyI
$TMDX
"Importantly, we did not see any degradation of our market share or center penetration on all three orders."
"There has not been or we have not seen any fundamental or competitive dynamics playing any role in the slight sequential decline in case volume for OCS in Q3"
They also didn't miss guidance. They missed analysts estimates.
Thank you Mr. Market.