@MithunSarkari I kind of wonder… if only i had followed you earlier. You simply doing charity for free, giving lead so one can analyze and build conviction. 👍🏻
@MithunSarkari I think deepak fertiliser must be added here. They will be strong candidate for re rating once they complete their capex, which is guided for this or next month. Kindly look if possible.
" Aarti Pharmalabs: From Cola to Cancer Drugs to GLP-1"
1/12
Most people think Aarti Pharmalabs (NSE: AARTIPHARM) is a 2019 company.
It's actually a 40-year-old chemical empire that just got a new birth certificate.
And it just posted its best quarter ever.
Here's the breakdown: 🧵
2/12
How It Started
1984: Started as Aarti Organics by technocrat Chandrakant Gogri
2001: First API + Xanthine unit at Dombivli
2005: Tarapur Unit-4 for US/EU markets
2016: Caffeine at Unit-5
2022-23: Demerged from Aarti Industries and listed separately
A 40-yr operation with a 2019 paper.
3/12
Today:
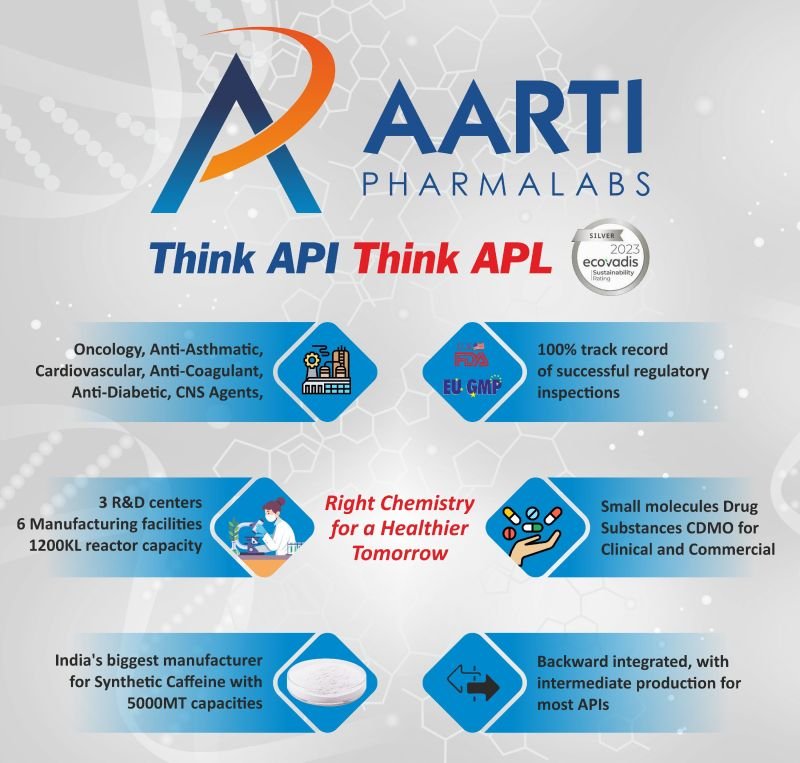
• 7 manufacturing units (Maharashtra & Gujarat) • 3 USFDA approved • 3 R&D centres • 2400+ employees • Part of Aarti Group (> Rs 145 bn turnover)
Mcap ~ Rs 7,800 Cr | Small-cap Pharma
4/12
What Makes It Special?
The world's only integrated non-Chinese caffeine maker who also does cancer APIs.
• India's largest caffeine maker, World's 3rd largest • Supplies 15-20% of world caffeine, ∼80% of India demand • 60 US DMFs, 44 CEPs, 500+ clients, 50+ countries
5/12
Business Breakdown
A) Xanthine Derivatives = 57% of Q1 FY27 (The Cash Cow)
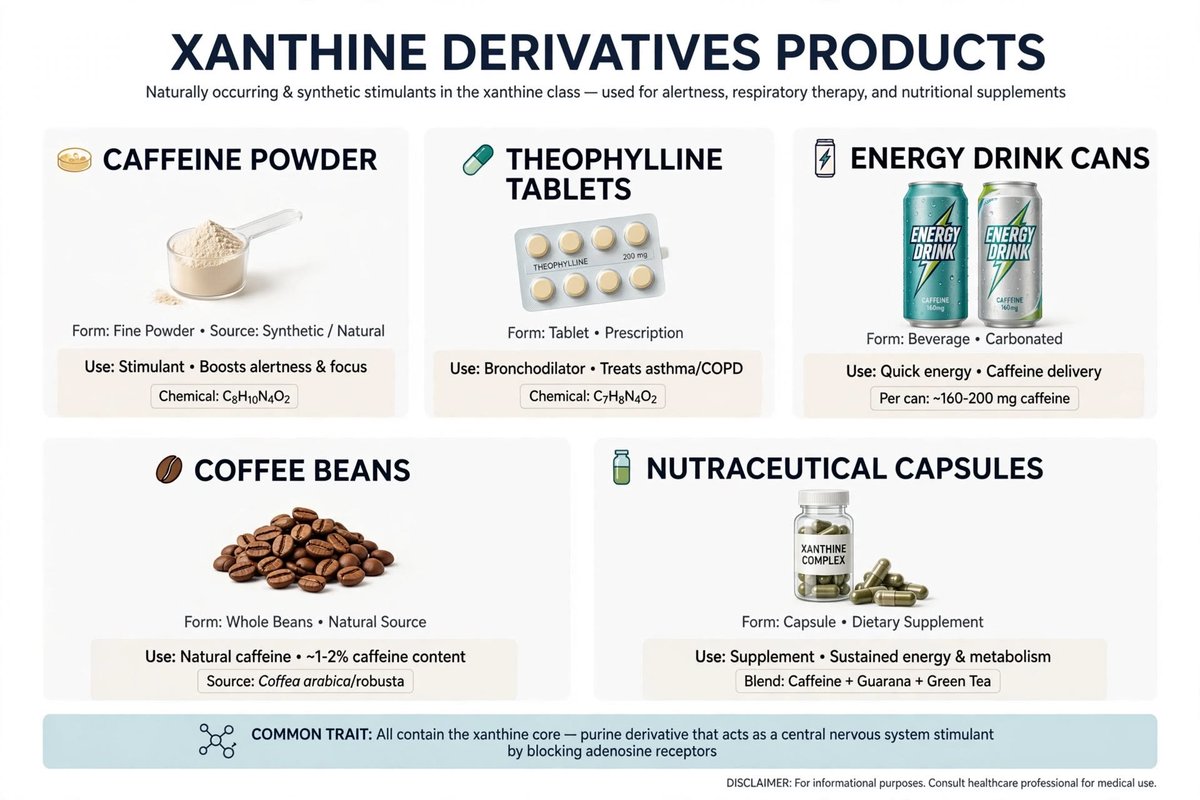
Caffeine, Theophylline, Aminophylline
Use: Cola + Energy drinks (74%), Pharma (26%)
79% exported
Capacity: 5,000 -> 9,600 TPA after new 3,600 TPA block at Tarapur Unit-5 in June 2026
6/12
B) API & Intermediates = 30% (The Moat)
61 APIs commercialized, 11 under development
HPAPI, steroids, oncology cytotoxic
C) CDMO/CMO = 7% but fastest growing (The Future)
Rs 32 Cr in FY22 -> Rs 276 Cr in FY26
22 customers, 57 projects
Focus: Phase II/III to commercial
7/12
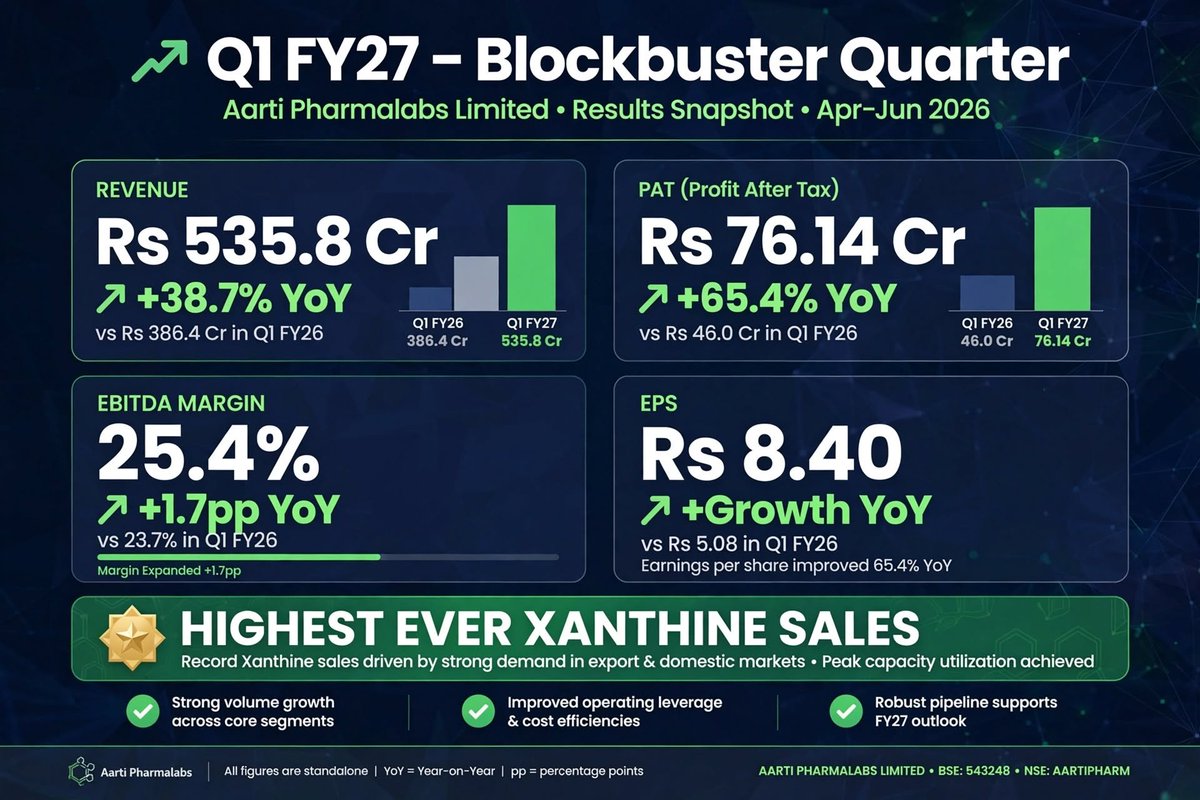
Q1 FY27 - The Blockbuster
This triggered the 33% rally in 2 days:
Revenue: Rs 535.8 Cr, +38.7% YoY
PAT: Rs 76.14 Cr, +65.4% YoY, +24.6% QoQ
PBT: Rs 101.06 Cr, +66.2% YoY
EBITDA Margin: 25.4% vs 23.7% YoY
EPS: Rs 8.40 vs Rs 5.08
Highest ever Xanthine sales.
8/12
Inside Q1:
• Highest ever Xanthine sales despite global slowdown • JV Ganesh Polychem turned profitable: +Rs 7.41 Cr vs -Rs 1.8 Cr loss YoY • Profit grew even after 6-week shutdown of Unit-4 steroid block for debottlenecking (+33% capacity)
Operationally very strong.
9/12
Triggers
1) Rs 149 Cr capex approved Aug 7 - 405 KL intermediate block at Atali for CDMO
2) Xanthine Super Cycle - beverage recovery + China+1
3) Leadership change Oct 1, 2026 - Rashesh Gogri to MD
4) GLP-1 entry - building peptide platform for Semaglutide/Tirzepatide
10/12
Moat & Clean Chit
Moat:
• Non-Chinese caffeine monopoly • Backward integrated (own KSMs/intermediates) • HPAPI/oncology blocks = high entry barrier
USFDA: March 2026 inspection at Tarapur Unit-IV cleared with only 1 procedural observation in Form 483.
11/12
Risks to track:
• 57% revenue from caffeine = commodity + cola demand risk • CDMO promise is still only 7% - execution is key • Working capital heavy (exports) • Restated base: YoY growth looks higher due to forex-derivative restatement last year
12/12
Aarti Pharmalabs is a classic demerger story - old business, new listing, new growth engine (CDMO + Peptides).
Whether caffeine super-cycle sustains + CDMO scales from 7% to 20%+ will decide if it stays small-cap.
Not financial advice. DYOR.
#AARTIPHARM #Pharma #SmallCap
@SniPayne Exactly.. but HFCL’s 60-65 percent of q1 revenue came from OFC solutions, interestingly margins in ofc is lower than other business segments of hfcl apart from epc and turnkey. HFCL’s business strength probably getting overshadowed by AI narrative and stl tech’s comparison
@chetanmahur25@MithunSarkari@grok There is catch.. more than 40 percent of their aum is unsecured.. their d2c aum needs to be scaled.. and biggest problem is their poor ROE due to lower borrowings against its equity base and credit cost is also high.. high credit cost also makes the illusion of lower NPA
@MithunSarkari Well the story is there.. but what do you think about its valuations? … they had distressed base which has been already capitalised by the market well.. absolutely no margin of safety at this valuations..
“I succeeded in the market because I love the market.”
— Rakesh Jhunjhunwala
This 👇 was his prediction before the 2008 market crash.
“There could be a significant fall in consumption in America, combined with hard lending in China. That could lead to a slowdown in the global economy and hit India too.”