Among the 30 major housing markets with the highest share of “underwater” borrowers, the table below shows you the “underwater” breakdown by vintage.
In the down markets, it's primarily the 2022, 2023, 2024, 2025 and 2026 vintages being impacted.
@JeffEllery@ResiClub_HQ Naples is there, Fort Myers is there (in Cape Coral metro).
Venice, FL; Bradenton, FL; and Sarasota, FL are all in the North Port-Sarasota-Bradenton, FL metro, which is up +0.1% YoY in this series (however, still down -16.6% from '22 peak).
Among the 300 largest metro/micro area housing markets, the 76 markets with declining year-over-year home prices:
-> The list has expanded from 54 markets to 76 markets over the past two months
Chart via @ResiClub_HQ
@wxgator The home price corrections in Cape Coral MSA (and FL in general) since mid-2022 have been almost exactly on par with what cyclical factors in early 2022 were suggesting for the markets.
See this report:
https://t.co/DCjREISRD0
Florida’s particularly intense overheating during the Pandemic Housing Boom was the key reason for its post-boom downside pricing vulnerability (in particular in SWFL). While U.S. home prices rose +41% between March 2020 and June 2022, Florida home prices surged +51% over the same period—leaving some parts of the state significantly overvalued. Only, it takes a large enough shift in the supply-demand equilibrium for that vulnerability to manifest into falling prices. Of course, after the boom ended, 5 factors came together to create a supply-demand equilibrium shift large enough to reveal some of that downside risk and push certain pockets of Florida into post-Pandemic Housing Boom corrections.
1. The Pandemic Housing Boom’s migration surge to Florida fizzled out. Indeed, Florida saw net domestic migration of +23K in 2025, compared to +314K in 2022. Without that larger influx of deep-pocketed buyers from up North, Florida home prices have had to rely more on local incomes.
2. Surfside condo fallout. Following the Surfside condo collapse in June 2021, which killed 98 people, Florida passed new structural safety rules, requiring more inspections and additional funds for repairs to be set aside by the end of 2024. That has led to Florida HOAs issuing sky-high special assessments and monthly HOA fee increases to cover these costs. Following Surfside, Fannie Mae and Freddie Mac also tightened condo underwriting: stricter reserve requirements, mandatory. This has had a greater impact on older coastal Florida condo buildings.
3. Hurricane Ian spurred a greater SWFL softening. Markets like Cape Coral and Punta Gorda, which were hard-hit by Hurricane Ian in September 2022, saw thousands of damaged homes, and the subsequent need for renovations. According to the National Oceanic and Atmospheric Administration, Hurricane Ian caused an estimated $112.9 billion worth of total damage, making Ian the third-costliest U.S. hurricane on record. That event helped create additional softening in SWFL.
4. Supply elasticity. Unlike many housing markets in the Northeast and Midwest, Florida has a higher level of homebuilding, build-to-rent, multifamily construction. As that new supply entered the market in the post-Pandemic Housing Boom affordability-strained environment, builders used bigger affordability adjustments—such as mortgage rate buydowns and rental incentives—where needed to move it. That helped cool the Florida resale market further by drawing buyers who might have otherwise purchased existing homes toward new construction. As a result, this put additional upward pressure on Florida’s resale inventory after the Pandemic Housing Boom ended.
5. Home insurance shocks. In the three years following the boom, the median annual U.S. home insurance premium has jumped around 30%, but Florida homeowners have been hit even harder. The surge in Florida home insurance rates is partly driven by rising replacement costs—home prices and construction costs soared during the boom—and partly by increased hurricane risks and insurance payouts. Florida's sharp rise in insurance costs, combined with one of the biggest home price increases during the Pandemic Housing Boom, has led to one of the biggest housing affordability deteriorations.
--> Many Florida markets needed some mean reversion—and over the past four years, with much of it occurring in 2024 and 2025, that mean reversion has taken place (see the black line below representing the nationally aggregated housing market).
@evaheeeh bizarre comment considering that at the climax of the Pandemic Housing Boom I covered pockets of FL—and in particular SWFL—as having a greater risk of post-boom correction considering cyclical factors (in particular very high levels of "overvaluation")
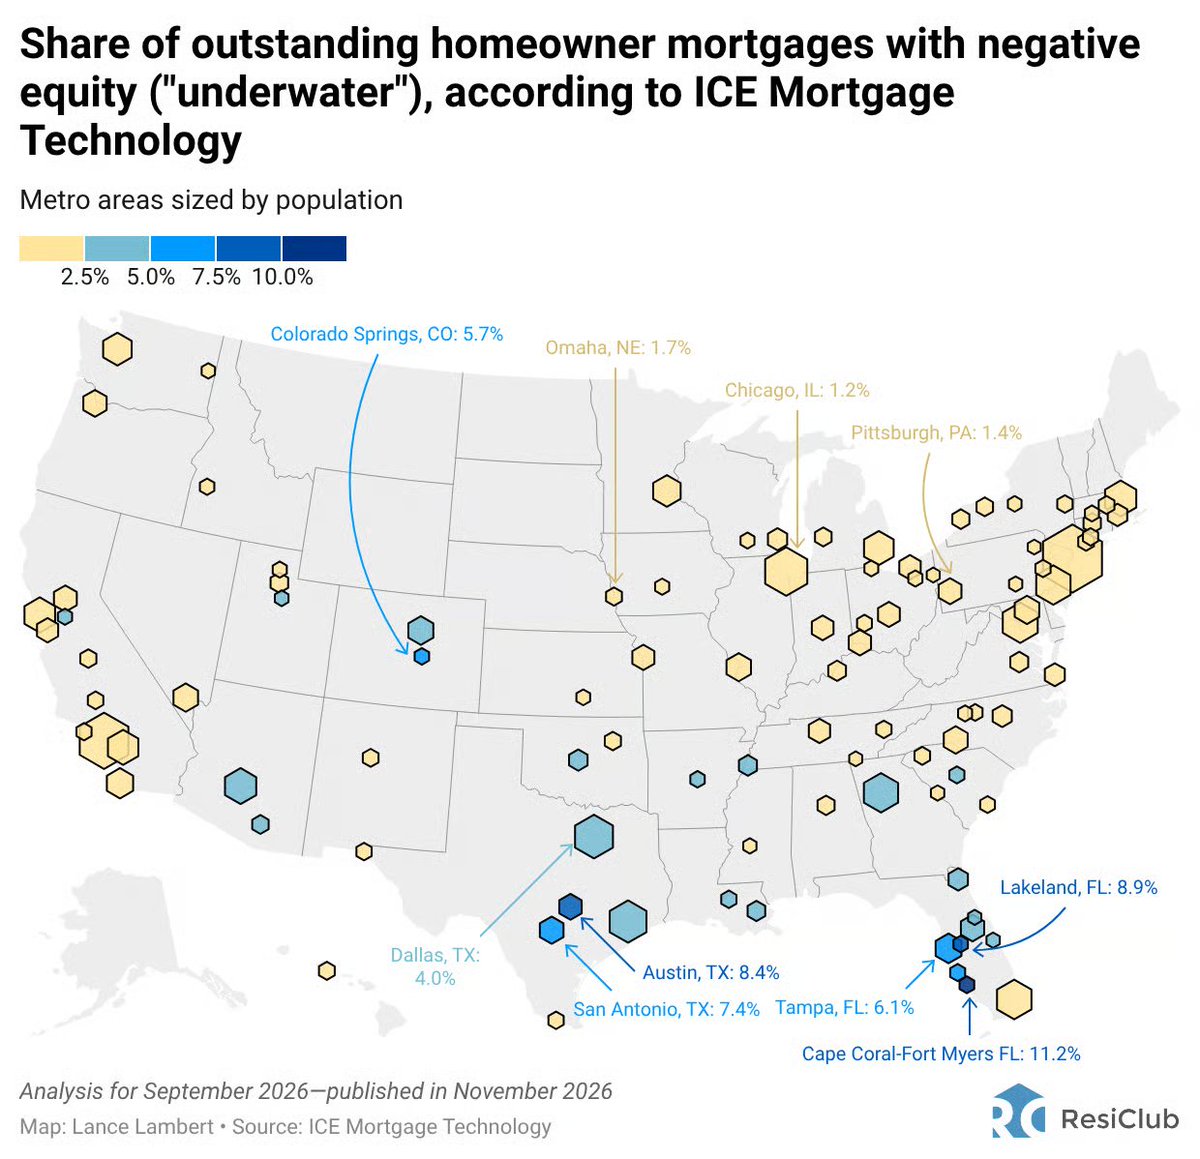
Among the 100 major metro areas for which ICE Mortgage Technology provided data to ResiClub, these 15 metros have the highest share of homeowner mortgages currently underwater:
1. Cape Coral, FL —> 11.2%
2. Lakeland, FL —> 8.9%
3. Austin, TX—> 8.4%
4. San Antonio, TX —> 7.4%
5. Tampa, FL —> 6.1%
6. Colorado Springs, CO —> 5.7%
7. North Port, FL —> 5.4%
8. Baton Rouge, LA —> 4.8%
9. Jacksonville, FL —> 4.8%
10. Dallas, TX —> 4.0%
11. Orlando, FL —> 3.7%
12. Palm Bay, FL —> 3.7%
13. Phoenix, AZ —> 3.7%
14. Tucson, AZ —> 3.5%
15. New Orleans, LA —> 3.5%
Read the full @ResiClub_HQ article here: https://t.co/5asMv8iNIl
@AnthonyClose Methodology explained in the article below.
Negative equity here means a homeowner owes more on their mortgage than the current market value of the home.
https://t.co/gIOrOM7cxV
Among the 30 major housing markets with the highest share of “underwater” borrowers, the table below shows you the “underwater” breakdown by vintage.
In the down markets, it's primarily the 2022, 2023, 2024, 2025 and 2026 vintages being impacted.
Among the 30 major housing markets with the highest share of “underwater” borrowers, the table below shows you the “underwater” breakdown by vintage.
In the down markets, it's primarily the 2022, 2023, 2024, 2025 and 2026 vintages being impacted.
Homebuilder intelligence for navigating a regional down housing market cycle and exiting strong, as told by Prophetic’s CEO
At ResiDay 2026, @ResiClub_HQ interviewed Oliver Alexander, founder and CEO of Prophetic, for a fireside chat on navigating a regional housing down cycle.
Prophetic tracks thousands of new homes for sale on top builder websites and checks their prices twice a week. Its data shows the weakness is very regional. Builders in Houston, Tampa, Charlotte and Nashville are leaning hardest on incentives, while Phoenix and Boise are holding up better. The Northeast builder pricing is moving in line with national averages.
Oliver also covered “value drain” (small margin losses at each step that compound across a builder’s business), and how one Orlando builder found 354 off-market lots where it expected about 150.
You can watch Oliver's full chat here: https://t.co/WvmNzZdthF
We should point out that the nationally aggregated housing market is softer than the counts above suggest, given that year-over-year home price declines are currently skewed slightly toward larger metro areas. Among just the 50 largest housing markets, 21 (42%) are currently posting negative year-over-year price growth when looking at this particular index.
Also note that most of the places posting “nominal gains” are seeing gains below income growth and consumer price growth, which the latter economists call “real” (inflation-adjusted) home price declines.