In July 2025 we bought thirty-two NVIDIA H200s and put them on the on-demand market.
We are publishing fourteen months of actuals from that fleet.
Very little operating data on GPU fleets is public. This is ours. https://t.co/ecgHaVT1Dd
But contracted revenue = rate x utilization and as more deals get underwritten against contracted revenue, somebody will eventually want the second number.
Few lenders today are even requesting historical utilization. Financings still get priced against counterparty credit, contract terms, and residual value assumptions.
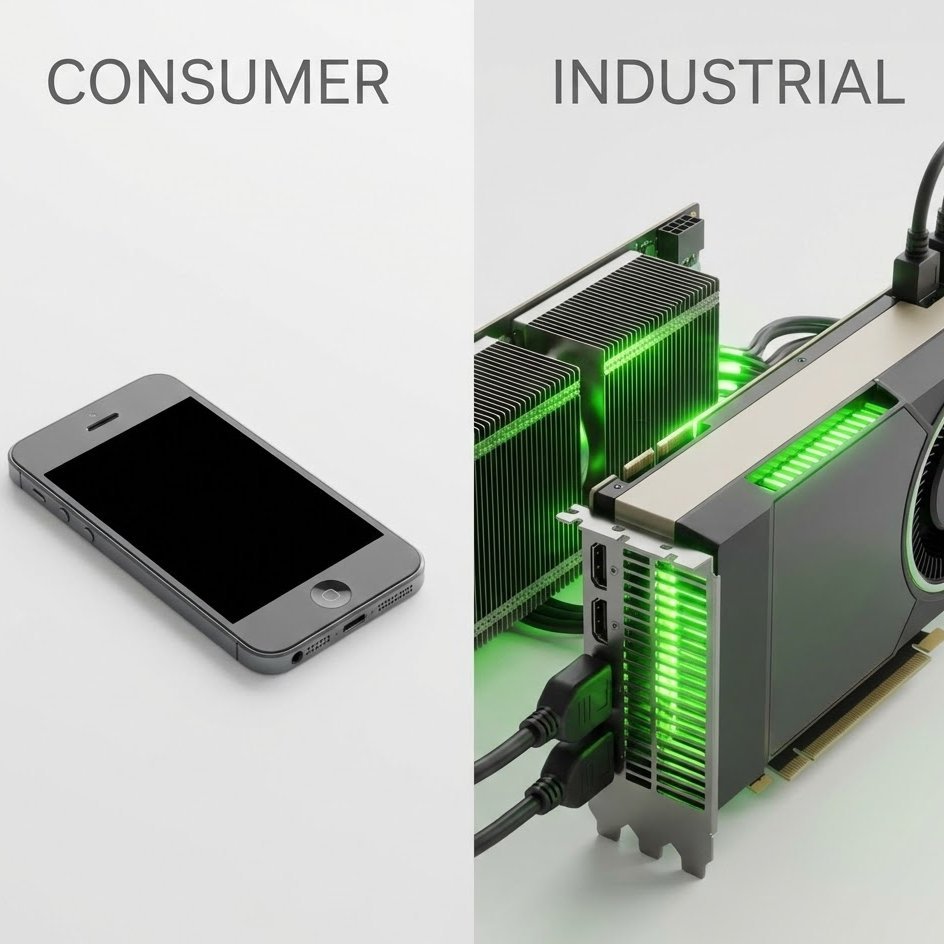
The biggest mistake I see investors make is viewing GPUs like iPhones.
With consumer tech, value is driven by "newness". Many want the latest model because it has a better camera or a thinner bezel. When the new one comes out, the old one feels obsolete.
But in the industrial world, value is driven by ROI.
A 3-year-old tractor that can still plow a field is not "obsolete". A 5-year-old Boeing 737 that can still fly passengers is not "obsolete". These are revenue-generating assets.
GPUs follow this same logic, not consumer logic. An older A100 might not train GPT-5, but it can run inference for a healthcare bot perfectly fine. As long as the chip can do work that someone is willing to pay for, it retains value.
We need to stop looking at this market through the lens of a consumer and start looking at it through the lens of an equipment lessor.
Everyone talks about hedging against inflation.
That usually means buying hard asset gold or real estate. Hard assets. I view high-performance GPUs in a similar bucket.
It is a scarce, physical resource that generates cash flow. Unlike cash, which loses purchasing power, productive hardware tends to hold its value relative to the demand in the market.
It’s interesting to see more Family Offices starting to allocate towards GPU investments.
If you want to learn about investing in GPUs, read this article we recently published:
https://t.co/gXhyVF9YtW
There's a big difference between buying a stock and investing in GPUs.
When you buy a stock, you are betting on market sentiment and a multiplier of future earnings. When you invest in a GPU, you are funding the engine itself.
To be clear, it doesn't function as a fixed bond. Yields vary from month to month depending on the strategy.
Some clusters are on stable long-term contracts while others are on-demand for higher potential upside.
But that is exactly why I like it. You know exactly where the return comes from. It’s transparent and grounded in the real economy.
To learn more, read this whitepaper on GPUs as an investment, co-published with The Family Office Association:
https://t.co/qGgHmZVscq
My stock portfolio jumps up and down every day based on news headlines and Fed whispers.
It can be exhausting. That’s why I prefer the mechanics of investing in GPUs. It’s not risk-free, but it is rational.
When we finance a GPU cluster, the returns are driven primarily by utilization.
1) The machine turns on.
2) It processes a workload (whether that's a steady contract or on-demand spot usage).
3) The revenue flows from that work.
Our early GPU pilot deals are yielding well. To learn more, read this whitepaper on GPUs as an investment, co-published with The Family Office Association:
https://t.co/SjrJJO7JDi
Right now, AI companies are paying a hefty premium for speed of GPU deployments.
Neoclouds have customers waiting at the door, but traditional banks are too slow to finance the hardware.
That delay creates an attractive opportunity for private capital.
By stepping in to fund that gap, we can command a higher yield for solving a liquidity problem. We provide financing exactly when the neocloud operator needs it.
This play wouldn't exist in more capital efficient market. We are helping family offices and individual investors capture this value. Learn the basics about GPU infrastructure investing here:
https://t.co/WwgzkNQ6qY
We wrote the manual on investing in GPUs.
I’m excited to share a whitepaper I co-authored with @WarWren_ and @TFOA_SFO
Over the last year, I’ve spoken with hundreds of investors who understand that AI is huge, but don’t know how to touch it without taking massive venture risk.
This paper is the answer.
We dig deep into the mechanics that actually matter like utilization rates, depreciation myths and the investment opportunities companies are working on.
If you are a family office or allocator looking to better understand the AI economy, this is for you.
Read it here: https://t.co/A29vV0FCIz
The best yields often live in the gaps where banks can't move fast enough.
Right now, a neocloud with signed enterprise contracts can still struggle to deploy, even with a loan from a traditional lender.
That disconnect allows private capital to step in and capture a premium spread that simply shouldn't exist in a capital efficient market.
We are helping family offices and credit funds access this arbitrage.
AI stocks move on sentiment. Infrastructure yield moves on utilization.
When you invest in GPUs with @Compute_Labs, you aren't betting on NVIDIA’s quarterly earnings call or interest rate cuts. You are betting on the secular demand for compute capacity.
Whether the S&P is up or down, the demand for inference continues to grow. That makes structured compute one of the few genuinely non-correlated yield sources available today.
If your portfolio needs exposure to AI growth without the volatility of public equities, feel free to reach out!
Everyone is chasing AI exposure through public equities. But the real arbitrage is in the yield.
The quieter, higher-yielding opportunity is securing the economic rights to the GPUs themselves.
But yield only exists if the infra is running.
We underwrite neoclouds to ensure they have the demand side sorted, whether that’s through signed contracts or proven on-demand utilization.
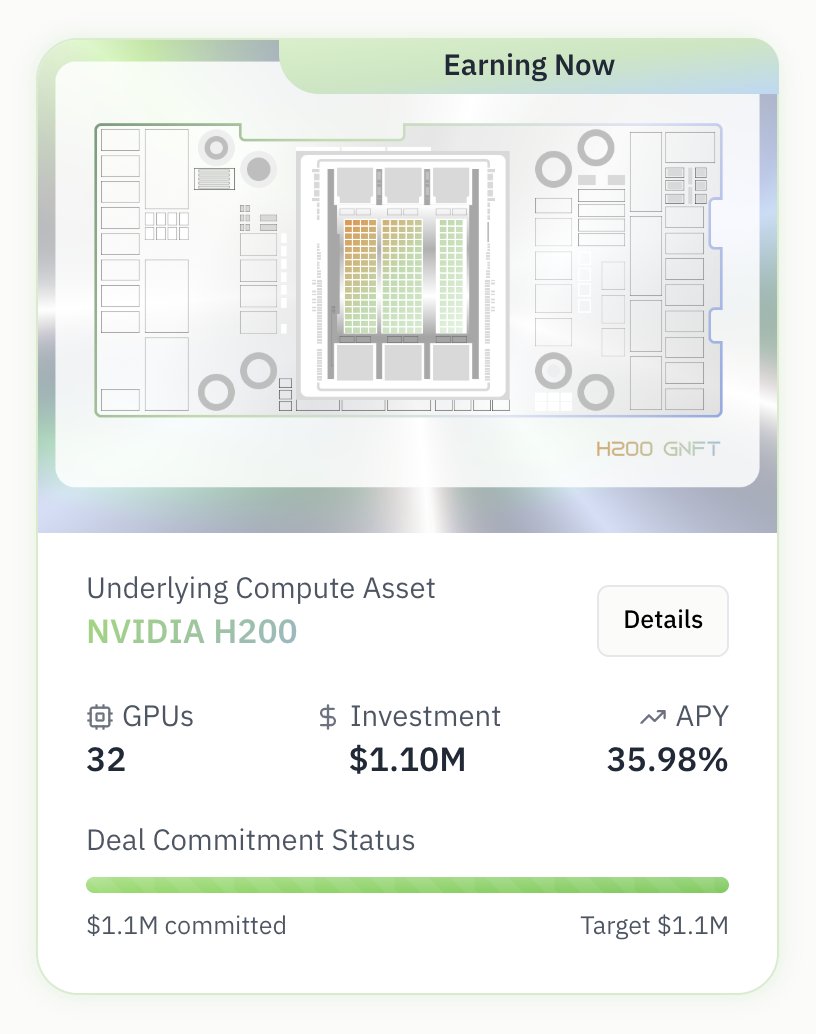
The 36% APY we’re seeing on our H200 is a premium paid for liquidity in a constrained system.
Right now, neoclouds have end demand contracts but lack the credit history for traditional bank debt. That friction creates a window for private capital to step in and capture the spread that traditional lenders are leaving on the table.
@Compute_Labs is helping allocators early to this industry capture this yield before the institutional floodgates fully open.
To a traditional lender, GPUs are often only viewed as hardware with a depreciation schedule. In the Compute Labs model, they function as income-generating infrastructure assets.
Hardware book value provides crucial downside protection for the principal. However, the primary value driver is a neocloud's ability to monetize uptime.
Structuring financing around asset yield rather than just resale price unlocks liquidity for neoclouds and provides asset-backed returns for investors.
This is how capital markets for compute are built.
We talk to neoclouds every day who have strong demand but can’t scale due to limited financing tools.
On the other hand, investors tell us they’re interested but don’t yet have a framework to underwrite neoclouds and GPU returns.
There is a fundamental mismatch. Providers can put hardware to work immediately. And only a small set of allocators understand the economics deeply enough to fund them.
Closing that gap is what unlocks scale.
If you’re an allocator looking for exposure to a high-demand real asset, I can walk you through how we structure these deals in a way that’s familiar and underwritable.
More and more capital allocators are reaching out to ask about compute and the same pattern keeps popping up: they want exposure to AI, but are still learning how GPU revenue actually works.
That’s where most of the opportunity is right now. Neoclouds have workloads ready to run and investors want attractive yields.
The gap is education.
Once investors understand utilization, demand type, and operator track record, GPUs begin to look like a yield asset they already know how to evaluate.
If you’re exploring the space and want a walkthrough, I’m always happy to chat.
There’s a reason a live H200 deal on our platform is earning 36–40% APY: the industry has a GPU demand and financing supply mismatch.
Neocloud operators can monetize GPUs quickly after they arrive, but most capital sources aren’t set up to fund these deployments. That gap creates unusually strong return profiles because few groups can underwrite the economics.
These yields won’t last forever. As capital markets get more educated on AI infrastructure, returns will normalize. But right now, early allocators are being rewarded for stepping into an asset class before it matures.
If you want to understand how these deals are structured, happy to chat.