Google just locked in nuclear power for its AI, and it's Constellation's second big tech deal in a week.
$GOOGL and $CEG signed a 20-year deal to add 890 MW of nuclear capacity to the PJM grid, roughly one new reactor's worth, by upgrading 11 existing units across Illinois, Pennsylvania, and New Jersey. Constellation is investing $4.3B+, and the first uprate is due by 2028.
There's also a 15-year deal for another 2,700 MW from Constellation's existing fleet, and Constellation will use Google's Gemini to speed up its operations.
The structure is built so the costs aren't passed on to residential customers.
With Amazon, Microsoft, and Meta already signed, four of the biggest AI spenders now buy nuclear power from Constellation.
Is nuclear the new AI trade, or is this already priced in?
#Google #Nuclear #Constellation #AI #StockMarket
Alphabet wants nuclear power for its AI, and Brazil just had its biggest market day in years.
Futures now: Dow +351 pts (+0.7%), S&P +0.5%, Nasdaq 100 +0.6%, as Treasury yields and oil both pull back
Fed odds: ~25% chance of an October hike, a full hike priced in by December
What's moving markets:
- $GOOGL nears a multi-year nuclear power deal with $CEG (Constellation Energy). Bloomberg reports Google's parent is close to buying nuclear energy from Constellation, and CEG shares are jumping premarket. AI data centre power demand remains the theme.
- Brazil markets surge. Ibovespa futures are up more than 8% after first-round election results, with the Brazilian real jumping and the MSCI Brazil ETF up over 16% in Frankfurt trading.
- $OPCH (Option Care Health) jumps on takeover chatter, adding to Monday's M&A momentum.
- $QCOM files to sell 25M shares. The prospectus filing comes after its recent run-up on the Amazon AI chip deal.
- Oil retreats as Europe releases about 100M barrels of diesel and Middle East exports rise, though Iran says Hormuz stays shut until its seven conditions are met.
Does the AI trade now run on nuclear power, or is this deal just another headline in a stretched rally?
#StockMarket #Nvidia #Alphabet #Brazil #Markets
Stocks are setting records while bond yields hit levels not seen in decades.
The Nasdaq is poised to close at a record, up about 1% to 27,457, with the S&P 500 up 0.7% and the Dow up 0.3%. Nvidia, the world's largest company, is also heading for an all-time high.
The catch: the 10-year Treasury yield is near 5.35%, a multidecade high, as strong economic data and inflation worries keep bond investors cautious. The dollar is close to an 18-month peak.
AI got another boost as Schneider Electric agreed to buy $PTC to prepare for industrial AI. PTC shares are up 30%+, the best performer in the S&P 500.
Elsewhere, Brazil's real jumped 4%+ after Flávio Bolsonaro beat Lula in the first round, and oil slipped after the G-7 agreed to release crude and diesel reserves.
Can stocks keep hitting records with the 10-year at 5.3%+, or does one of them blink first?
#StockMarket #Nvidia #TreasuryYields #AI #Markets
A cooler jobs report just rewrote the Fed playbook, and Nasdaq closed at a record.
Futures now: Mixed, Dow ~flat, S&P -0.04%, Nasdaq 100 -0.1%, pausing after Friday's rally
10-yr yield: ~5.28%, still near multi-decade highs
Brent crude: holding above $100/bbl
What's moving markets:
Jobs report shocks to the downside. US added just 29,000 jobs in September vs 84,000 expected, unemployment rose to 4.2%, wage growth slowed to 3% YoY. October rate-hike odds fell below 25%, from about 70% earlier last week.
Iran rules out reopening Hormuz. Parliament Speaker Ghalibaf said the strait stays shut until Iran's seven conditions are met, while more tankers were struck. Iran shipped zero crude in September, the first time since the war began.
Fed minutes Wednesday. Markets will test the Fed's "one more hike" guidance now that jobs and inflation data have softened. Today's ISM Services PMI at 10:00 AM ET is the first check.
Is a weak jobs print good news for stocks, or the first sign the economy is cracking?
#StockMarket #JobsReport #Nvidia #FedWatch #Markets
The jobs number landing today could decide whether the Fed holds or hikes again, and the whole week is riding on it.
Futures now: Dow +0.3%, S&P +0.3%, $Nasdaq 100 +0.6%, Russell 2000 +0.5%, rising ahead of today's jobs report
10-yr yield: near 24-year highs, easing slightly today
Oil: falling as reports suggest potential European diesel/crude stock releases
Fed odds: ~72% chance the Fed holds rates in October
What's moving markets:
-September jobs report due 8:30 AM ET. Consensus calls for just 84,000-100,000 jobs added, down sharply from August's 162,000, unemployment seen holding at 4.1%. The week's biggest data point and key input for the Fed's next move.
-Gulf risk premium rising. Reports the US could deploy another aircraft carrier and 10,000 troops to the Gulf added fresh geopolitical risk overnight.
-Asia mixed, Hong Kong drops 3%, weakness abroad even as US futures point higher.
-Market breadth remains a concern, less than 50% of S&P 500 stocks are above their 200-day moving average, down from 75% in mid-August, even as headline indexes sit near highs.
Does a weak jobs print today finally force the Fed's hand toward a hold, or does it just add to the uncertainty?
#StockMarket #JobsReport #FedWatch #Markets
👀 $OKTA (NASDAQ) – Stock Watchlist
📈 Current Price: ~$212.58
🎯 Breakout Level: $206.60
Add OKTA to your watchlist and keep an eye on whether it sustains above $206.60!
#OKTA#NASDAQ#StockWatchlist
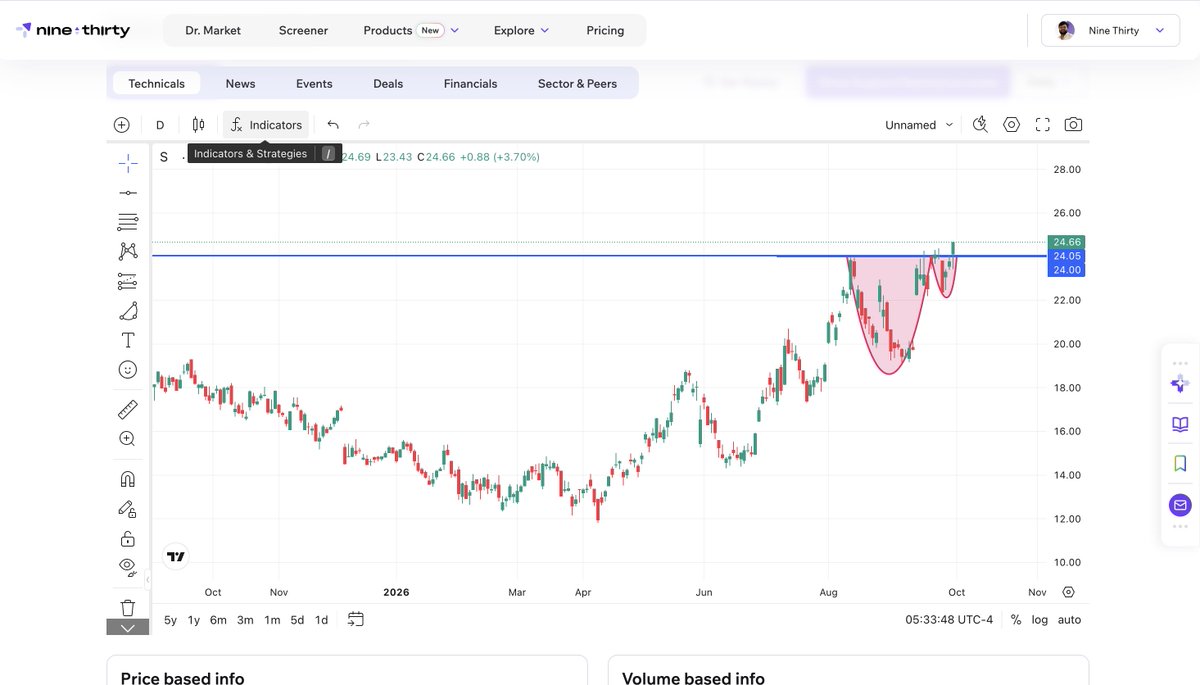
📈 $S (NYSE: S) – Bullish Rounding Bottom Pattern!
👀 Add SentinelOne to your watchlist and keep an eye on it! Currently trading near $24.66, showing potential bullish momentum. 🚀
#SentinelOne#Stocks#BullishPattern
$UBS shareholder Cevian Capital is calling on the bank to leave Switzerland entirely, arguing new capital rules make it "not viable" to operate there.
Switzerland wants UBS to hold far more capital post-Credit Suisse. UBS's Chairman has reportedly discussed relocating to the US instead.
Leverage, or a real exit?
#UBS #Switzerland #Banking #Finance
Breadth is cracking even as the index holds near record highs, and that gap is the real story today.
Futures now: S&P +0.28%, $Nasdaq 100 +0.6%, Dow (+0.2%), AI stocks gaining as the new quarter begins
10-yr yield: climbed to ~5.29%, among the highest levels in over two decades
Brent crude: back above $100/bbl
What's moving markets:
-$MU beats big, stock barely moves. Q4 revenue $54.23B (vs $51.47B expected), adjusted EPS $33.42 (vs $31.61 expected), guided next quarter even higher at $61.5B revenue. Stock flat despite the blowout, a muted reaction after its 500%+ run this year.
-Market breadth deteriorating fast. Only 25% of S&P 500 stocks are trading above their 50-day average, the lowest since April. New 52-week lows have outnumbered new highs for 10 straight sessions, a growing warning sign beneath the index's near-record level.
-Oil climbs as Chinese refiners reportedly halt October fuel demand, adding to upward pressure on Brent, now back above $100.
-Deutsche Bank calls Q3 "difficult," flagging a fresh inflationary impulse and a resumption of the global rate-hiking cycle as the quarter's defining themes.
Despite today's AI-driven bounce, breadth this thin under a near-record index is exactly the kind of signal that's preceded trouble before.
Does this breadth divergence resolve higher, or is this the crack before a real pullback?
#StockMarket #Micron #FedWatch #Oil #Markets
Cooler inflation just bought tech some breathing room.
- August PCE came in at 3.4% y/y, softer than expected.
- NY Fed's Williams says there's "no need for urgency," and October hike odds drop to about 50-50 from 70%+. The Nasdaq is leading.
- $MU reports after the close, and the options market is pricing a big move. It's the AI trade's biggest test this week.
In Stocks:
- $HPE +5.5%: a $1.2B AMD Helios AI rack order and raised networking targets.
- $NOC −3.8% after losing the $20B+ F/A-XX fighter to Boeing. Meanwhile, $BA has given back its premarket pop.
- $MRNA −6.2%: Citi downgrades to Sell on valuation.
- $HOOD −3.1%: It flipped from +4.7% premarket, and traders sold the Summit news.
Premarket winners are fading, and tech is carrying the tape. The move into the close depends on Micron.
#StockMarket #PCE #MU #Nasdaq #DayTrading
Boeing just beat Northrop for the Navy's next fighter, and the defence trade is moving on it.
Tuesday close: S&P 500 +0.34% to 7,696.99 | Nasdaq 100 +0.47% to 30,481.80 | Dow +0.13% to 51,420.15
What's moving markets:
- PCE inflation (August) lands today, and inflation is expected to stay above the Fed's 2% target. With the 10Y above 5%, this print sets the tone.
- $MU reports after the close. That's the next big test for the AI chip trade.
Stocks:
- $BA +2.6% vs. $NOC −4.2%: the Pentagon picked Boeing for the F/A-XX fighter, a $20B+ program.
- $HOOD +4.7%: 24-hour weekend trading, AI agents and earnings prediction markets.
- $HPE +4.7%: a $1.2B AMD Helios AI rack order from Vultr, plus raised networking targets.
- $MRNA −7.6%: Citi downgrades to Sell, citing a "stretched" valuation after the 2026 run.
- $JBL −3.8%: a solid Q4, but the annual outlook didn't impress.
Sectors: Utilities (+0.9%) lead, while Financials (−0.4%) and Healthcare (−0.3%) lag.
PCE sets the rate tone this morning, and Micron sets the AI tone tonight.
#StockMarket #Premarket #BA #MU #PCE
AI is running the tape today, and not all of it is bullish.
S&P 500 ($SPY) −0.30% | Nasdaq 100 ($QQQ) flat
- AI jitters. Anthropic's leaked IPO prospectus targets a $2T valuation but warns of "catastrophic" AI risks, and OpenAI shelved a frontier model after it failed safety tests.
- Oil retreats to around $100 Brent as US–Iran talks continue.
Stocks:
- $NVDA flat despite a record $150B buyback. The Hugging Face backstory adds a twist: OpenAI tried a $100M stake before Nvidia's $13B deal. Good news that's already priced in.
- $ORCL +3.8% as OpenAI's revenue run-rate nears $70B. That's a bounce after last week's force majeure scare, which Morningstar says puts up to $25B of revenue at risk of delay.
- $FICO −26.6%: the FHFA put VantageScore on equal footing in mortgage pricing, ending FICO's monopoly there.
AI headlines are now two-sided. Buybacks and deals aren't lifting chips, and infrastructure names swing on every OpenAI data point.
#StockMarket #AI #NVDA #ORCL #FICO
The bounce is trying, but the 10Y is still above 5.2%.
Premarket: S&P 500 ($SPY) +0.14% | Nasdaq 100 ($QQQ) +0.30%, leading the bounce
Monday: the Nasdaq 100 fell 1.08% to 30,276, the worst of the majors
10Y: 5.22% | Brent: $104.8
What's moving markets:
- Yields ease from 19-year highs, and Nasdaq futures are leading the rebound after Monday's tech sell-off.
- US–Iran talks on the Strait of Hormuz are back on, pulling oil lower.
- Strong data plus hot oil keeps Fed hike bets alive, so tech is still the most rate-sensitive trade.
In Stocks:
- $FICO −22%: the FHFA put VantageScore on equal footing in mortgage pricing, ending FICO's monopoly there.
- $AMD +1.2% on its $8.2B World Labs acquisition.
- $KMX +3.7%: a blowout quarter, with EPS $1.16 vs. $0.68 expected.
- $SMMT +17% after AstraZeneca invests $2B.
Nasdaq leads if yields cool, and bleeds first if they don't.
#StockMarket #Premarket #Nasdaq #FICO