OpenOre is open.
14,900+ deposits · 6,700+ mines · 1.18M licences · 230 jurisdictions — mapped, linked, and sourced, with every claim labeled by its evidence.
Free tier: full Atlas, watchlists with alerts, AI Analyst. No card.
https://t.co/6NcE0HC8CR
Five operations changed state this week. None because of geology.
Escondida: mediation requested
Centinela: strike begins
Sibanye-Stillwater: strike ends
Raspadskaya: fire halts output
Grota: court clears restart
Labour x3, fire x1, court x1.
https://t.co/T0aoSpxDTL
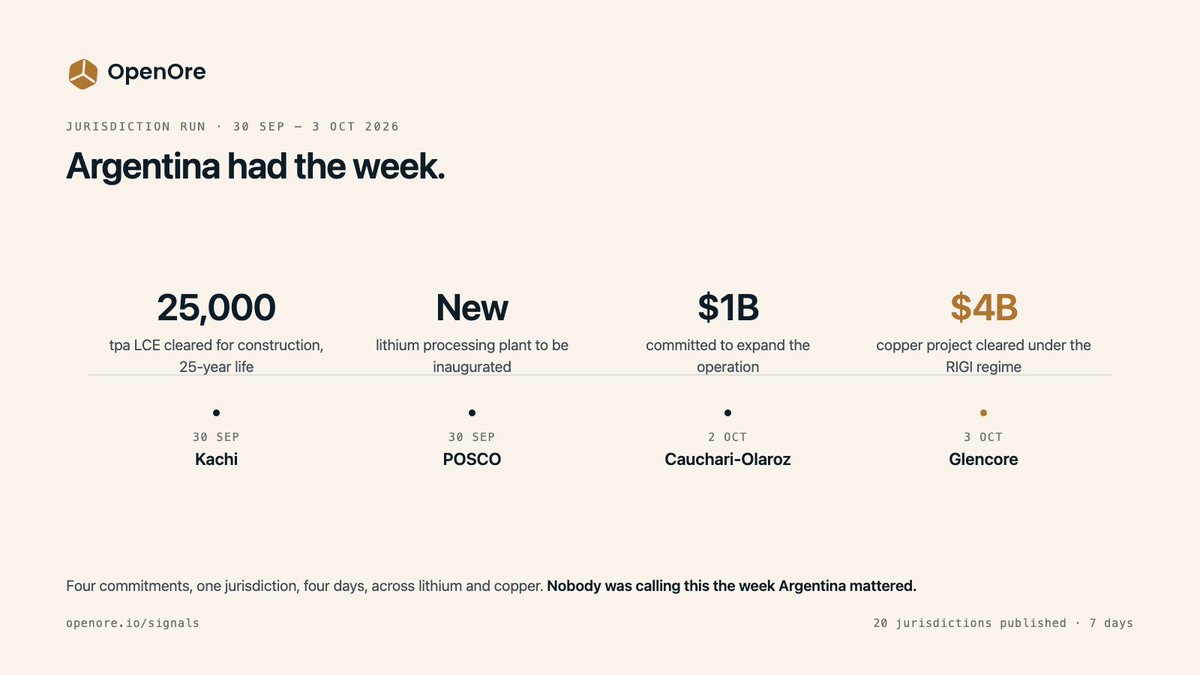
Four commitments, one jurisdiction, four days.
30 Sep: Kachi approved, 25,000 t/yr lithium
30 Sep: POSCO plant to open
2 Oct: $1B to expand Cauchari-Olaroz
3 Oct: Glencore's $4B copper project cleared
Argentina had the week.
https://t.co/T0aoSpxDTL
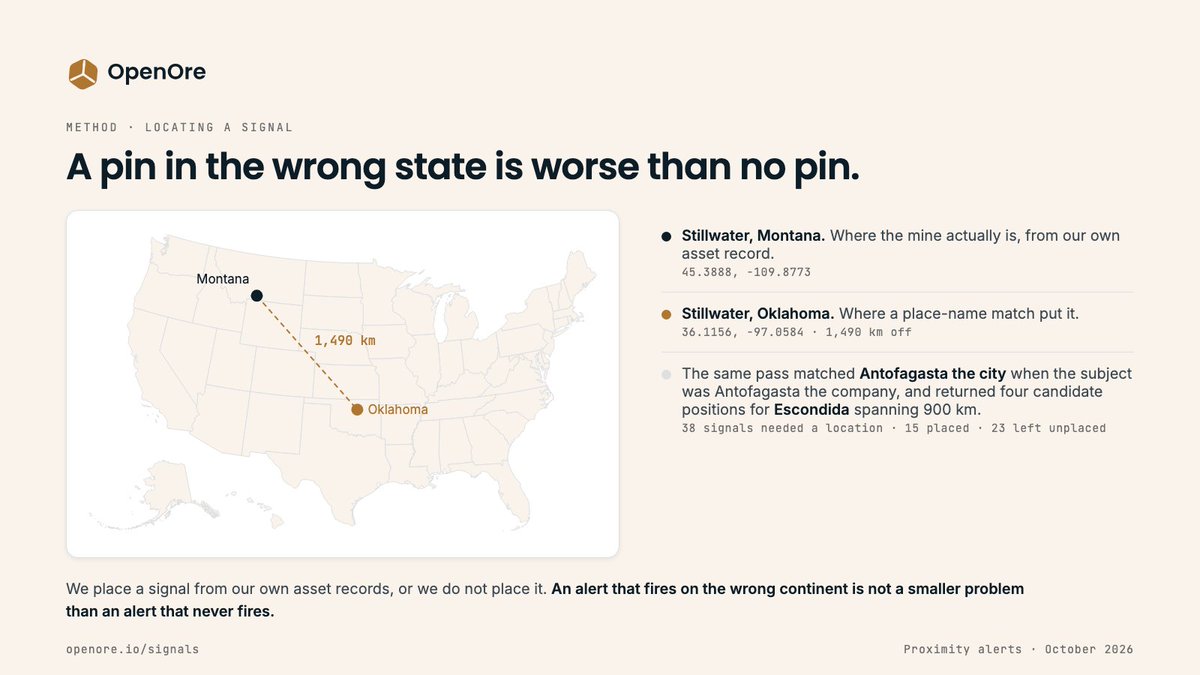
38 signals needed a location last week. We placed 15 and left 23 unplaced.
A place-name match put Sibanye-Stillwater's Stillwater mine in Oklahoma. It is in Montana, 1,490 km away.
An alert on the wrong continent isn't a smaller problem than no alert.
https://t.co/T0aoSpxDTL
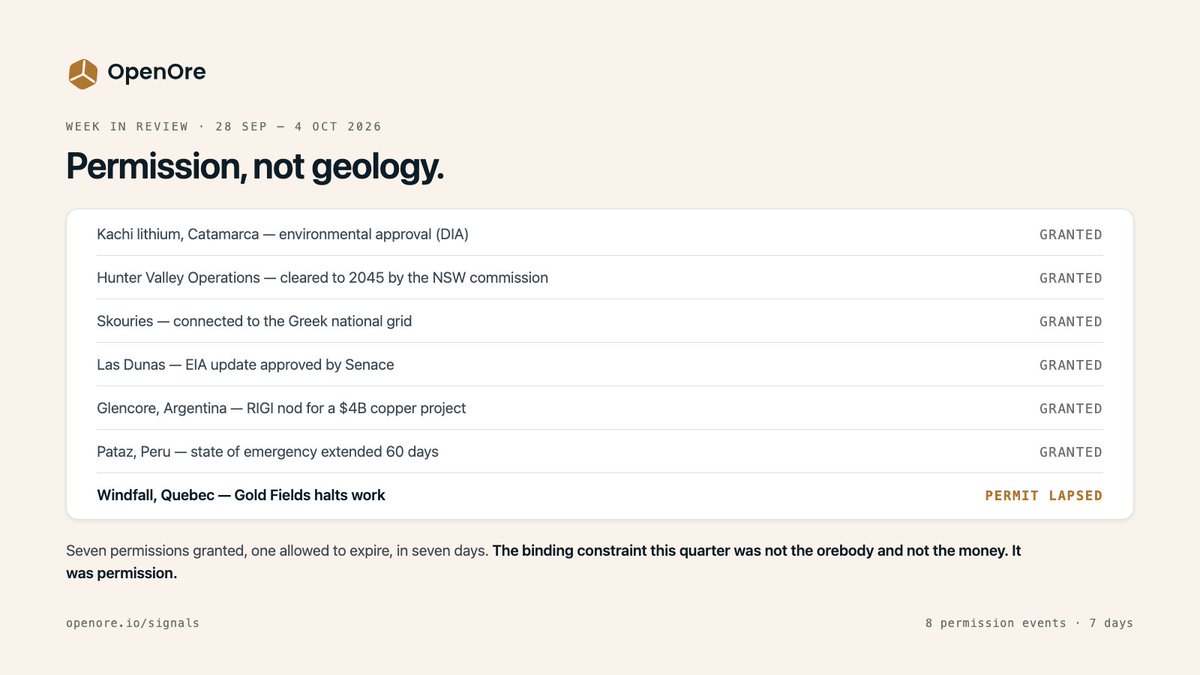
Seven permissions granted last week. One allowed to expire.
Kachi approved. Hunter Valley cleared to 2045. Skouries energised. Glencore's $4B copper project cleared.
And Gold Fields halted Windfall because a permit lapsed.
Permission, not geology.
https://t.co/T0aoSpxDTL
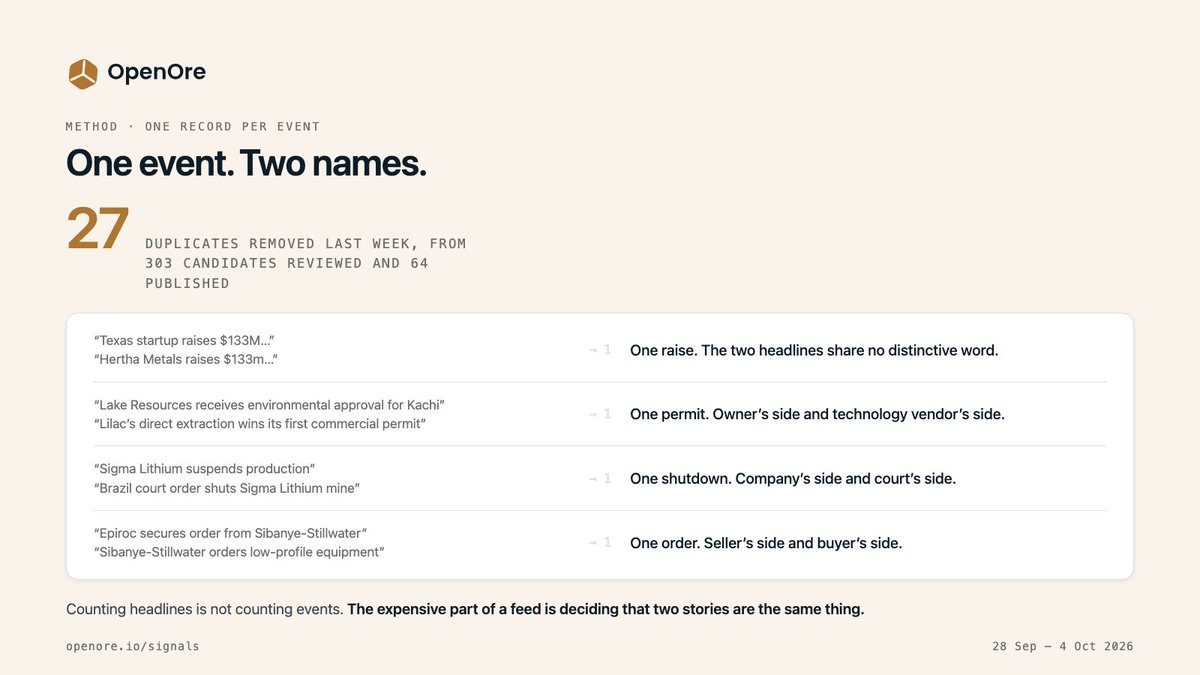
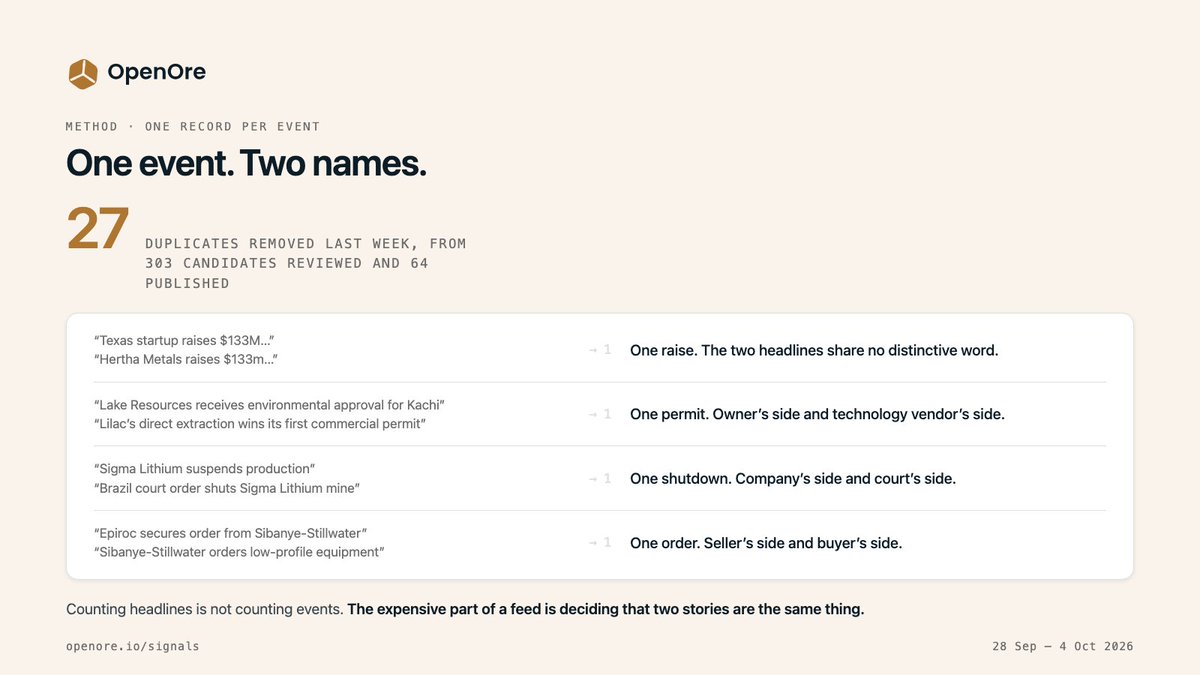
We reviewed 303 stories last week and published 64. We also removed 27 duplicates.
"Texas startup raises $133M" and "Hertha Metals raises $133m" are the same raise. They share no distinctive word.
Counting headlines is not counting events.
https://t.co/T0aoSpybJj
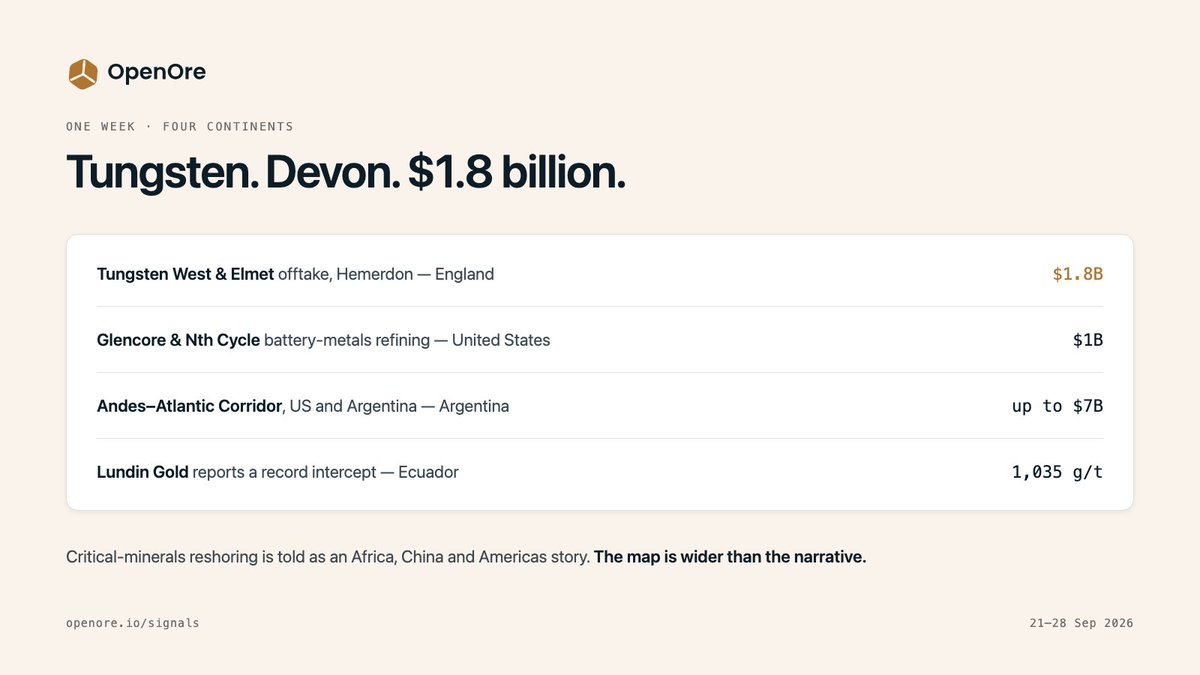
The biggest offtake we published last week was tungsten from a mine in Devon — $1.8B, Tungsten West and Elmet.
Same week: $1B US battery metals, $7B US–Argentina corridor, 1,035 g/t gold in Ecuador.
The map is wider than the narrative.
https://t.co/T0aoSpxDTL
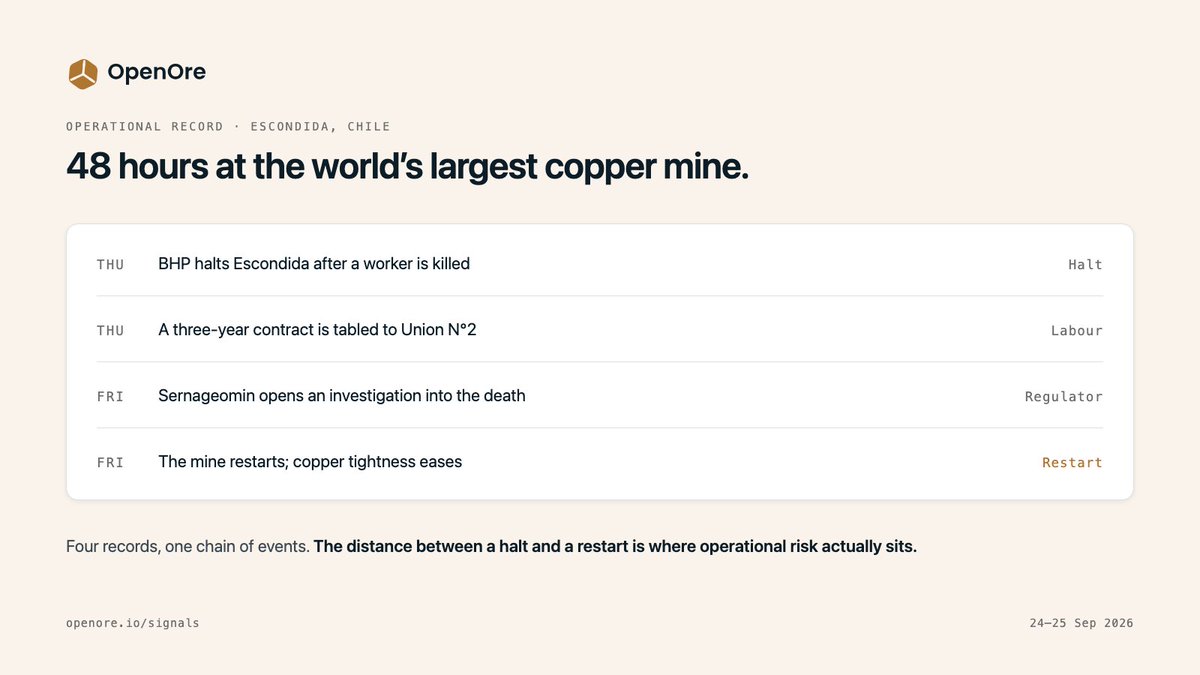
The world's largest copper mine stopped, was investigated and restarted in 48 hours.
Thu: BHP halts Escondida, a worker dead
Thu: 3-yr contract tabled to the union
Fri: regulator opens an inquiry
Fri: restart, tightness eases
Four records, one chain.
https://t.co/T0aoSpxDTL
Correction: the bid is A$38.7bn — about US$27bn, not US$38bn.
Our source reported "$38 billion" without a currency marker, and we carried it through unqualified. Two later sources settled it.
Our record has been corrected. Posting this rather than quietly fixing it.
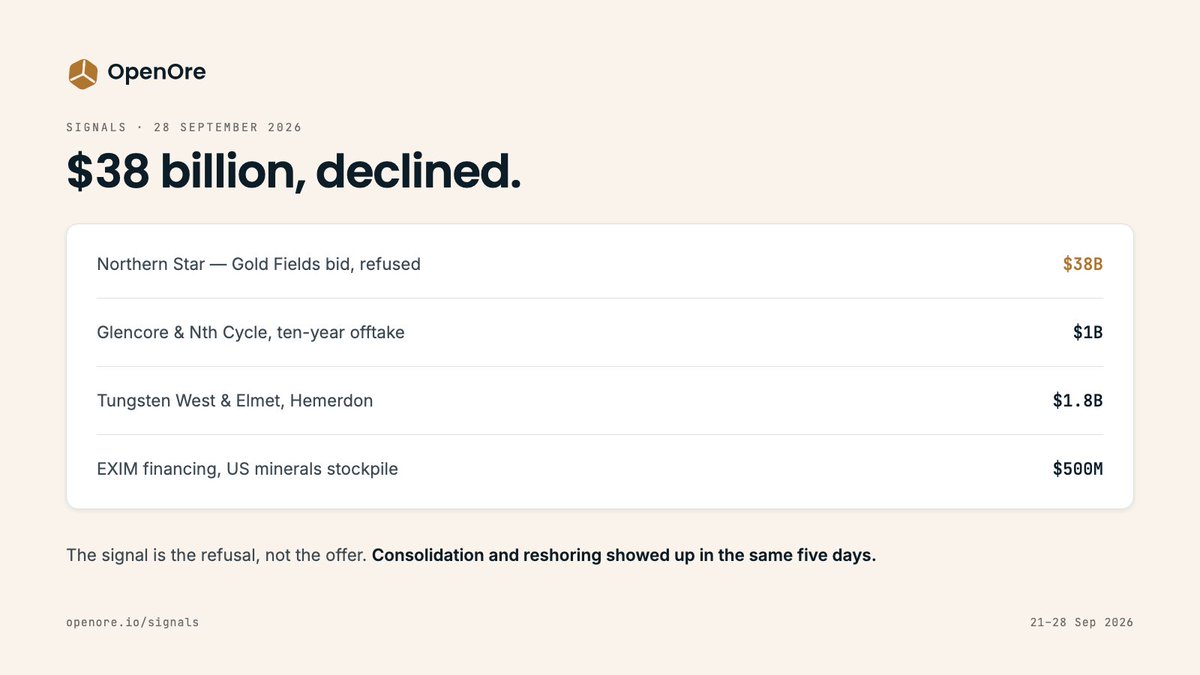
Northern Star turned down a $38B takeover from Gold Fields.
The signal is the refusal, not the offer.
Same week: $1B Glencore–Nth Cycle offtake, $1.8B UK tungsten, $500M EXIM for a US stockpile.
Consolidation and reshoring, five days apart.
https://t.co/T0aoSpybJj
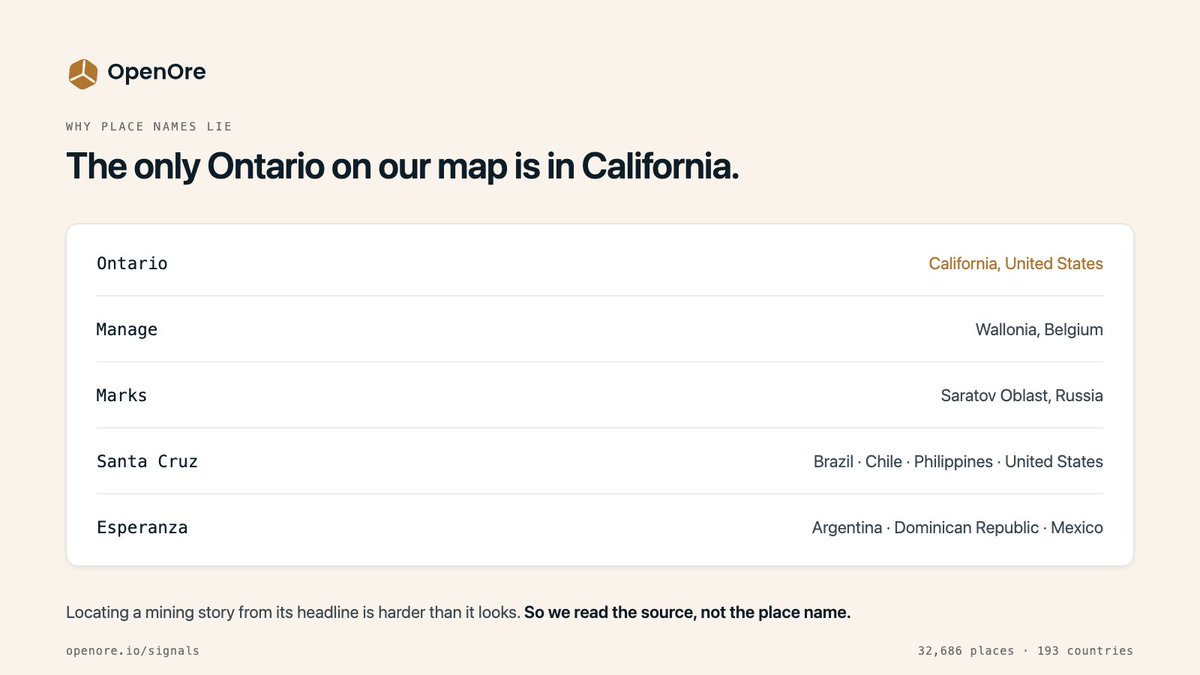
The only Ontario in our 32,686-place gazetteer is in California.
Manage is in Belgium. Marks is in Russia. Santa Cruz names places in four countries.
Locating a mining story from its headline is harder than it looks. So we read the source.
https://t.co/T0aoSpxDTL
Northern Star turned down a $38B takeover from Gold Fields.
The signal is the refusal, not the offer.
Same week: $1B Glencore–Nth Cycle offtake, $1.8B UK tungsten, $500M EXIM for a US stockpile.
Consolidation and reshoring, five days apart.
https://t.co/T0aoSpybJj
We hold 621,715 recorded security events.
We won't alert you on most of them.
Machine-coded news read a Poland airport story as an armed conflict in Bristol — that's the town that republished it. We measured it.
An alert has to say who stands behind it.
Last week: 322 candidates reviewed, 82 published, 240 rejected.
Not because they were false. Because they were thin — no named asset, no concrete commitment.
A feed you can trust is built by what you refuse to publish.
Four of last week's six biggest mining signals had the same author: a government.
- $450M DoW, tungsten
- $414M US loan, Niger uranium
- $100M DoE, Utah lithium
- C$1.3bn, Marathon Cu-Pd
When the state is your lender, policy risk and credit risk stop being separate columns.
One week, three signals:
→ REE recycling at commercial scale in Arizona
→ $73M DoE bet on domestic mining tech
→ EU scrutiny of the Anglo–MMG nickel deal
The critical minerals map is being redrawn by policy as much as geology. We keep the whole board visible.
Last week: our Lobito Corridor record.
This week: the system behind it.
36 corridors monitored daily, worldwide. And a hard rule — no data, no claim.
A licence is worth what the route to market is worth. https://t.co/6NcE0HCGsp
Codelco + Escondida copper output: down ~10% in July (COCHILCO).
Two operations moved the global supply picture in one month.
Concentration is fragility. We track it daily → https://t.co/T0aoSpybJj
1,181,233 licence records. 17 national cadastres.
And where a cadastre is closed or paper-only, we publish that too.
Knowing where the data ends is the product. https://t.co/6NcE0HC8CR
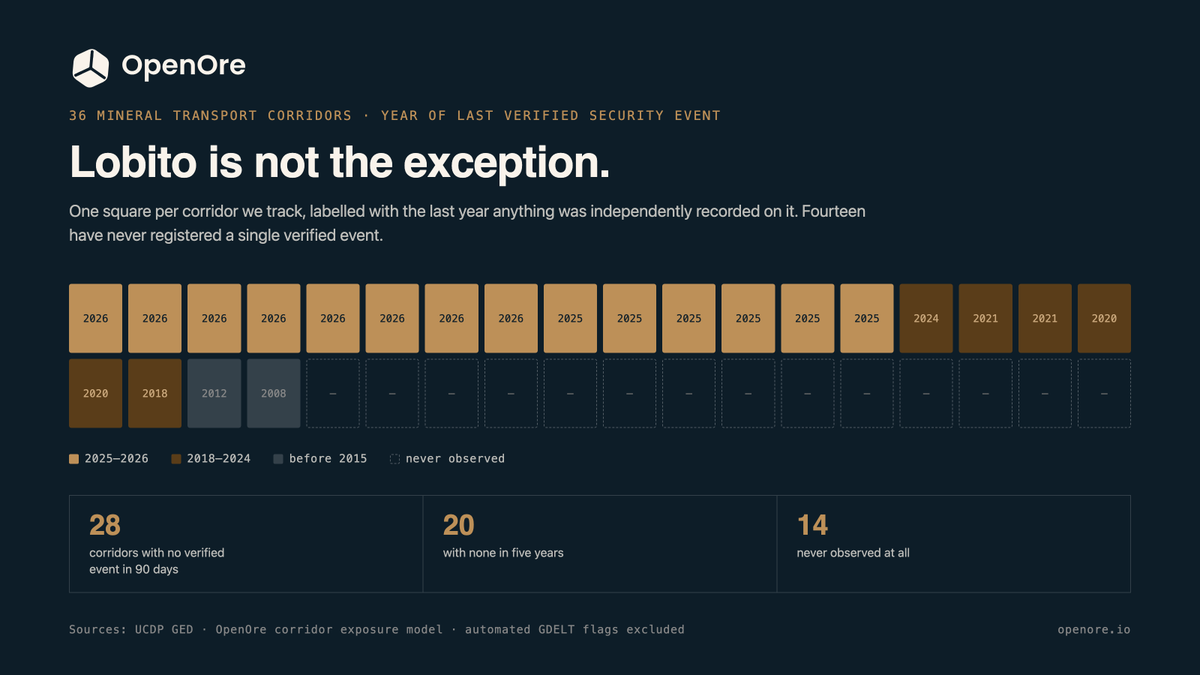
Yesterday: the Lobito Corridor's full security record.
Is it unusual? Same test, all 36 corridors we track:
28 — no verified event in 90 days
20 — none in 5 years
14 — never observed
Risk ratings often describe missing data, not safety.
Mining diligence starts with a question nobody answers in writing: can this country's register actually be consulted?
346 portals mapped across 203 countries. 52 countries formally assessed, each written to.
We'd rather publish the gap than paper over it.