AI token costs are going to continue falling aggressively.
This will bring low-cost, high-powered intelligence to every business.
An incredible economic boom of productivity and prosperity will follow.
If commercial paper deals penciled out at 30% down with 4% rate in 2021 on a 20 year am, and they are forced to refi at 7% now on 20 year am they are just not pulling money out, the deal still pencils
6% cap rate is and was stupid in my opinion. 4’s and 5’s were ludicrous, and because those deals blow up is no one’s problem but the aggressive buyers and banks being reckless
With rates at 7% on commercial paper who TF paying 6% cap. 8% should have always been the number for this shit not 6%
Just another example of large funds locking out the smaller guys with this nonsense.
I just got off the phone with one of the world’s most respected chart squigglers. He has averaged $92,000 of profit every year for the last 12. He says we are virtually guaranteed to see $40,000 Bitcoin in October. I hung up and placed a limit order to buy all the Bitcoins there.
I’d love to do more spaces with people in real estate. Whether it be $OPEN $RKT $UWMC $FNMA #FedTalk.
LMK if you want me to come in on any of them
Market might do -6% next year, it may do nothing, but it’s not crashing or booming. Realist over here
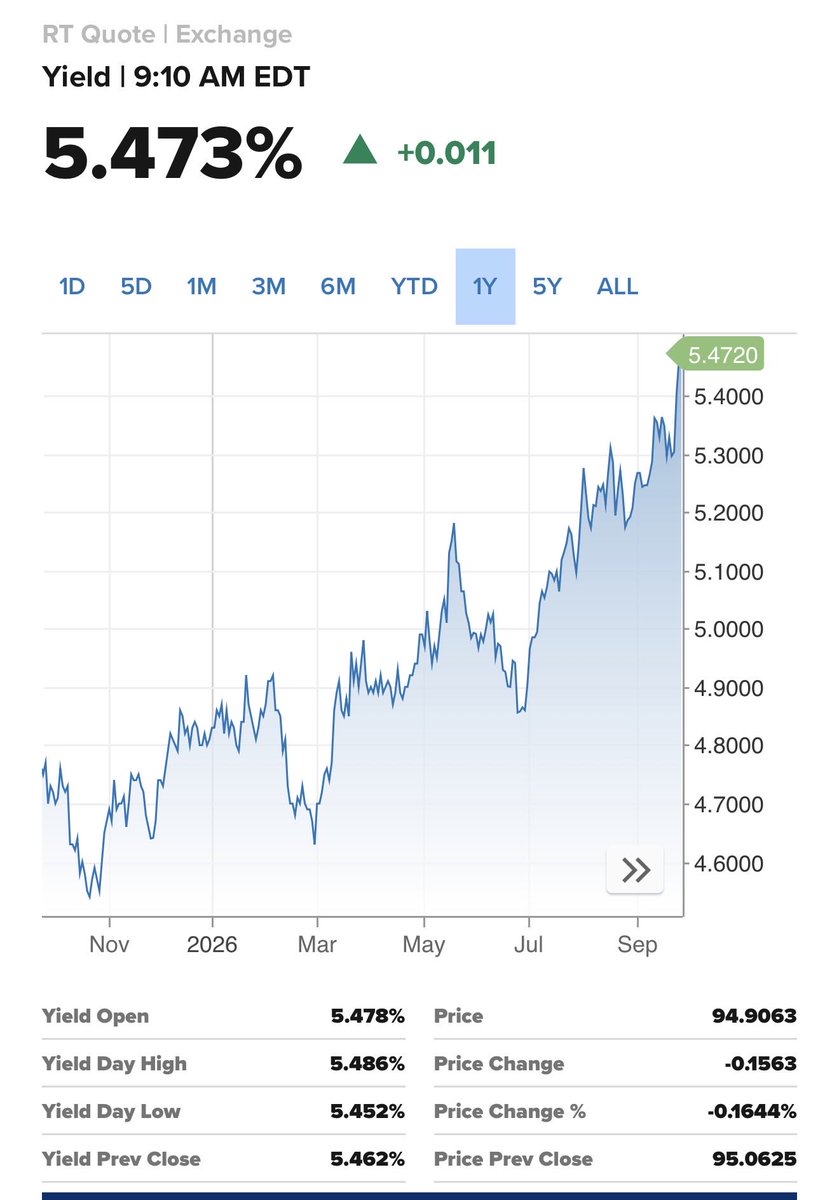
Warsh is trying to cause a 1994 bonds market massacre because recession was avoided then @BillAckman
Guidance was created after 1994 and taken away with Warsh. Fed is 100% making a mistake
The presumption that the Fed raising short-term rates reduces inflation is predicated on the belief that higher rates reduce demand and investment.
But what if higher rates don’t reduce demand and investment because the demand for intelligence and energy is unaffected by higher rates because winning the race for super intelligence has a near infinite ROI and the demand for compute will remain incalculable.
Why won’t higher rates at this unique moment in history therefore lead to more inflation as interest costs are embedded in everything?
And the problem is compounded as the more the Fed raises rates, the more inflation we will have and the more the Fed will need to raise rates further and so on.
But what if the old models don’t apply to the current paradigm and the Fed is wrong?
I think the Fed might have just made a mistake. Am I right or am I wrong?
At 6% wealthy buyers flood real estate again. Finance at 8% on 30 year buy bonds at 6% let bonds fall back to 4% make 20% there plus refi in mid 5’s and watch real estate pop
Rich get richer. 6% is the number IMO
-6% over next 12 month in real estate if we stay around 7.5% is my projection. Yes it’s localized and we are a high demand area. National average likely worse
I built this out in August when mortgage rates were around 6.5%. Click on the Purple tab about halfway down. It takes about 3 months for the system to absorb the full effect of rising rates. https://t.co/apC7vEjV2m
Under 600k market, Expect to see listings expire and transactions to come to a halt.
When a boomer or person that studies rates says well we are at an historical norm on rates remind them that the effective rate of 7.5% on 30 year now is close to 11-12% in the 70’s and 80’s when you factor income to living affordability strain. You must factor healthcare, food, schooling, etc., and then one realizes this rate is not sustainable
Warsh is attempting a 1994 style bonds market massacre, which avoided a recession, but the economic factors are far different today.
Greenspan started guidance from massacre and Warsh pulled them….. #FED get your shit together and #Trump get your shit together too. @pulte read this
$OPEN $RKT $UWMC $FNMA $EXPI
@koremasa21022@FBiadu98 Yes they take your home and force sell it after a couple days of your price then says they are 20% under mls sales timelines. Well that’s because it’s underpriced