Nippon Steel’s $14.9B deal for $X is done! Trump’s golden share gives U.S. control, but will it boost or spook investors? Union opposition fading, and Third Point’s stake adds fuel. Thoughts on $X’s future? #USSteel#Merger
Gold’s shining bright, hitting record highs with a 4% surge! Investors piling in as a safe haven. You stacking gold or sticking with stocks? Share your strategy! #Gold#PreciousMetals#Investing#StockMarket#SafeHaven
📉 Tech stocks are wobbling ahead of Powell’s Jackson Hole speech, while defensive sectors shine.
Is this the start of a bigger rotation, or just market jitters? 🤔
#StockMarket#Investing#Fed#TechStocks#Finance
"S&P 500 expected to end 2025 slightly below current highs (~6,300), as tariffs and Fed uncertainty weigh on sentiment. #InvestingOutlook what's your take?
NEWS: Nissan has officially announced that its next-generation Leaf EV will start at $29,990 in the US this Fall with 303 miles of EPA range.
Trims & starting price:
• Leaf S+: $29,990 (303 miles)
• Leaf SV+: $34,230 (288 miles)
• Leaf Platinum+: $38,990 (259 miles)
This will be the lowest starting MSRP price for any new EV on sale in the US when deliveries start in a couple months:
• 75-kWh battery
• Two charging ports: Passenger's side is a NACS port, driver's side is a J1772 port
• Up to 214 hp
• Fastback roofline
• Two 14.3" screens
• 360-degree camera view
• Electrically dimming panoramic roof, a first for Nissan
• Cargo capacity is 20 cubic feet with the rear seats up, while folding them opens up the Leaf to swallow 56 cubic feet
• No self-driving technology
• Drag coefficient of 0.26
• 4-speaker sound system on $30k S+ trim
• Ground clearance: 5.3"
• Weight on S+ trim: 4,187 lbs
• No battery heater on $30k S+ trim. Higher trims have it.
Deliveries begin Fall 2025 in the U.S.
$TSLA Summary - 6/17/2025
Positive Catalysts:
1/ Trump streamlines federal process allowing TSLA to secure general unsupervised autonomy license nationally
2/ More affordable vehicle launch in 2025/3Q can expand TAM if it’s a different form factor (e.g. hatchback, smaller M-Y).
3/ FSD licensing deal with 1 or more OEMs
4/ TSLA likely first to market with generalized unsupervised FSD FY’25 YE
5/ DE Supreme Court overturns Chancellor McCormick’s 2018 comp ruling late 2025
6/ Cybercab production begins 2026
7/ Optimus production begins late-2026
Negative Catalysts:
1/ Trump eliminates $7,500 IRA EV purchase credit
2/ Trump admin restricts state efforts to control carbon emissions, which could significantly reduce TSLA ZEV sales.
3/ TSLA fails to introduce new cheaper form factor in 2025/1H, and instead cuts prices and costs similar to 2023-2024
4/ FY’25 EPS expectations continue to fall (-33% past 3 months) as FY’25 delivery ests fall (2Q -12% YoY, FY’25 -6% YoY).
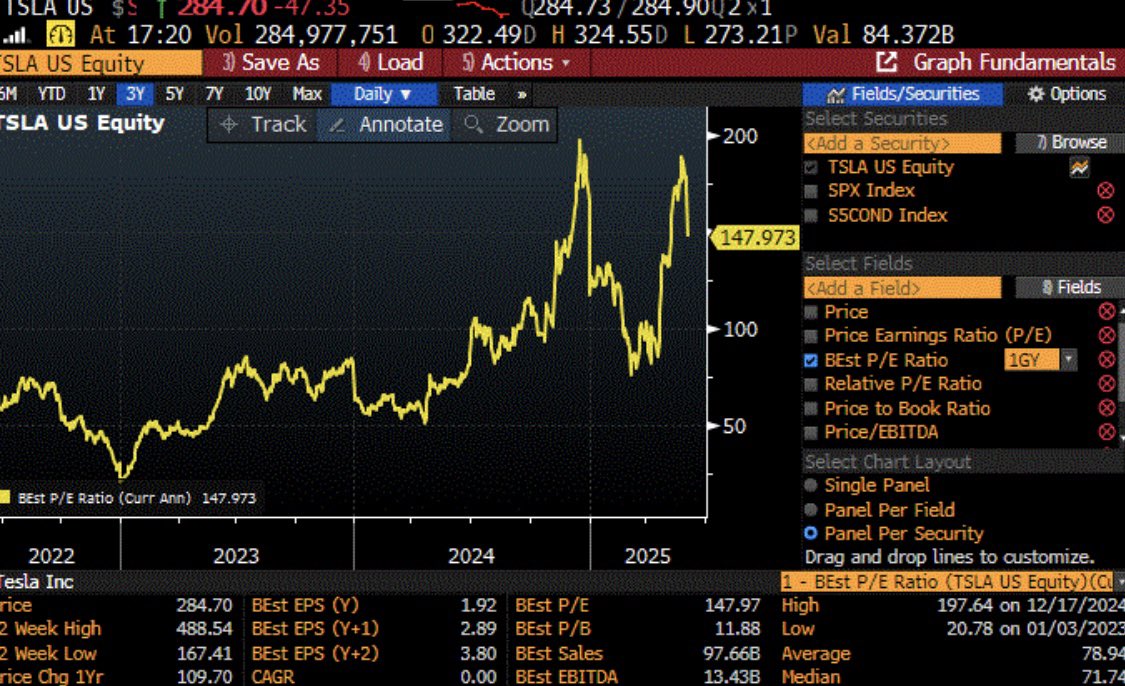
5/ TSLA 2025 P/E of 170x too high relative to FY’25-‘30 EPS growth of +25% CGR. Avg forward P/E past 3 years 80x.
$TSLA 6-12 month price target $310
Seven democrats in the TX House and Senate have asked $TSLA to delay the rollout of TSLA’s scheduled June 22 Austin robotaxi launch until Sept 1, when new autonomous driving regulations are scheduled to go into effect.
As the last sentence reads, Tesla can proceed with the June 22 launch if it “respond(s) to this letter with detailed information demonstrating that Tesla will be compliant with the new law upon the launch of driverless operations in Austin.”
The biggest mistake $TSLA bears make is slapping an auto industry P/E on TSLA’s EV business. From long-term $TSLA bear Drew Dickson’s latest report: “We can make a simple determination of what the automobile business is worth. And, by implication, the balance must be these other "Musk Options." In auto-land, the average P/E for Ford, BMW (XE:BMW), Mercedes (XE:MBG), GM (GM), Renault (FR:RNO), Stellantis (STLA) and Volkswagen (XE:VOW) is 6.5x. Include Honda (JP:7267), Toyota (JP:7203) and SAIC (CN:600104), it is 7.7x.”
“If we assume the Tesla automotive business - despite all its deteriorating metrics - is a better business and deserving of a higher multiple than each of them, perhaps we can say it should be worth a P/E of 10x. Maybe we could even say 15x. At a 2025 P/E of 15x, Tesla's auto business would have market cap of $100 billion. That is still a heck of a lot, more than any other automaker except Toyota (which generates 5x more sales and Ebitda). And if we assume we are close, that means that the market already values Tesla's FSD, robotaxis, Optimus and the energy business at roughly $1 trillion. And for the Tesla fans laughing at our valuation of the automotive business, even if Tesla's automotive business were worth twice that amount (a P/E of 30x), the "Musk option" would be valued at $900 billion. In other words, Tesla's share price already assumes - and prices in - a tremendous amount of success for Tesla's non-automotive manufacturing businesses.”
While we have high respect for Drew as a reasonable bear, we believe his approach is flawed because P/Es are based on forward revenue and earnings growth rates of businesses, and not the industry in which they compete. Does $CAVA trade at the same P/E as $MCD? Does $ONON trade at the same P/E as $NKE? Does $COST trade at the same P/E as $TGT? The answer to all of these is of course not.
To say that $TSLA should trade at no more than a 15x P/E just because GM, F, STLA, VW, and TM trade at 7-8x EPS ignores the fact that TSLA is 100% EVs which are growing at 25-30% per year while ICE vehicles are in a state of permanent decline. Of course there should be a huge difference in P/Es between EV manufacturers and ICE manufacturers given stark differences in growth prospects.
We continue to like $TSLA longer-term but remain concerned about the near-term asymmetrical risk/reward associated with the Austin robotaxi test that begins 6/22. We also worry that the more affordable vehicles targeted for 3Q will be lower cost, lower priced M-3 and M-Y that are not new form factors and do not increase TSLA TAM but instead cannibalize the more expensive M-3 and M-Y trims. Finally, we believe TSLA 2Q volumes are likely to again disappoint (~380K -14% YoY vs Street consensus of 402K -10% YoY) as the China EV price war led by $BYDDY and the U.S./European brand taints take their tolls on 2Q deliveries to be announced 7/2.
$TSLA faithful arguing that Elon separating from Trump is a good thing is hilarious. These same bulls argued for months that the Musk-Trump alliance would streamline the federal process allowing TSLA to secure general unsupervised autonomy license nationally. That prospect is now highly unlikely.
At $278 AH, TSLA is now trading at 149x FY’2025 EPS (vs 79x historically) which now seems even more stretched without Trump in Elon’s corner on a national autonomy standard.
$TSLA China reported 13,060 insured registrations for the week of May 26-June 1. After 9 weeks, the quarter is +2.6% QoQ and -21.4% YoY. This was the highest week of the quarter so far. Source: @piloly@Tslachan
Earnings season heats up! $NVDA’s Q1 2026 report drops May 28—will it keep its 16% rally alive? Meanwhile, $UNH’s 17% plunge has bargain hunters circling. What’s your move? #StockMarket#Earnings