🇵🇭 PrimeLendRow shared its latest progress during our Stellar PH Builder Checkpoint, Batch 1! ⚡
The team walked us through their lending platform, showcasing key parts of the user journey:
🔹 Identity verification to support borrower onboarding
🔹 Loan dashboard to view loan information and lending activity
🔹 Lending operations to manage loan-related transactions and repayment workflows
Built on @StellarOrg, @PrimeLendRow is exploring how on-chain lending can become more accessible, with credit scores informed by actual loan outcomes.
From concept to working demo, tuloy-tuloy ang pag-build! 🚀 Excited to see what the team ships next.
Learn more below 👇
#BuildOnStellar 🇵🇭
4 weeks of building PrimeLendRow on Stellar.
• On-chain XLM collateral custody via Soroban
• Lending backed by up to 2 guarantors
• Transparent, precise interest split distribution
• Credit scores rise only at term-end, drop on default
Building a more transparent lending ecosystem.
@StellarOrg@PHI_Stellar@riseinweb3
Interesting update from @PrimeLendRow. 👏
Making credit scores based on actual loan outcomes, with every change publicly verifiable, adds a clear layer of transparency to lending.
The anti-farming rules and fixed loan terms also make the scoring system more meaningful. ����
#BuildOnStellar 🇵🇭
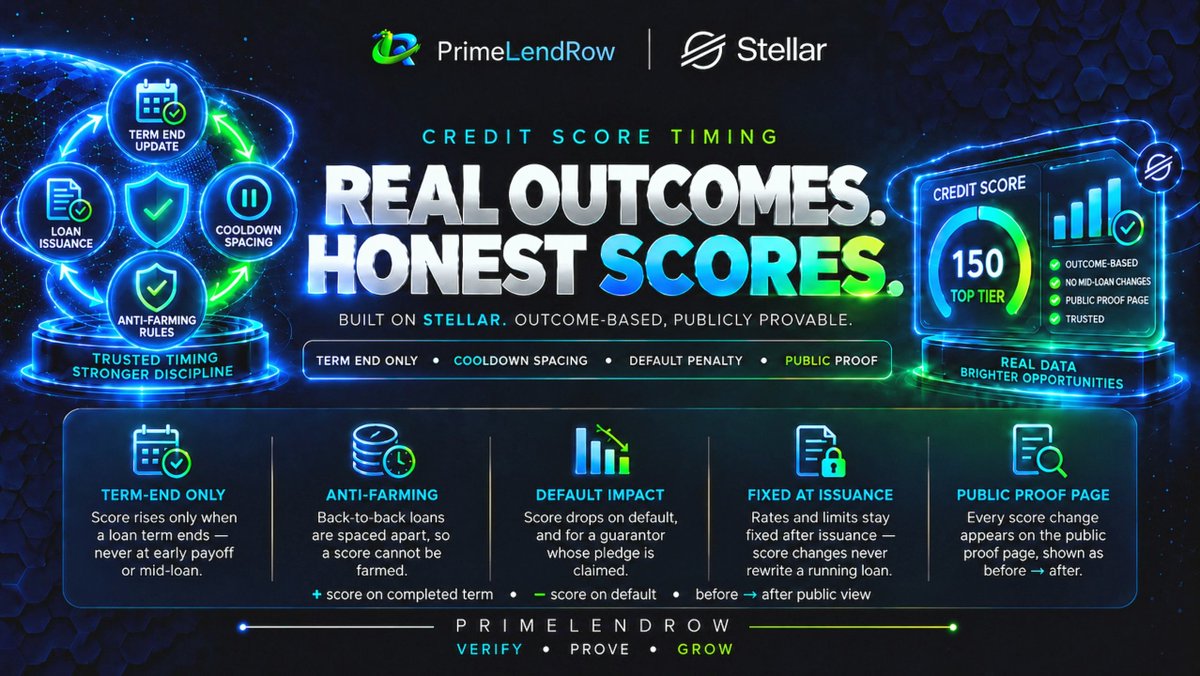
Credit score on PrimeLendRow now moves on outcomes only.
• Score rises only when a loan's term ends, never at early payoff or mid-loan
• Back-to-back loans are spaced apart, so a score can't be farmed
• Score drops on default, and for a guarantor whose pledge is claimed
• Rates and limits are fixed at issuance, so a score change never rewrites a running loan
• Every score change shows on the public proof page, before → after
@StellarOrg@PHI_Stellar@riseinweb3
PrimeLendRow built a transparent Interest splitting.
• 10% platform • 20% reserve • 40% depositors • 30% risk band
• Guarantor rewards scale by credit tier, up to 25% of interest
• Whole-centavo calculations with deterministic rounding
• Credit score moves on repayment outcomes, not activity
• Every split and score change is recorded and auditable
@StellarOrg@PHI_Stellar@riseinweb3
CLARITY failed to advance.
Stellar $XLM didn’t stop. ⭐️
✅ Denelle Dixon said it before the vote:
“Progress should not pause for policy.”
Now look at the numbers.
🏦 $4B in tokenized RWAs on Stellar
📈 ~$2.5B in tokenized fund growth YTD
�� $8.92B in stablecoin transfers over the last 30 days - up 50%
⚙️ 11.6M+ transactions processed in a single day
That’s the point.
Regulatory clarity matters.
But $XLM adoption isn’t sitting in Washington waiting for a green light.
The assets are already being tokenized.
The stablecoins are already moving.
The network is already processing millions of transactions.
CLARITY can be delayed.
Stellar’s buildout doesn’t have to be. 🌐
And if regulation eventually catches up, it may find an ecosystem that’s already operating at scale.
#Stellar #XLM
prosperity doesn’t come from the white paper.... it comes when the cost of being in the financial system falls to near zero and the full stack actually works: wallet, stablecoin, off-ramp, card, settlement.
that’s the good and @PrimeLendRow build that.
Clarity this, clarity that.
All that's clear to me is that I woke up this morning to see the Stellar ecosystem grow and usher in the future of finance.
PrimeLendRow is beyond collateral-lending only.
We’ve built guarantor-powered lending on Stellar Testnet, giving borrowers another path to access credit while keeping the lending flow transparent and enforceable.
• Up to 2 guarantors can back a borrower
• Guarantor pledges are locked and tracked
• Stellar-verified transactions and collateral
• Stripe-powered fiat funding and collections
• Auditable repayment and recovery flows
Real backing. Real access. Built for a more accountable lending system.
@StellarOrg@PHI_Stellar@riseinweb3
6/ Reputation is the new financial capital.
Not because it sounds nice.
Because it is the only collateral that travels when the bureau says you don’t exist.
FICO is a black box because opacity is the product.
You can service every obligation on earth and still be a ghost if you never rented the right kind of debt from the right kind of bank.
Credit was never “can you pay.”
It was “did you already pay us.”
Borrow. Repay. Repeat.
That’s duration. That’s a track record. That’s the only input that should price the next loan.
Reputation is working capital.
The score should just be the receipt.