How can a country lift 496 MILLION people out of poverty, yet still have a notoriously small market for startups and discretionary spending? 🧵👇
We compared the World Bank's latest India Poverty Brief with Blume’s Indus Valley Report.
Escaping extreme poverty is a survival milestone, not a consumption boom.
With flat real wages and high youth unemployment, millions have crossed the welfare floor, but they still lack the extra income for discretionary spending.
Here is the side-by-side breakdown:
Delhi is currently ranked the World's most polluted city, with an AQI reading of 1,744.
The hazardous category starts at 300. This is nearly 6 times that threshold.
The frightening part is that pollution doesn't just affect people today. Years of exposure can have devastating consequences for children's development, lung health and life expectancy.
How did we allow this to become normal?
Clean air should not be a privilege but a basic right.
#Pollution
🚨 MARKET BREADTH DECLINES
Nifty is resting after the explosive upmove, which is a healthy sign.
▶️ Stocks above 200 SMA fell below 40%
▶️ Stocks above 20 SMA stayed above 70%
▶️ Net New Highs improved slightly to +1.9%
▶️ Around 38% stocks closed in green today
Full breadth data👇
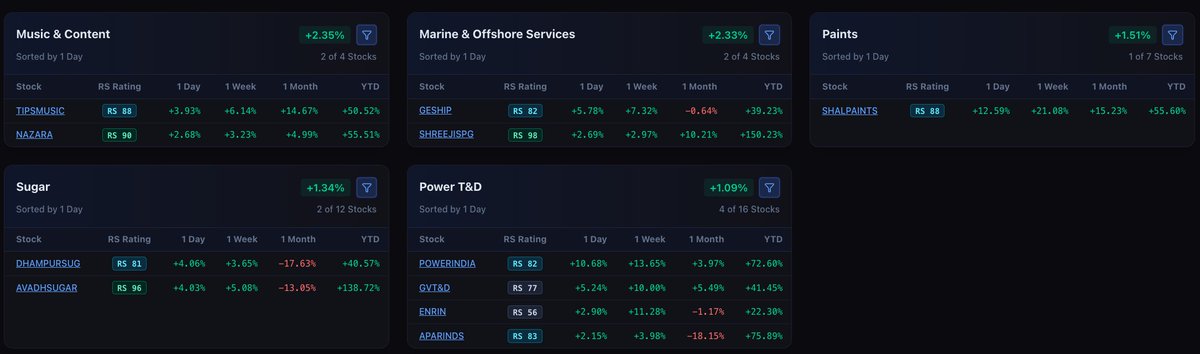
🚨 TODAY’S TOP GAINING SECTORS
▶️ Music & Content → +2.35%
▶️ Marine & Offshore Services → +2.33%
▶️ Paints → +1.51%
▶️ Sugar → +1.34%
▶️ Power T&D → +1.09%
Full list with 1 Week, 1 Month, YTD return + RS Rating in the attached screenshot 👇
Keep reading for the top stocks driving these sectors →
Jensen Huang resigns, $NVDA gaps down ~13% at the open to $151, and buyers immediately step in to absorb the panic.
Markets hate leadership vacuums, but institutions are clearly defending the $152 support ahead of Nov 17 Q3 earnings.
Jensen Huang resigns, $NVDA gaps down ~13% at the open to $151, and buyers immediately step in to absorb the panic.
Markets hate leadership vacuums, but institutions are clearly defending the $152 support ahead of Nov 17 Q3 earnings.
The debate on #CUPID post-Q2 results & the guidance upgrade:
• The Bull Case: Q2 PAT more than doubled (+133% YoY to ₹56.22 Cr), H1 PAT crossed ₹100 Cr (+156% YoY), FY27 guidance was hiked again to ₹880 Cr+ Rev / ₹275 Cr+ PAT, Palava plant doubles capacity in Q3, and V2 Retail + Baazar Style lock in massive modern-trade visibility.
• The Counter / Monitorable: Q2 EBITDA margin compressed 449 bps YoY to 29.16% as fast-moving domestic retail scaled up, and aggressive balance sheet deployment into PPE capex (₹78.8 Cr) and Baazar Style equity warrants (~₹137.9 Cr balance conversion) demands tight cash-conversion tracking in H2.
Are you backing Cupid's multi-year compounding target toward ₹1,950 Cr by FY29?
Why the gap between salaries and fortunes keeps widening:
• Wages scale linearly with hours worked
• Equity scales exponentially with distribution and margins
• Inflation punishes cash savers and rewards asset owners
Profit per employee isn't going down in an AI economy. The only real hedge against automation is owning equity in the machines and not just renting out your hours.
Why the gap between salaries and fortunes keeps widening:
• Wages scale linearly with hours worked
• Equity scales exponentially with distribution and margins
• Inflation punishes cash savers and rewards asset owners
Profit per employee isn't going down in an AI economy. The only real hedge against automation is owning equity in the machines and not just renting out your hours.
@SwarajSwaraj0 That is the exact trap central banks walked into during the 1970s.
Raising rates fixes demand-driven inflation, not supply-driven energy shocks. If they hike into elevated crude, they risk crushing growth while inflation stays sticky anyway.
The debate on #CUPID post-Q2 results & the guidance upgrade:
• The Bull Case: Q2 PAT more than doubled (+133% YoY to ₹56.22 Cr), H1 PAT crossed ₹100 Cr (+156% YoY), FY27 guidance was hiked again to ₹880 Cr+ Rev / ₹275 Cr+ PAT, Palava plant doubles capacity in Q3, and V2 Retail + Baazar Style lock in massive modern-trade visibility.
• The Counter / Monitorable: Q2 EBITDA margin compressed 449 bps YoY to 29.16% as fast-moving domestic retail scaled up, and aggressive balance sheet deployment into PPE capex (₹78.8 Cr) and Baazar Style equity warrants (~₹137.9 Cr balance conversion) demands tight cash-conversion tracking in H2.
Are you backing Cupid's multi-year compounding target toward ₹1,950 Cr by FY29?
Historic shakeup in Indian broking
For the first time in 3 years, India's Top 3 broking hierarchy has reshuffled.
Angel One has officially overtaken Zerodha to become India's 2nd largest stockbroker.
NSE Active Clients Leaderboard (Oct 2026):
1. Groww: 1.38 Cr (+3.04L MoM) | 29.43% Share
2. Angel One: 69.98L (+2.43L MoM) | 14.97% Share 🔼
3. Zerodha: 67.59L (-32.4K MoM) | 14.46% Share 🔽
4. ICICI Sec: 21.64L (+3.7K MoM) | 4.63% Share
5. Upstox: 18.43L (-11.3K MoM) | 3.94% Share
6. Kotak Sec: 14.05L (+12.9K MoM) | 3.01% Share
7. HDFC Sec: 13.60L (+6.0K MoM) | 2.91% Share
8. Dhan: 11.47L (+25.7K MoM) | 2.45% Share
5 structural takeaways from the October NSE print:
• 89% Acquisition Duopoly: Groww (+3.04L) and Angel One (+2.43L) captured 5.47L of the industry's 6.15L net additions.
• The #2 Flip: Two months of contraction at Zerodha paired with Angel One's 9-month high gross additions (6.6L) sealed the overtake.
• Legacy Outflows: Zerodha (-32.4K), Paytm Money (-32.5K), and Upstox (-11.3K) all bled active users amid retail F&O churn.
• Challenger Surge: Execution-focused platforms Sahi (+34.4K to 3.15L) and Dhan (+25.7K to 11.47L) led mid-tier growth.
• Scale vs ARPU: Top 3 control 58.9% of the market. Listed giants are chasing MTF scale, while bootstrapped Zerodha protects high-ARPU margins.
#NSE #AngelOne