Unhinged Momentum Against Timed Momentum: The Rate of Change, Applied to Time It and to Tame It. Every six months from 2006 to 2025, we took the S&P 500's ten steepest trends and ran them twice. Once as is, once with rate-of-change indicator.
https://t.co/EHMbrb41Nk
We built one S&P 500 stock portfolio that picks its stocks by value, quality and momentum, weighted by the market's regime. Then we ran it twice from 2006 to 2025: once with a hidden Markov model deciding the regime, once with the VIX.
https://t.co/FEv1LkEE65
Andreas Clenow's book "Stocks on the Move" In short: buy the stocks that rose fastest and most smoothly over the last three months, and stop buying new stocks while the whole market is falling. The book's promise is to beat the market. We tested it apart.
https://t.co/cnaHoPyIUB
QuanterLab is now listed in Anthropic's own directory.
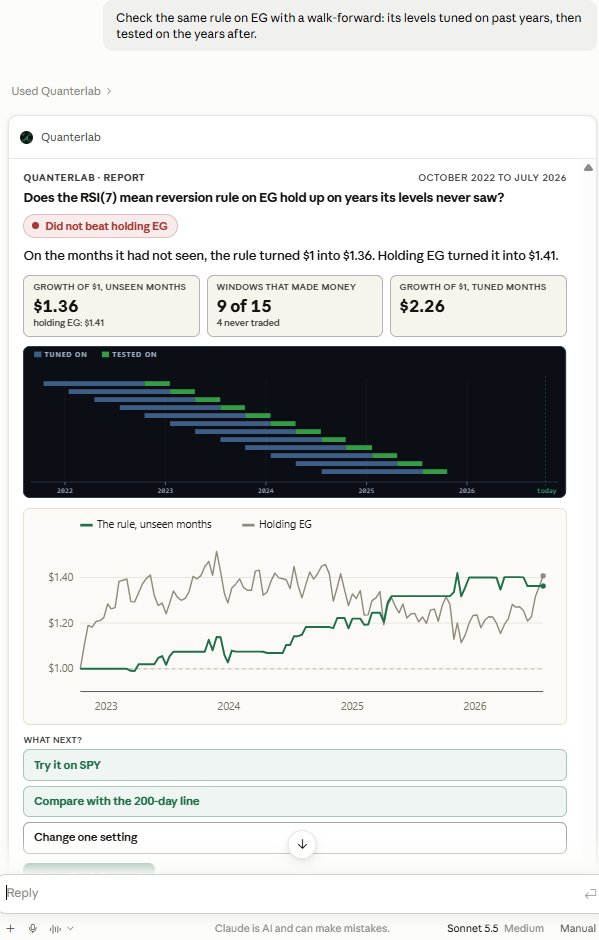
Describe your rule in a Claude chat and QuanterLab tests it for you:
"Would the 200-day line have beaten simply holding Tesla?"
Free runs every day.
https://t.co/HoNjqNq3ZQ
Two Kinds of Crash, Two Kinds of Protection: the 200-Day Line and Volatility Targeting, 2000 to 2025
Two famous crash rules, tested on SPY over a quarter century and on 13 other funds.
https://t.co/YiXlnG94zB
In Search of the Market's Payday. We slid a window across the month and the strongest days come a few days earlier, so the famous four days start on a day that lost money on average.
https://t.co/tYqrMzcPar
QuanterLab is now in ChatGPT's plugin directory.
Add it and ask ChatGPT about any of our walk-forward studies: it reads the paper and answers with the numbers and a link to the page.
Works with a free QuanterLab account.
https://t.co/w5UNZ4kcJr
Mean reversion is the idea that a price pushed too far in a few days tends to come part of the way back. The research explains it as a trade, discusses the mechabism.
https://t.co/TKiYjbxtSL
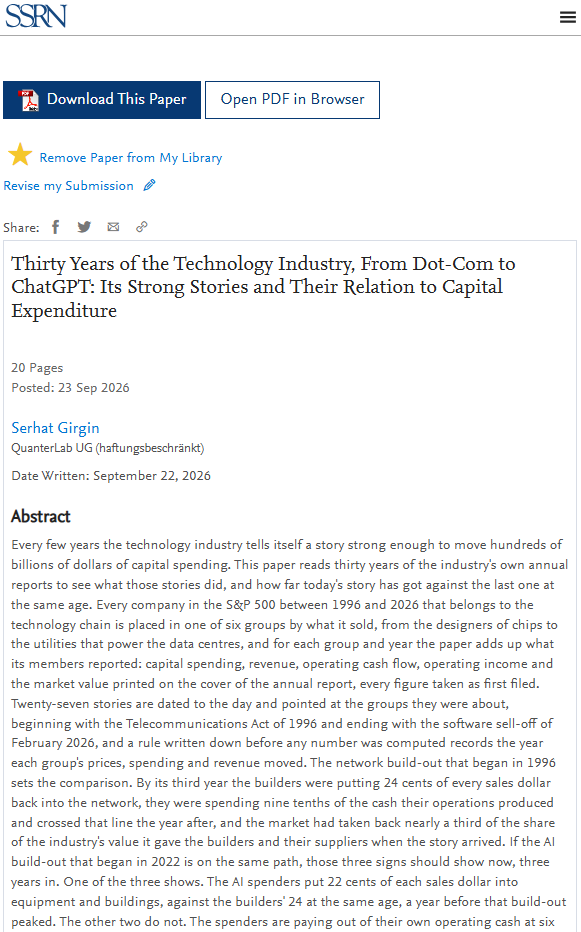
Thirty Years of the Technology Industry, From Dot-Com to ChatGPT: Its Strong Stories and Their Relation to Capital Expenditure
(September 22, 2026). Available at SSRN: https://t.co/gjDeGvfrZm or https://t.co/UNoQOsBTmO
Post-Earnings Drift in the Point-in-Time S&P500 universe across different sector constituents, different holding periods, different entry points.
https://t.co/b70mc4w3Fr
https://t.co/IfhqiIX13U
Post-Earnings Drift in the Point-in-Time S&P500 universe across different sector constituents, different holding periods, different entry points.
https://t.co/IfhqiIX13U
Post-Earnings Drift in the Point-in-Time S&P500 universe across different sector constituents, different holding periods, different entry points.
QuanterLab
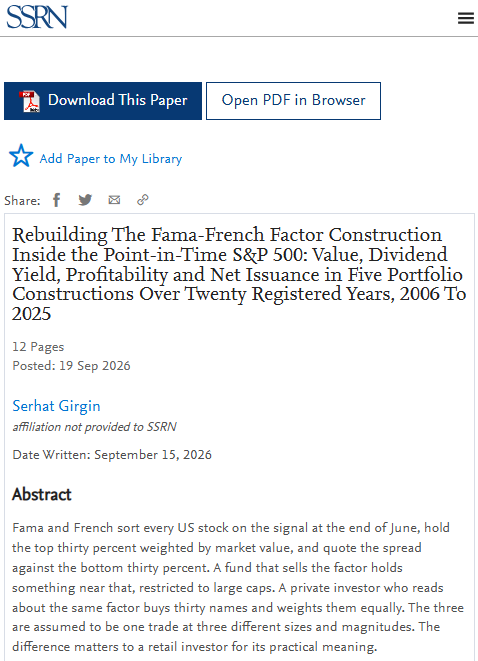
Rebuilding The Fama-French Factor Construction Inside the Point-in-Time S&P 500 Available at SSRN: https://t.co/jYjLyXEy4O or https://t.co/BkGvG7hEiq
QuanterLab
Rebuilding The Fama-French Factor Construction Inside the Point-in-Time S&P 500 Available at SSRN: https://t.co/jYjLyXEy4O or https://t.co/BkGvG7hEiq
Rebuilding the Fama-French factor construction inside the point-in-time S&P 500: value, dividend yield, profitability and net issuance, 2006 to 2025
https://t.co/6VNIsH5lRd