1/8 CagriSema data – better than the market reaction
This is a longer analyse of the CagriSema Redefine 1 data.
Enjoy your reading and please don’t hold your comments back.
"I will throughout this analyze try and show what that “extra” potential WL looks like.
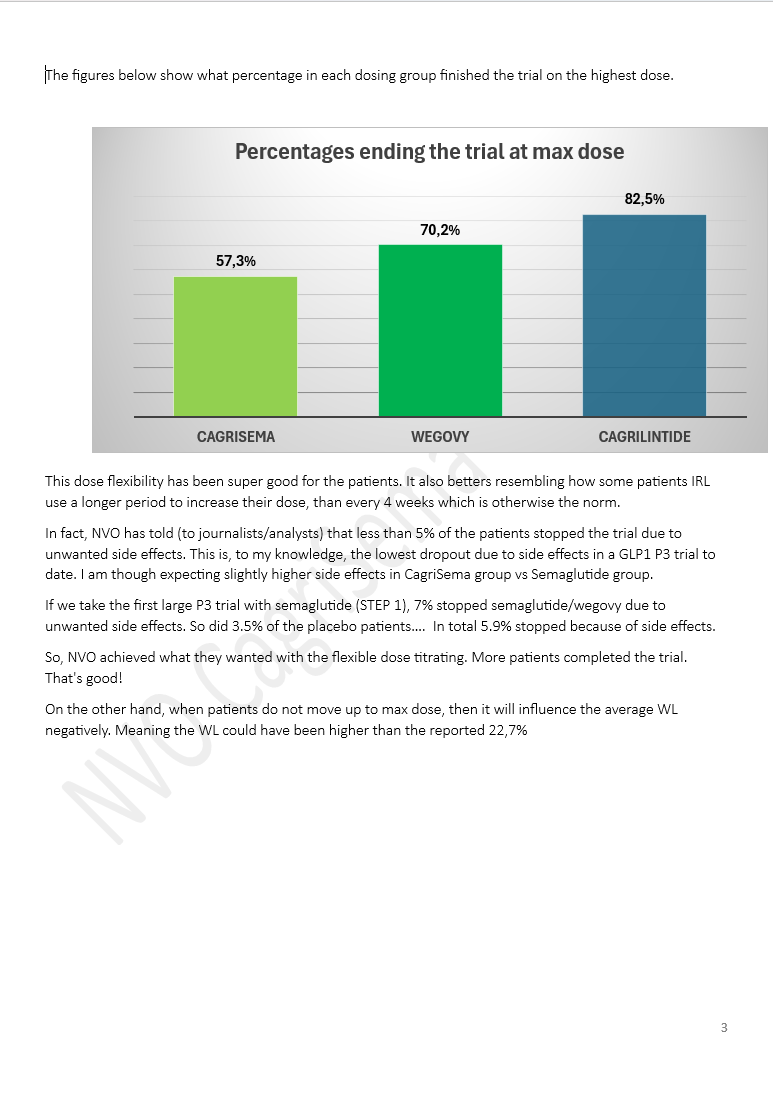
I also zoom in at one of the most often conclusions I have seen. “Only 57% finished the trial at max dose CagriSema. That means it had seriously tough side effects”.
I believe that is both a hasty and wrong conclusion."
$NVO $LLY $VKTX $GUBRA $ZEAL
@GLP1
I don’t know who have started this “rumour” on Betaville, but it’s all made up. Probably by someone who are under pressure with current marked tumbling.
$LLY has zero interest in buying VKTX at BL inflated prices.
LLY has a very wide pipeline and don’t need to buy any late stage obesity assets. They do early stage R&D deals within obesity for assets that brings in new MoA and/or new modalities.
If next week stock market continue this weeks downward pressure, then i guees we would start to see big investors (with a seat in the board) looking for exits.
That potential offers the board turned down just few weeks ago, all the sudden looks more attractive.
Is this official LLY trial? How did titration look like.
It’s easy to reduce GI by using slower titration than the approved 4 week schedule. But I’m not aware of any official slower titration that has been included in the label?
The contradiction is a customer wants to see fast results, which in general means a bit faster titration than if you focus on low GI.
The whole investor environment is centred around max WL in xx weeks.
When cash you buy the most effective you can afford.
With no wegovy HD approved in India then there’s a big WL gap between the two.
I think the more surprising part of India GLP1 business is that branded wegovy still maintains about the same TRx as before patent expiration
Wegovy TRx actually increased the first couple months after patent expiration.
Even though branded wegovy cost up to 6x the cheapest wegovy copy offering ($175 vs $28 for 2.4mg) branded wegovy still maintains its TRx.
Could weight-loss drugs become a game-changer for children living with obesity?
According to the Sunday Independent, Professor Donal O'Shea, consultant endocrinologist, believes GLP-1 treatments could eventually benefit children as young as 3 or 4.
The discussion follows promising results from Novo Nordisk's Wegovy trial in children aged 6 to under 12.
Nearly 80% achieved a BMI reduction of more than 10%, while 40% were no longer classified as obese after 68 weeks.
Novo plans to seek FDA approval for this younger age group next year.
The argument is that childhood obesity should be treated during childhood, rather than waiting until adulthood — particularly given its potential impact on physical health, mental well-being, school performance and social development.
Source: Sunday Independent, November 22, 2026.
$NVO $LLY
Ja de udvikler og tester jo hele tiden nye modeller.
Men som du også nævner mange gange i podcasten, så er konkurrencen så stor mellem de forskellige mastodonter at de ikke kan undlade at frigive nye modeller i lang tid efter de er udviklet. For så løber OpenAI, Gemini eller en 3. Bare med indtjeningen i det kommercielle marked.
Og når nogle Pharma kunder har store aftaler med flere af ANT primære konkurrenter, og derfor har flere modeller at vælge blandt, så er det altså ikke sådan ANT har et kæmpe forspring i forhold til deres store kunder.
Tror du missede den part om at Novo (og mange andre BP) allerede har aftale med ANT så de har samme capability som ANT + adgang til andre modeller fra OpenAI mf. Så de kan vælge den bedste model til den specifikke opgave.
Som du selv ofte siger så har hver AI model deres styrker. Hver deres arbejdsområde hvor de i en given periode er bedst, mens en konkurrent er bedst indenfor en anden type opgave hvor ANT er knap så god.
$NVO er ikke skræmt over AI. De embracer den fuldt ud og har allerede implementeret det på tværs af virksomheden. Både i R&D, produktion, salg og som administration.
Og der dukker konstant områder op hvor AI enten kan udføre det specifikke arbejde hurtigere eller mere præcis. Så implementeres det.
AI kan automatisere utrolig mange opgaver og har allerede skåret meget tid af udvikling af nye molekyler, test af dem mm. Men du udvikler ikke nye lægemidler udelukkende med IT folk.
ANT skal nok få nogle gennembrud.
Lige som der er en masse andre biotech selskaber der løbende finde nye biologiske processer, får udviklet molekyler der enten aktiverer eller deaktiverer processen, valideret target mm.
Men nej ANT satsning i life science og udvikling af ny medicin er ikke noget fuldstændig mindblowing epokegørende og helt unikt for dem. For de sælger allerede den tech til Pharma, PLUS flere af ANT kunderne også har samme type aftale med bl.a. OpenAI. Så de kan plukke det bedste på tværs af AI frontrunners. Og de har hele tiden adgang til de nyeste modeller.
@JCanNuSH@KontraInvest Thanks for your thought and insight.
I don’t understand their management. Why they would sell a product that’s closer to taking a placebo than getting anything remotely like Tirzepatide effect.
Well except that management is top greedy. But I hope this backfires
@JCanNuSH@GregoryMaysMD@Gramps_bloomers Yea we vials fall immediately after KwikPen launch.
But above 7.5mg KwikPen becomes to expensive vs vials. Don’t think there’s much cash pay above.
KwikPen accelerated significantly after Bridge started.
@JCanNuSH@GregoryMaysMD@Gramps_bloomers Vials TRx still a bit higher than KwikPen. But only a matter of time before KwikPen will pass vials
KwikPen is behind most of the growth