Rajshree Polypack (#RPPL) looks dirt cheap at current valuations! 👀
FMCG recovery, easing raw material costs & Olive Ecopak growth — potential to double by FY28? 🚀
Whether I sold or hold FCL has nothing to do with my assessment. 😂
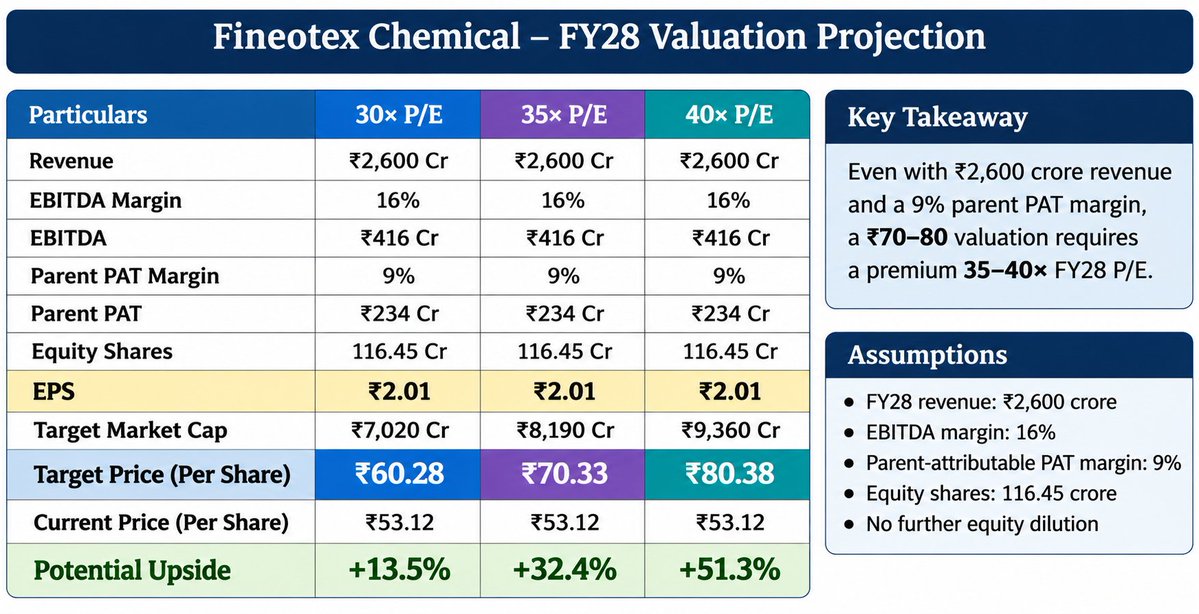
The question isn't just what CCT delivered on a ₹96 Cr investment, but what is already priced in.
Look at the equity dilution, current P/E and earnings attributable to FCL shareholders.
Even assuming ₹2,600 Cr FY28 revenue and 9% PAT margin, EPS is ~₹2. At 30–40× P/E, valuation works out to ₹60–80.
Investing is about future growth relative to current valuation, not just management delivering promises.
And I'm perfectly okay being wrong. That's part of investing!
Did I say anything about the future? Anyway, I sold FCL two days ago.
One reason the stock corrected from ₹60 to ₹52 was that the Street wasn't expecting strong results.
The long-term outlook still looks promising, but there are several moving parts, including the Democrats' win and cooling crude prices.
@TheTradeDoctr12@RaajendraGuupta The stock already priced for CrudeChem's ambitious annual projections.
Expectations were for stronger growth and improving margins, but the numbers have failed to deliver. With crude sliding again, another overhang emerges for the oilfield chemicals business.
My observation: Better to stay away from these groups.
1. Shapoorji Pallonji Group – One of the biggest wealth destroyers.
2. Reliance – Avoid listed subsidiaries/associates.
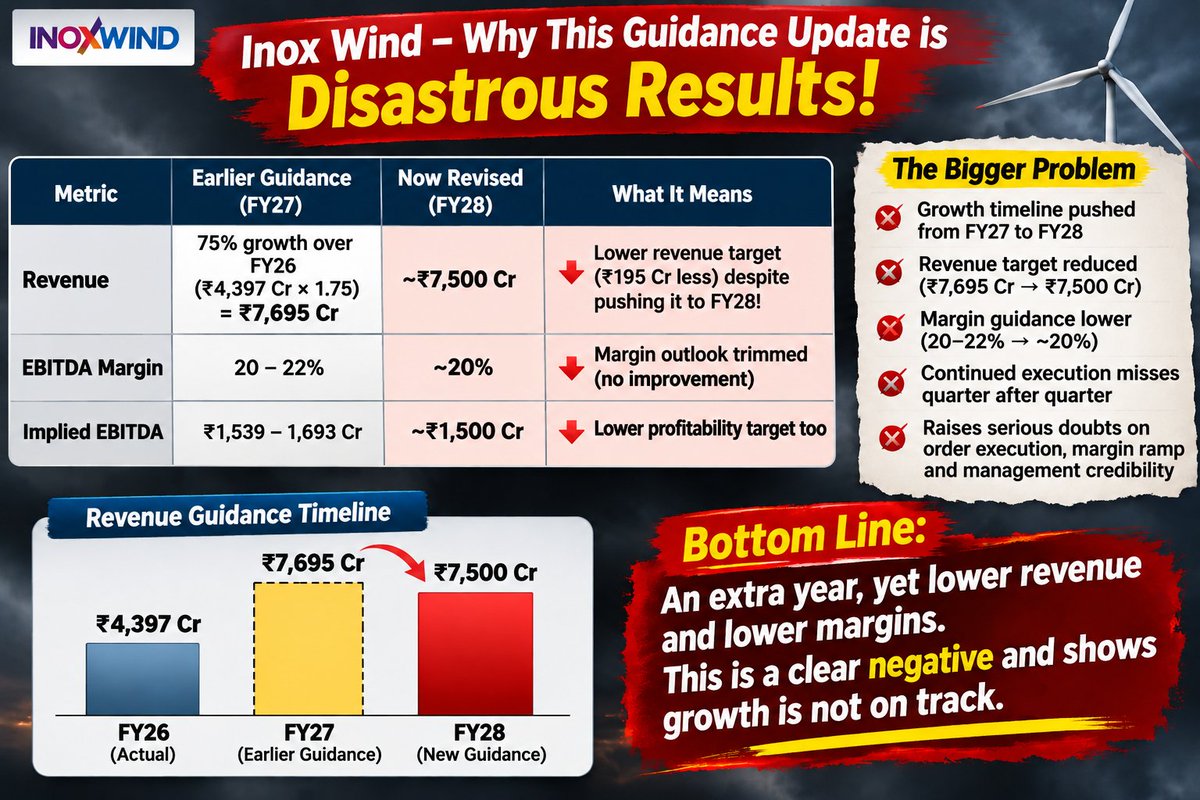
3. INOX Group – Highly sceptical after the kachra INOX Wind has delivered over the last 2 years.
📉 Monday could be a rough day for my portfolio!
Disappointing results from these portfolio stocks:
🔻 Inox Wind
🔻 DCAL
🔻 John Cockerill India
🔻 Rishabh Instruments
🔻 POCL Enterprises
Monday looks painful! 😬
⚠️ Anyone buying EMS stocks now, be careful!
The low-hanging fruits have already been picked.
Every other company is entering EMS. Competition will intensify, margins could compress, and making money from these stocks may get much tougher.
📈 Industry growth ≠ Stock returns!
Inox Wind never disappoints! 😏
Ye toh lagta hai apna NPA ban gaya hai! 😂📉
Biggest positive takeaway from the results? The resignation of Sanjeev Agarwal 🫡
One company where both FIIs and DIIs seem to be losing faith — Inox Wind! 📉 From a promising renewable energy story to a wealth destroyer. One of the worst managements in my view. Shareholders ko bas ullu banaya! Big promises, poor shareholder returns. #InoxWind#StockMarket
Amazing🙏
Exactly what I highlighted earlier:
📈 Better realisations
⚙️ Higher capacity utilisation
💰 Operating leverage kicking in
Earnings growing much faster than revenue!
#OrientBell
🏏 Orient Bell -- Can hit the ball out of the park?
Kajaria's Q2 FY27 performance signals improving tile demand, realisations & margins.
The Orient Bell thesis:
📈 Pricing gains + better capacity utilisation
🔥 Operating leverage driving EBITDA margin expansion
💰 Potential for earnings to grow much faster than revenue
#OrientBell #SmallCaps